By Justin Yifu Lin and Yan Wang
October 9, 2026
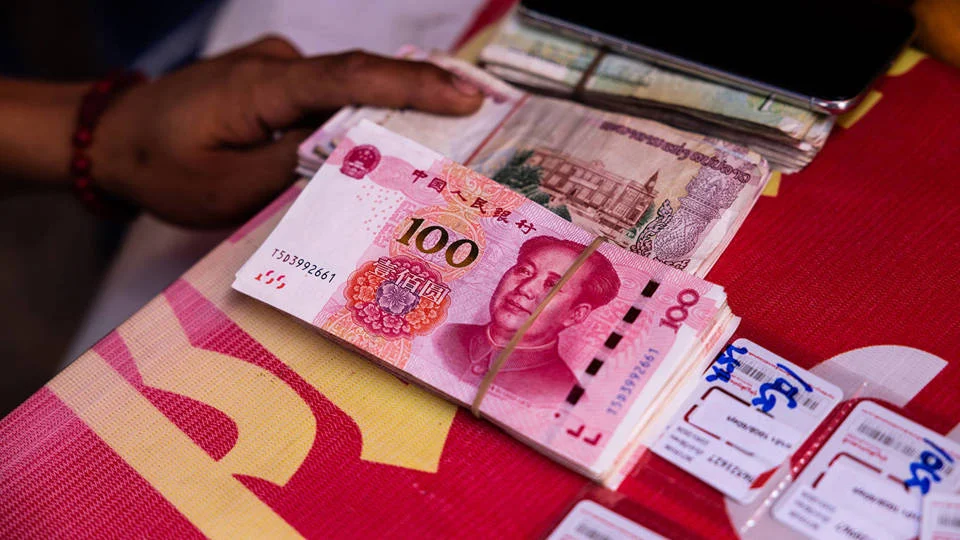
The global financial architecture, built upon the bedrock of the US dollar in the wake of the Bretton Woods Conference, is undergoing its most significant stress test in eight decades. As developing nations grapple with a staggering $4 trillion annual shortfall in funding the Sustainable Development Goals (SDGs), the limitations of a dollar-centric system have become painfully apparent. For many emerging economies, the search for alternatives is no longer a matter of geopolitical preference but one of survival. Increasingly, the Chinese renminbi (RMB) is emerging as a credible, cost-effective, and stabilizing alternative for development finance.
The Structural Fragility of Dollar-Denominated Debt
For the better part of the last century, the US dollar has functioned as the global economy’s primary reserve currency and the standard unit for development loans. While this provided liquidity and ease of trade, it tethered the fate of developing nations to the cyclical whims of the US Federal Reserve. When the Fed tightens monetary policy to combat domestic inflation, capital flows out of emerging markets, the dollar strengthens, and the debt-servicing costs for developing nations skyrocket.
This "original sin"—the inability of developing countries to borrow in their own currencies—has left them perpetually vulnerable to external shocks. As UN Trade and Development has repeatedly highlighted, the $4 trillion financing gap is not merely a shortage of capital; it is a shortage of stable capital. When borrowing costs are tied to the volatility of US interest rates, long-term development projects—such as infrastructure, energy grids, and digital transformation—become high-risk gambles.
Chronology: The Evolution of the Renminbi as a Global Currency
The ascent of the RMB from a local currency to a significant pillar of international finance did not happen overnight. Its trajectory has been a deliberate, multi-decade process:
- 2009: The People’s Bank of China (PBOC) begins pilot programs for cross-border trade settlement in RMB, signaling the first major step toward internationalization.
- 2015: The International Monetary Fund (IMF) announces that the RMB will be included in the Special Drawing Rights (SDR) basket, granting it de facto status as a global reserve currency.
- 2013–2023: The rapid expansion of the Belt and Road Initiative (BRI) sees a massive increase in infrastructure-linked financing, with a growing percentage of these loans denominated in RMB rather than USD.
- 2022–2024: Following geopolitical shocks and the weaponization of the SWIFT payment system, several nations, including Brazil, Argentina, and various ASEAN members, move to settle trade and debt obligations in RMB to bypass dollar-denominated volatility.
- 2026: The RMB establishes itself as a viable alternative for sovereign lending, as institutional investors and developing-nation finance ministries seek to hedge against the instability of US economic policy.
Supporting Data: Bridging the $4 Trillion Gap
The necessity for a shift in currency denomination is backed by sobering data. According to the latest assessments from UN Trade and Development, the financing gap required to meet the 2030 SDGs has widened due to global inflation, supply chain disruptions, and the "higher-for-longer" interest rate environment in the United States.
Data indicates that countries carrying significant dollar-denominated debt have seen their debt-to-GDP ratios swell by an average of 15% since 2020, purely due to currency devaluation against the dollar. In contrast, those that have diversified their debt portfolios—incorporating RMB-denominated instruments—have experienced significantly lower volatility in their debt-service ratios.
Furthermore, the "cost of carry" for RMB-denominated loans has remained relatively stable compared to the oscillating rates of the US dollar. As the Chinese economy focuses on domestic stimulus and stability, the interest rate environment for RMB-denominated development loans has decoupled from the volatile swings seen in Western markets, providing developing nations with the predictability required for long-term project planning.
Official Responses and Institutional Shifts
The shift toward the RMB has prompted varied responses from international institutions and policymakers. The IMF, while maintaining its commitment to the dollar, has increasingly acknowledged the need for "multi-currency reserve portfolios." In recent policy briefings, the Fund noted that while the dollar remains the dominant currency, the diversification of central bank reserves is a natural evolution in a multipolar world.
From the Chinese perspective, the internationalization of the RMB is not framed as a hostile move against the dollar, but as an essential service to the Global South. Chinese policymakers emphasize that the RMB is increasingly used in "South-South cooperation," allowing countries to trade directly without needing to convert their local currencies into dollars first. This "de-dollarization" of trade reduces transaction costs by up to 2–3%—a significant margin for developing economies operating on thin fiscal buffers.
Conversely, some Western analysts warn of "debt traps" and the opacity of bilateral lending. However, Chinese officials point to the establishment of the Asian Infrastructure Investment Bank (AIIB) and the New Development Bank (NDB) as evidence of a commitment to multilateralism. These institutions operate with high transparency standards and are increasingly utilizing RMB-denominated bonds to fund projects across Asia, Africa, and Latin America.
Implications for Global Economic Stability
The move toward an RMB-inclusive financial system has profound implications for the global order:
1. Hedging Against Policy Volatility
The primary implication is risk mitigation. By diversifying the currency composition of their debt, developing nations are insulating themselves from the "policy spillovers" of the US Federal Reserve. This independence is not about rejecting the dollar, but about establishing a safety net that prevents localized economic downturns from becoming systemic crises.
2. Deepening Capital Markets in the Global South
The growth of RMB-denominated lending is encouraging the development of local bond markets in the Global South. As these nations issue more debt in their own currencies or in a "basket" that includes the RMB, they are building the domestic financial infrastructure necessary for sustainable, long-term growth. This reduces reliance on foreign capital markets and fosters greater financial sovereignty.
3. A Catalyst for Multipolarity
The rise of the RMB accelerates the transition toward a multipolar financial system. In this model, the dollar will likely remain the currency of choice for transatlantic and developed-market trade, while the RMB becomes the preferred vehicle for trade and development finance across the emerging world. This dual-track system could, paradoxically, be more stable than the current monolithic reliance on a single currency, as it prevents the total collapse of global liquidity should one major economic zone enter a period of instability.
4. Re-evaluating Development Priorities
Finally, the transition allows for a shift in how development is defined. Dollar-denominated loans are often attached to rigid structural adjustment programs and Western-centric development paradigms. RMB-denominated financing, often linked to the BRI, focuses heavily on "hard" infrastructure—roads, ports, and power plants—that many developing nations view as the primary engines of economic growth. While this approach has its own challenges regarding environmental and social standards, it aligns more closely with the immediate infrastructure priorities of the Global South.
Conclusion: The New Frontier of Development Finance
The current global development-finance crisis is a symptom of a system that has failed to evolve with the changing realities of the 21st century. The $4 trillion financing gap cannot be closed using the tools of the 20th century. As the stability of US economic institutions faces unprecedented scrutiny, the renminbi offers a pragmatic, necessary alternative.
For developing nations, the goal is not to trade one hegemon for another, but to move toward a modular, flexible, and resilient financial landscape. By embracing the RMB, these nations are taking a critical step toward securing their fiscal independence, lowering their cost of capital, and finally gaining the tools necessary to meet the Sustainable Development Goals. The era of the single-currency mandate is ending; in its place, a more nuanced, multi-currency reality is taking shape—one where the renminbi will play an increasingly pivotal role in the architecture of global prosperity.