The landscape of corporate sustainability reporting has long been a fragmented mosaic of voluntary frameworks, conflicting regional mandates, and bewildering acronyms. For global multinationals, the cost of compliance has been high, and the utility of data for investors has often been low. However, a significant shift is underway. Under the guidance of the International Sustainability Standards Board (ISSB), the global business community is moving toward a unified "global baseline" for disclosing sustainability-related risks and opportunities that directly impact financial performance.
As of late 2026, the ISSB’s framework—comprising the IFRS S1 for general sustainability disclosures and IFRS S2 for climate-related reporting—has gained unprecedented traction. With nearly 50 nations moving to adopt these standards into their mandatory reporting regimes, the ISSB is rapidly evolving from an ambitious project into the de facto "global passport" for corporate transparency.
The Genesis of a Global Standard
The ISSB was born out of the 2021 UN Climate Change Conference (COP26), a response to the chaotic state of environmental, social, and governance (ESG) reporting. Investors and regulators alike recognized that without a consistent, comparable, and reliable set of standards, capital could not be efficiently allocated toward sustainable transition.
By anchoring itself within the International Financial Reporting Standards (IFRS) Foundation—the same entity responsible for the world’s most widely used accounting standards—the ISSB bypassed the credibility hurdles that often plague new regulatory bodies. It did not seek to reinvent the wheel; instead, it synthesized the best elements of existing frameworks, such as the Task Force on Climate-related Financial Disclosures (TCFD) and the Sustainability Accounting Standards Board (SASB). This "evolutionary" rather than "revolutionary" approach allowed it to gain immediate buy-in from the global investment community.
Chronology: From Concept to Global Baseline
- November 2021 (COP26): The IFRS Foundation announces the creation of the ISSB to develop a comprehensive global baseline of sustainability disclosures.
- June 2023: The ISSB officially issues its inaugural standards, IFRS S1 and IFRS S2.
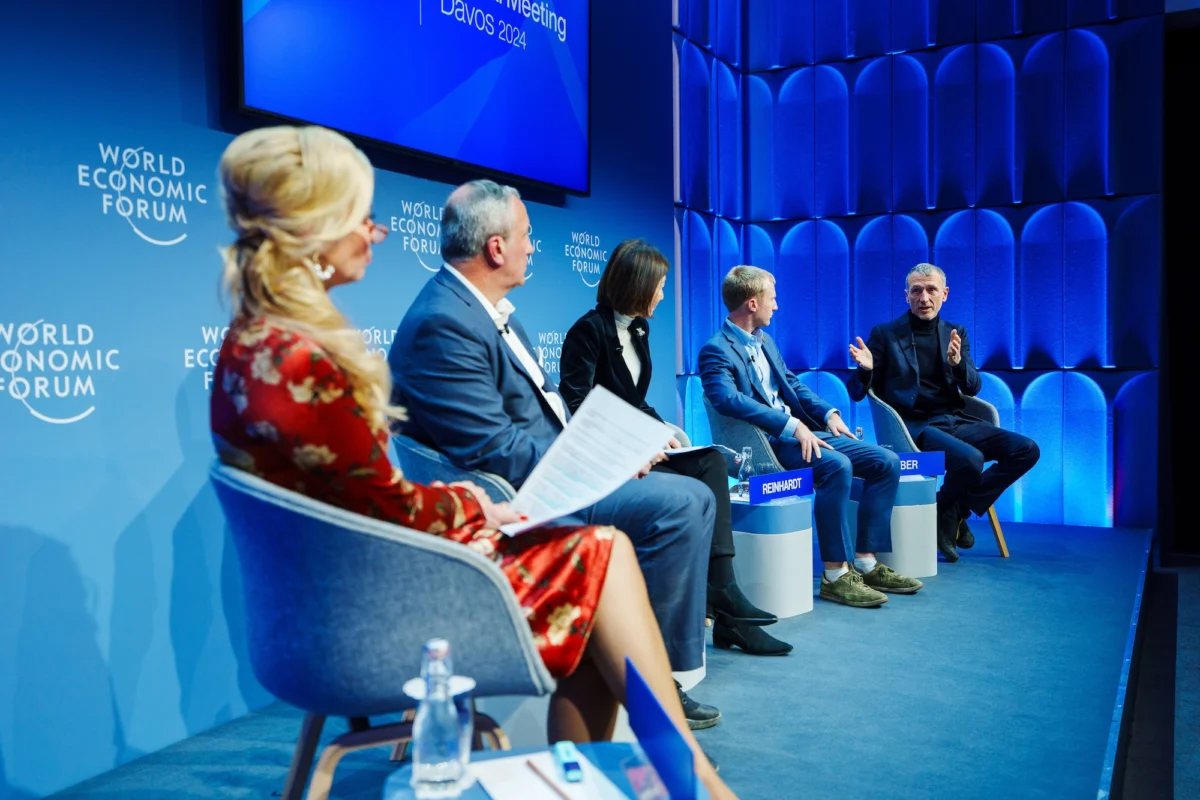
- 2024 (World Economic Forum, Davos): ISSB Chair Emmanuel Faber leads high-profile discussions on the necessity of integrating sustainability metrics into core financial reporting, signaling a pivot toward mandatory, audit-ready data.
- 2025: The IFRS Foundation expands its Jurisdictional Working Group, bringing more nations into the fold to standardize the adoption process.
- June 2026: Various nations, including Brazil, adjust their implementation timelines, highlighting the complexities of moving from voluntary to mandatory reporting.
- Late 2026–2027: The ISSB prepares to launch practice statements on biodiversity and ecosystems, signaling an expansion beyond simple climate metrics into broader nature-related reporting.
The Strategy of "Adoption by Stealth"
The ISSB’s rapid expansion is attributed to its perceived neutrality. In an era of intense geopolitical friction, where sustainability policy is often viewed through a partisan lens, the ISSB offers a "non-political" technical solution.
The European Union’s Corporate Sustainability Reporting Directive (CSRD) has been praised for its ambition but criticized for its complexity and the "confusion" it caused among global businesses. Conversely, the United States has seen a tumultuous period of legislative roll-backs and legal challenges regarding climate disclosure. Amidst this volatility, the ISSB has positioned itself as the "Goldilocks" solution: rigorous enough to satisfy sophisticated investors, yet flexible enough for emerging markets to adopt without triggering domestic political backlash. For many nations in the Middle East, Africa, and Asia, adopting the ISSB standards is a strategic move to "level up" their local markets to meet the expectations of international institutional investors.
The Reality of Implementation: A Patchwork of Variations
While the aspiration is a single global standard, the reality is a fragmented implementation process. No two countries are adopting the ISSB standards in exactly the same way.

The "Cherry-Picking" Phenomenon
Countries like Chile, Malaysia, Nigeria, and Singapore have largely transposed the ISSB standards into their national laws without significant alteration. However, others have applied "local filters."
- The Climate-First Approach: Jordan, for example, has made IFRS S2 (climate) mandatory, while leaving the broader sustainability requirements of IFRS S1 optional.
- The Materiality Deviation: China remains the most notable outlier. By incorporating "double materiality"—which requires companies to report on how they impact the environment, not just how the environment impacts their bottom line—China has created a significant deviation from the ISSB’s primary focus on financial materiality.
- The Assurance Gap: Mexico has imposed an external audit and assurance requirement, a step not currently mandated by the core ISSB framework. Brazil, meanwhile, has vacillated between mandatory and "comply or explain" models, illustrating the difficulty of enforcing these standards in volatile economic climates.
Transition Relief and Timetables
The ISSB originally built "transition relief" into its standards, allowing companies to report only on Scope 1 and 2 emissions in the first year before expanding to include the more difficult-to-calculate Scope 3 (value chain) emissions. Many regulators have extended these timelines to accommodate local industries. Conversely, the United Kingdom’s Financial Conduct Authority opted to strip away this relief for voluntary adopters, setting a strict trajectory: direct emissions by 2028, value chain emissions by 2029, and full sustainability disclosures by 2030.
Materiality: The Continuing Debate
The fundamental tension in global reporting remains the definition of "materiality." The ISSB adheres to a financial materiality model, prioritizing information that affects a company’s enterprise value. However, the EU’s CSRD model favors double materiality.
In early 2026, there was a brief, intense discussion regarding whether the EU could align more closely with the ISSB. When proposals suggested a potential pathway for integration, significant pushback from French financial institutions—who feared that "investor-focused" disclosures would ultimately sideline impact-related data—resulted in the proposals being shelved. This failure to reach a consensus underscores a persistent truth: the "impact" of a company on the planet and the "financial risk" that the planet poses to the company are increasingly seen as two sides of the same coin, yet the global regulatory community remains divided on which should take precedence.
Implications for Global Multinationals
For the global enterprise, the ISSB’s momentum represents both a burden and a potential relief. While the prospect of aligning with a single standard is enticing, the current "patchwork" of regional variations means that compliance remains a complex, multi-jurisdictional exercise.
Practical Advice for Businesses:
- Map the Landscape: Before committing to a specific reporting framework, determine the mandatory requirements of your primary operating jurisdictions. If your home market mandates the ISSB, focus your compliance strategy on the local version of the standard.
- Identify the Audience: If you are in a voluntary reporting environment, choose your framework based on your capital providers. If you are seeking to attract global institutional investors who prioritize financial performance, the ISSB’s focus on enterprise value is the gold standard.
- Bridge the Gap: Use the ISSB as a foundational layer, but be prepared to supplement this with local requirements (such as the EU’s CSRD or country-specific assurance mandates) to satisfy regional regulators.
- Prepare for Nature: As the ISSB moves to issue practice statements on biodiversity and ecosystem services, businesses should start preparing their data collection processes now. The "climate-only" era of sustainability reporting is rapidly drawing to a close.
Looking Ahead: The "Global Passport"
The ISSB is not resting on its current successes. With a stated goal of reaching over 50 countries by 2027, the Board is actively working through its Jurisdictional Working Group to reconcile the variations currently popping up around the globe. The goal is to move from a "patchwork" to a truly interoperable "passport" that allows a report filed in Tokyo to be equally understood and trusted in London or New York.
As the ISSB expands its reach into the realms of biodiversity and sector-specific guidance via the SASB standards, the regulatory environment is becoming more structured, yet more demanding. For the CFOs and Chief Sustainability Officers of the world, the message is clear: the age of "sustainability reporting" as a public relations exercise is over. It is now a core component of financial reporting, and the ISSB is setting the ledger for the future.