The Australian and New Zealand startup landscape has witnessed a significant uptick in investment activity this week, with the "payments technology" sector emerging as the undisputed focal point of venture capital interest. As economic headwinds shift and interest rates stabilize, investors are increasingly pivoting toward platforms that solve the age-old friction of business-to-business (B2B) liquidity and transactional efficiency.
This week, three prominent players—Archa, RedOwl, and Qippay—have secured critical funding, signaling a robust appetite for innovation in the financial services vertical. While the broader economic climate remains cautious, these raises underscore a trend: the market is hungry for scalable, tech-led solutions that empower SMEs to bypass the rigid, often prohibitive traditional banking structures.
Main Facts: The Catalyst for Growth
At the center of this week’s news is Melbourne-based fintech Archa, which has successfully secured an $11 million capital injection. This funding is earmarked for the enhancement of its signature business credit card platform, a tool designed specifically to provide SMEs with seamless access to working capital.
What makes the Archa raise particularly noteworthy is the caliber of the backing. The round attracted a sophisticated cohort of investors, including high-profile executives and founders from industry giants such as Zip, The Iconic, BetaShares, and Netspace. Furthermore, the presence of US-based The Fintech Fund and former Macquarie Group executives signals a growing international confidence in the maturity of the Australian fintech ecosystem.
While Archa leads the headlines, the broader narrative involves a shift in how businesses handle their capital. The common thread across these three raises is the move away from personal guarantees and toward credit-scoring models based on cash flow and transactional data, rather than individual balance sheets.
Chronology of the Raise
The recent activity follows a period of strategic consolidation in the fintech sector. Throughout early 2026, many startups were forced to focus on runway preservation and unit economics.
- Q1-Q2 2026: A period of "capital discipline" saw these companies refine their product-market fit, shifting away from aggressive customer acquisition toward sustainable, high-margin revenue models.
- September 2026: Early discussions with potential investors began to pick up as inflation metrics in Australia and New Zealand began to show signs of cooling.
- October 2026 (The Current Week): The formal closing of the three funding rounds was announced, representing the culmination of months of negotiations. The liquidity event for Archa, in particular, marks a transition from a growth-at-all-costs phase to a platform-expansion phase.
Supporting Data: The SME Funding Gap
To understand why these payments companies are attracting such significant capital, one must look at the SME funding gap. According to data from industry regulators and private research firms, small-to-medium enterprises in the ANZ region continue to face systemic hurdles when seeking traditional bank financing.
The "Personal Guarantee" Hurdle
Traditional lenders often demand personal guarantees from business owners to secure credit facilities. This is a significant friction point for entrepreneurs who wish to protect their personal assets while growing their businesses. Archa’s model, which focuses on providing working capital without these requirements, directly addresses a multi-billion-dollar pain point.
Market Penetration
The digital payments market in Australia is projected to reach a transaction value of over $150 billion by the end of 2027. Fintechs like Archa, RedOwl, and Qippay are positioning themselves to capture a larger share of this pie by providing integrated software that handles not just the transaction, but the reconciliation, the credit, and the reporting in a single interface.
Official Responses and Strategic Outlook
While the companies have remained somewhat tight-lipped regarding specific valuations—citing competitive sensitivity—the sentiment from leadership is one of optimism.
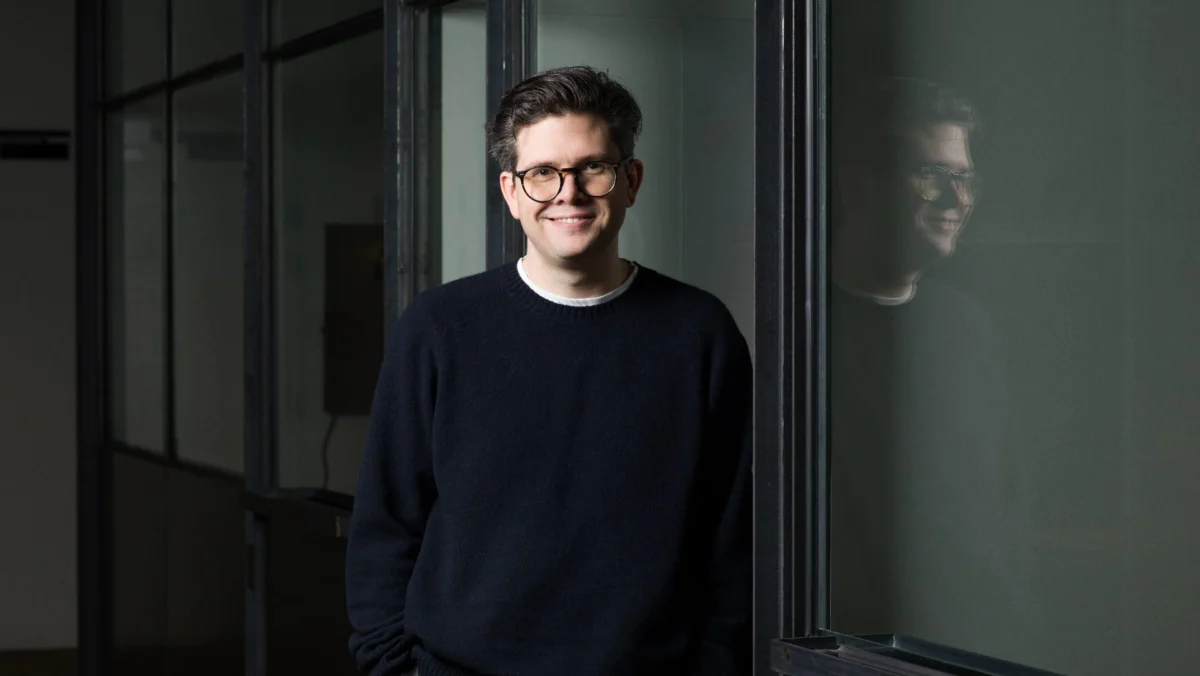
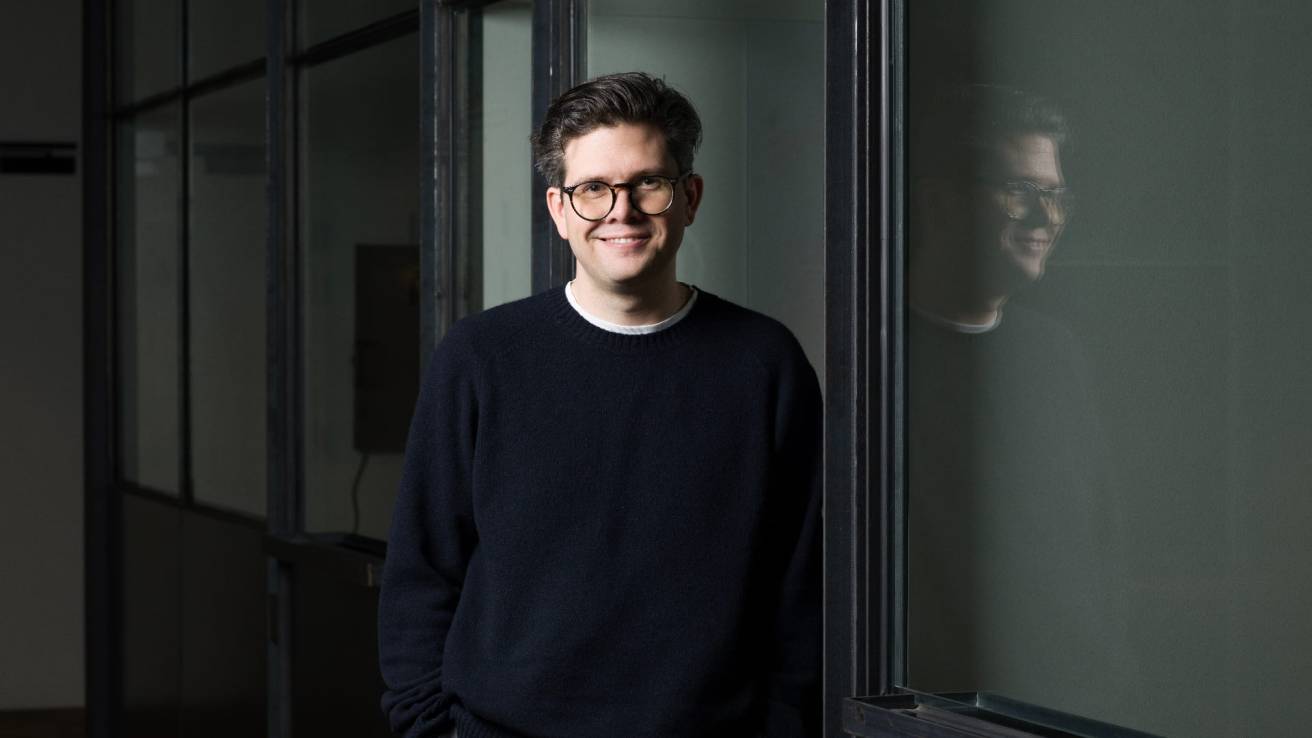
Oliver Kidd, founder of Archa, has emphasized that the latest capital will be instrumental in scaling the product suite. In comments provided to investors, the focus was squarely on "removing the friction of business spend." The company aims to integrate more deeply into the accounting software stacks that SMEs use daily, such as Xero and MYOB.
Investors have also weighed in on why this sector remains a priority. A representative from a participating firm noted, "We aren’t just looking for another payment gateway. We are looking for infrastructure plays. The companies that are succeeding now are the ones that are becoming the operating system for the small business."
Implications for the Broader Economy
1. The Democratization of Credit
The most significant implication of these raises is the democratization of credit. By utilizing alternative data sources—such as real-time transactional velocity and payment patterns—fintechs can provide credit to businesses that traditional banks might deem "too risky" or "too small." This is likely to boost the overall economic velocity of the SME sector, allowing for faster inventory cycles and more flexible hiring practices.
2. A Shift in Banking Competition
The traditional "Big Four" banks in Australia and New Zealand are facing a dual-threat. On one side, they are seeing their market share eroded by these agile, API-first startups. On the other, they are being forced to innovate their own digital offerings. This competition is a net positive for the consumer, leading to lower fees, faster settlement times, and more user-friendly interfaces.
3. The Role of Cross-Border Collaboration
With US-based investors like The Fintech Fund taking a seat at the table, it is clear that the ANZ fintech scene is no longer an isolated pond. It is becoming an integral part of the global fintech supply chain. This inflow of international capital brings not just money, but also access to global markets and operational expertise that can help local startups scale across borders.
4. Regulatory Vigilance
As these companies grow, they will inevitably face increased regulatory scrutiny. The Australian Securities and Investments Commission (ASIC) and other regional bodies are keeping a close watch on how these firms handle credit risk. The challenge for companies like Archa will be to maintain their rapid growth while adhering to the stringent compliance requirements that govern the financial services sector.
Conclusion: What Comes Next?
The success of these three raises in a single week is a testament to the resilience of the startup ecosystem in Australia and New Zealand. While the "easy money" era of 2021 may be behind us, the "smart money" era has clearly arrived. Investors are no longer throwing capital at vague concepts; they are backing companies with clear, actionable solutions to tangible business problems.
As these fintechs deploy their new capital, the coming 12 to 18 months will be critical. We can expect to see a surge in product updates, potential M&A activity, and perhaps even a move toward deeper integration with international payment rails. For the small business owner, the outlook is promising: a future where managing cash flow is less of a administrative burden and more of a strategic advantage.
The payments technology sector has set the pace for the remainder of the year. Whether this momentum can be sustained in the face of shifting global economic policies remains to be seen, but for now, the message from the venture capital community is clear: in the world of B2B finance, efficiency is the new currency.