Shares of Marten Transport (NASDAQ: MRTN) plummeted 7% during Friday’s midday trading session, a stark reflection of investor disappointment following the release of the company’s third-quarter 2026 financial results. As the only publicly traded carrier specializing almost exclusively in refrigerated transport, Marten serves as a critical bellwether for the broader cold-chain logistics industry. The latest report reveals a complex narrative: while underlying supply-demand fundamentals are beginning to show signs of improvement, the company is struggling to overcome persistent inflationary pressures, including rising fuel costs and escalating health insurance expenses.
The Core Financial Performance
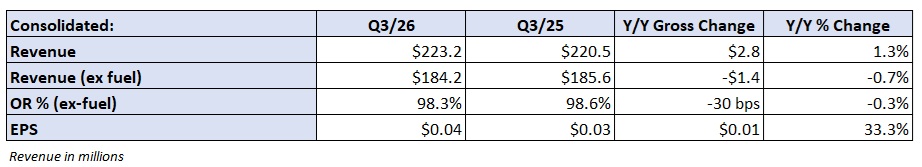
Marten Transport, headquartered in Mondovi, Wisconsin, reported net income of $2.9 million, or 4 cents per share, for the quarter ending September 30, 2026. While this represents a marginal improvement of one penny over the same period in 2025, it fell significantly short of consensus analyst expectations, which had anticipated earnings closer to 6 cents per share.
The primary culprit for the earnings miss was a combination of higher operational costs. The company noted that increased payroll—driven by strategic driver pay raises—and mounting fuel and insurance expenditures created a significant drag on the bottom line. These expenses resulted in a $3.7 million hit to net income, equating to approximately 4.5 cents per share. This financial erosion occurred despite a 1% year-over-year increase in consolidated revenue, which totaled $223 million. It is worth noting that this revenue figure was impacted by the strategic 2025 divestiture of its intermodal unit to Hub Group (NASDAQ: HUBG), which removed $9.9 million from the company’s top-line revenue compared to the previous year.
Chronology of Operational Challenges
The third quarter of 2026 has been defined by a "tightening" of the truckload market, a trend that Marten has navigated through aggressive fleet management. Throughout the summer and into the early autumn, the company focused on optimizing asset utilization by reducing its total tractor count, an effort to improve margins despite lower total volume capacity.
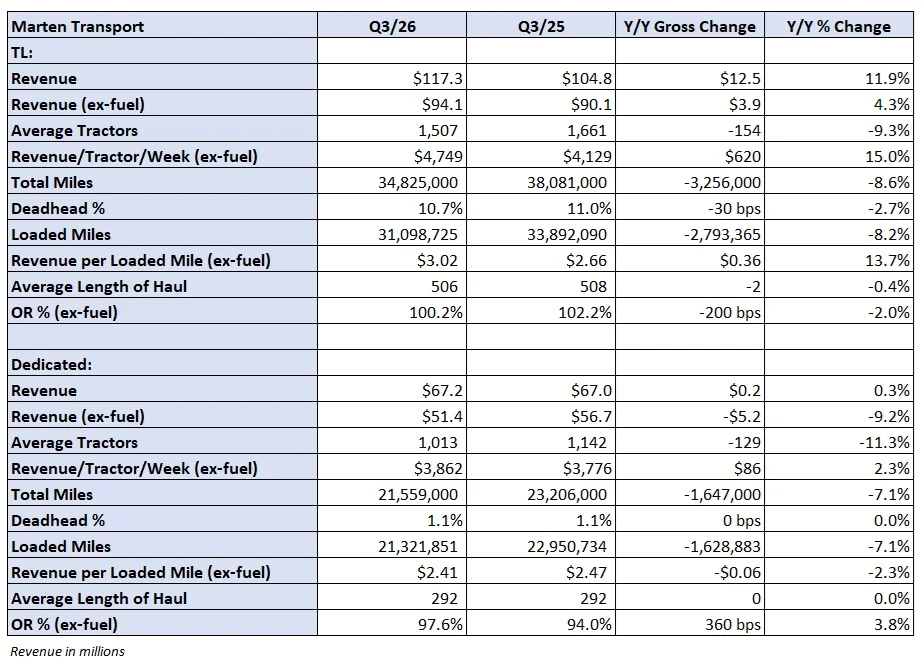
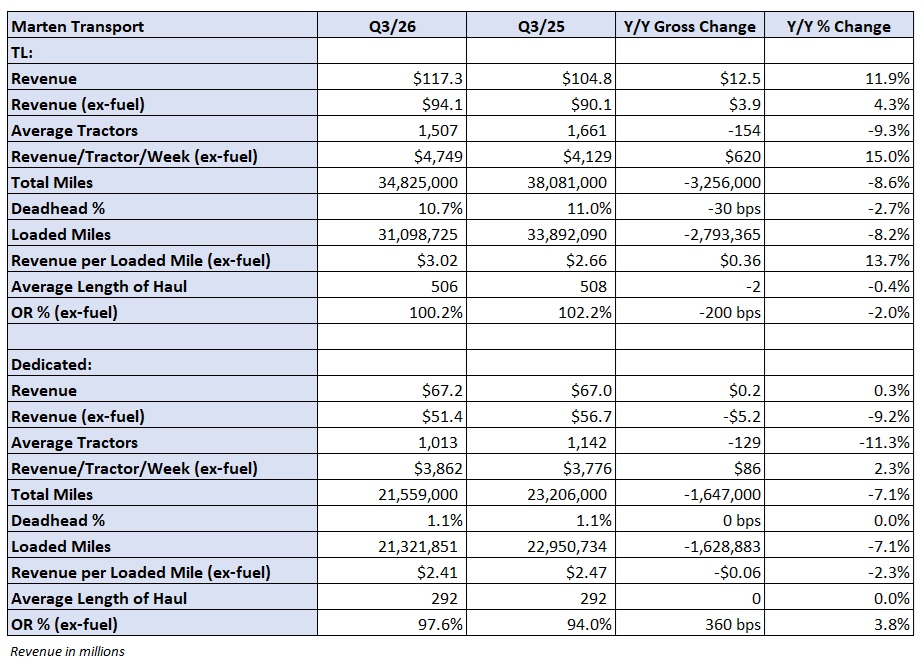
By late September, the impact of these decisions became clear. The one-way truckload segment saw revenue rise 12% year-over-year to $117 million. When excluding fuel surcharges, the segment’s growth was a more modest 4%. However, the company successfully increased revenue per tractor per week by 15%, even while operating a fleet that was 9% smaller than in the prior year. This strategy of "doing more with less" is a hallmark of Marten’s current operational philosophy.
Despite these efficiency gains, the segment remained unprofitable, posting an operating ratio (OR) of 100.2%—a figure that, while 200 basis points better than the previous year, represented a 280-basis-point decline compared to the second quarter of 2026. This sequential deterioration underscores the difficulty carriers face when attempting to pass on costs in a market still finding its footing after a prolonged freight recession.
Supporting Data: Deep Dive into Segments
Marten’s reporting structure provides a granular look at the health of the temperature-controlled logistics sector. The company’s key performance indicators (KPIs) paint a picture of a company in transition:
Truckload and Dedicated Segments
The dedicated segment, usually a bastion of stability for Marten, saw a 9% year-over-year decline in revenue (excluding fuel). This was largely driven by an 11% reduction in the tractor count. While revenue per tractor (ex-fuel) saw a 2% uptick, it was insufficient to offset the volume losses. The dedicated unit finished the quarter with an OR of 97.6%, a significant 360-basis-point worsening year-over-year and a 220-basis-point decline sequentially.
The struggle in the dedicated segment suggests that even with "premium" service offerings, the company is battling intense pricing pressure from shippers who have become accustomed to the soft freight rates of the past two years.
Brokerage Performance
Perhaps the most stable aspect of the report was the brokerage unit. Revenue remained flat at $39 million. This was achieved through a strategic trade-off: the number of shipments handled dropped by 15%, but the revenue per load increased by 17%. The unit’s OR improved by 110 basis points to 94.8%, matching the performance seen in the second quarter of 2026. This stability in the brokerage space highlights the company’s ability to leverage its network to maintain margins even when transaction volumes fluctuate.
Asset Utilization and Fleet Age
Marten has maintained a disciplined approach to capital expenditure, yet the average age of its tractor fleet has crept up to 2.5 years, compared to 2.2 years in the third quarter of 2025. While this remains a relatively young fleet by industry standards, the shift suggests a cautious approach to equipment replacement cycles amidst the current uncertainty regarding interest rates and residual values.
Official Responses and Executive Outlook
In a move that emphasizes the company’s focus on internal operations over quarterly investor relations, Marten did not host a traditional earnings call. However, Chairman and CEO Randy Marten provided insight into the company’s outlook via a prepared statement.
"The truckload freight market has sharply tightened since earlier this year," Marten stated. "Renewed and enhanced enforcement of federal and state law is removing a meaningful amount of noncompliant and unqualified driver capacity from the marketplace. We are securing higher pricing from our customers for our premium services while enhancing freight quality across our network within these early stages of the freight market upcycle."
Marten’s commentary reflects a broader industry sentiment: that the "shakeout" of the freight market, driven by regulatory pressure on smaller, less-compliant carriers, is finally starting to benefit the larger, more established players. The CEO’s optimism regarding a "freight market upcycle" provides a glimmer of hope for investors, though the market’s immediate reaction suggests that Wall Street is waiting for concrete evidence of this recovery in the bottom line.
Broader Implications for the Logistics Industry
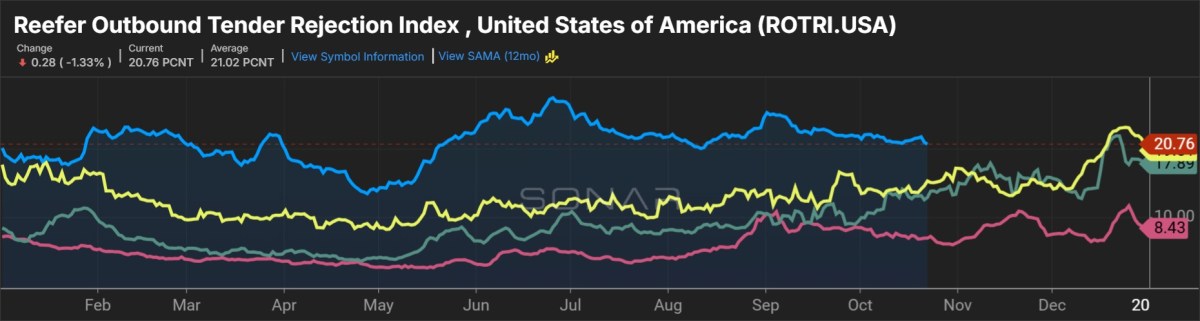
As a "refrigerated pure play," Marten’s performance is scrutinized for what it reveals about the demand for food, pharmaceuticals, and other temperature-sensitive goods. The current state of the market, as tracked by the SONAR Reefer Outbound Tender Rejection Index (ROTRI), confirms that capacity is indeed tightening. When tender rejections increase, it signals that carriers have more leverage to choose their loads and demand higher rates.
However, the disconnect between tighter market conditions and Marten’s earnings miss highlights the "stickiness" of operational costs. Even as pricing power returns, the costs of labor, insurance, and maintenance—all of which have risen significantly over the past 24 months—are making it difficult for carriers to return to the margins of the pre-2023 era.
Furthermore, Marten’s debt-free balance sheet and $83 million in cash flow from operations for the first nine months of 2026 provide a significant safety net. Unlike many of its competitors who are heavily leveraged, Marten has the liquidity to weather continued volatility. This financial resilience is likely why the company remains a favorite among long-term logistics investors, despite the 37% decline in its share price since its mid-June peak.
Looking Ahead: The Future of Freight
The logistics sector is currently undergoing a structural transformation. The upcoming Future of Freight Festival (F3) in Chattanooga, Tennessee, scheduled for late October 2026, will likely focus on these exact themes: regulatory compliance, the use of technology to optimize brokerage, and the shift toward "shipper of choice" models.
For Marten Transport, the path forward is clear: continue to purge inefficient capacity, leverage the tightening reefer market to push for rate increases, and maintain the operational discipline that has kept the company profitable while others have struggled. The third-quarter results may have been a disappointment to those hoping for an immediate rebound, but for those watching the long-term cycle, the report confirms that the "freight winter" is beginning to thaw. Whether that thaw translates into a sustained "spring" for shareholders remains the central question for the remainder of 2026.
Investors will be closely watching the fourth-quarter results for signs that the higher pricing mentioned by the CEO is beginning to outweigh the inflationary pressures that dominated this most recent period. As the industry gathers in Chattanooga for the F3 event, the lessons from Marten’s Q3 report will undoubtedly be at the center of the conversation.