By Antone Gonsalves | Published October 7, 2026
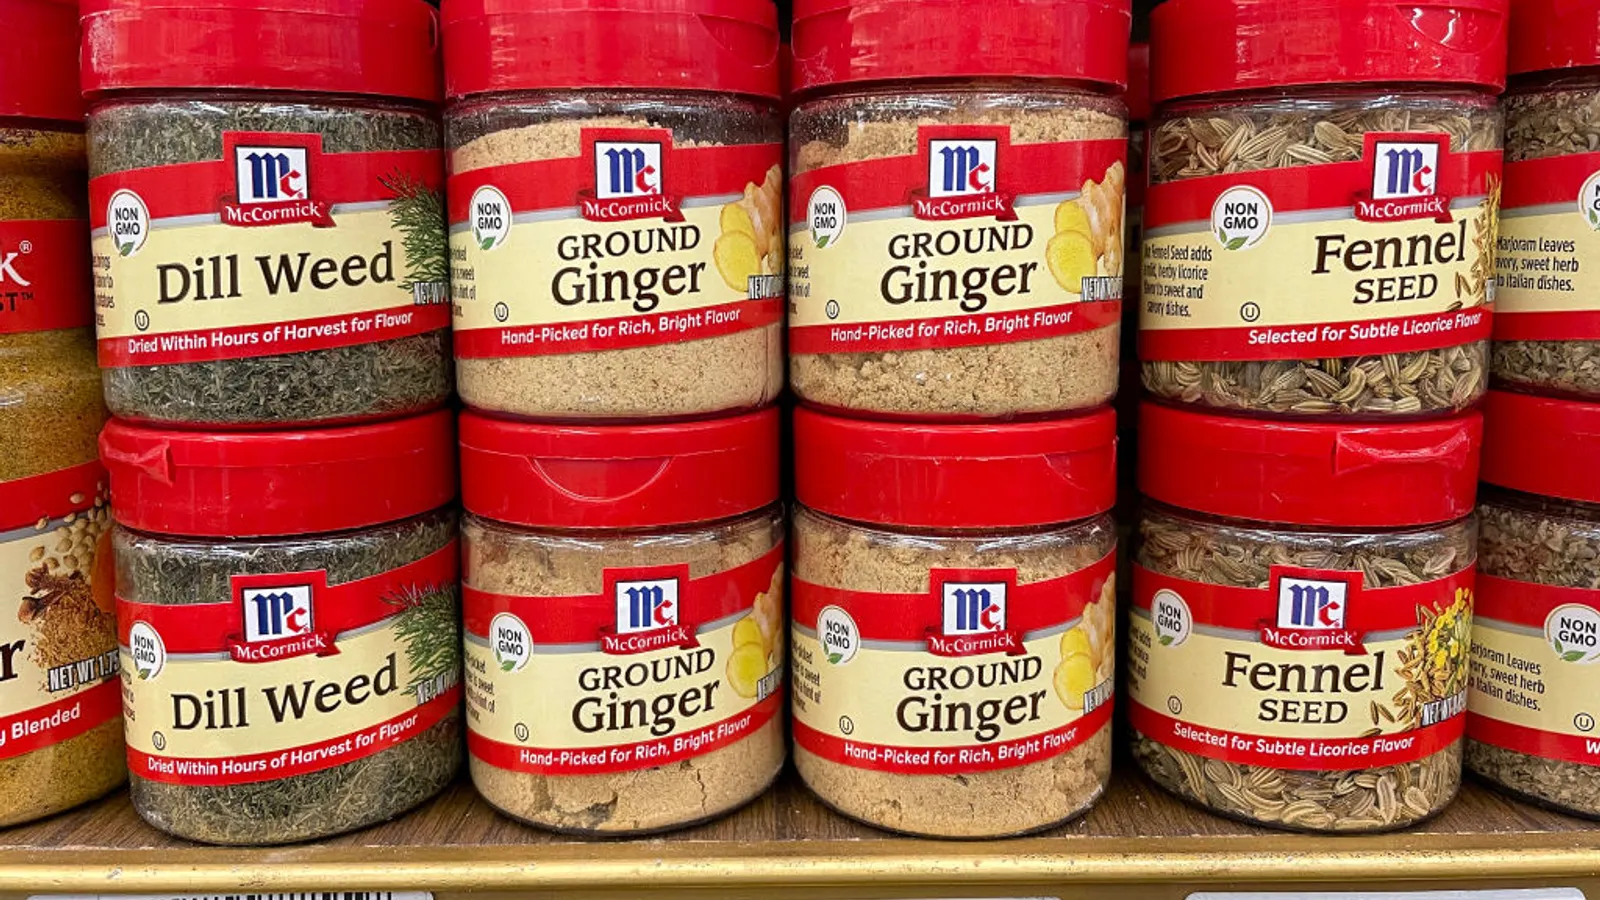
As the global economic landscape faces renewed volatility, major food manufacturers are finding themselves at the epicenter of a complex inflationary storm. McCormick & Company, the global leader in spices, seasonings, and flavor solutions, has joined a chorus of industry giants in signaling that the road to fiscal stability remains obstructed by geopolitical conflict, logistics bottlenecks, and persistent commodity price hikes.
With the shadow of the ongoing Iran war looming over global trade routes and energy markets, McCormick is proactively employing a multi-pronged strategy—leveraging strategic pricing, internal productivity initiatives, and targeted international acquisitions—to shield its bottom line. Despite these hurdles, the company’s recent performance suggests that its operational resilience is paying dividends, even as it looks toward a transformative future involving a massive merger with Unilever.
Main Facts: A Challenging Macro Environment
The current fiscal climate is defined by an interplay of factors that have complicated the supply chain for consumer packaged goods (CPG) companies. For McCormick, the primary challenge remains the unpredictability of raw material costs and the rising expenses associated with global logistics.
McCormick’s management has confirmed that inflation is not a transitory phenomenon but rather a structural pressure expected to persist well into fiscal year 2027. The company is currently mitigating these impacts through three primary levers:
- Strategic Pricing: Adjusting product price points to reflect the realities of increased input costs.
- Productivity Programs: Utilizing the company’s "CCI" (Comprehensive Continuous Improvement) program to extract efficiencies from every corner of the manufacturing process.
- Strategic Acquisitions: The recent move to secure a controlling stake in its McCormick de Mexico subsidiary has provided a geographic and operational buffer, allowing for more streamlined production and distribution in the North American market.
Chronology of Market Instability
The volatility observed in the third quarter of 2026 did not occur in a vacuum. A timeline of recent developments highlights how quickly the industry has shifted from recovery to defensive positioning:
- Mid-2026: Geopolitical tensions involving the conflict in Iran begin to ripple through international shipping lanes, leading to a surge in crude oil prices and maritime insurance premiums.
- August 31, 2026: McCormick concludes its third fiscal quarter, reporting strong financial results that outperformed analyst expectations despite the headwinds.
- September 2026: Conagra Brands issues a sobering report, noting that full-year inflation is projected to reach nearly 6%, driven primarily by a severe truck driver shortage and skyrocketing transportation costs.
- October 6, 2026: Lamb Weston releases its Q1 fiscal 2027 results, with CFO James Gray citing sustained inflation across freight, edible oils, and packaging materials as major inhibitors to margin growth.
- October 7, 2026: McCormick releases its updated outlook, emphasizing that while current procurement costs are weighing on the business, the long-term outlook remains positive, anchored by the pending merger with Unilever.
Supporting Data: Operational Performance Amid Inflation
Despite the external noise, McCormick’s financial data for the third quarter reveals a company that is effectively managing its internal variables.
In a period where many of its peers saw margins compress, McCormick successfully expanded its adjusted profit margin by 180 basis points year-over-year, reaching 39.3%. This expansion is particularly noteworthy given that the company faced rising commodity and freight expenses throughout the period. Furthermore, adjusted operating income saw a significant jump of 22.1%, rising to $358.5 million.
The efficacy of the company’s CCI program has been central to these figures. By systematically identifying waste and streamlining labor and energy usage, McCormick has been able to absorb a portion of the "inflationary tax" without passing the entirety of the cost burden to the consumer. The Mexico subsidiary acquisition also serves as a strategic hedge, allowing the company to source and produce locally, thereby reducing reliance on long-haul, high-cost international logistics.
Official Responses and Strategic Perspectives
Leadership at McCormick has remained transparent about the difficulties of the current cycle. In recent earnings calls, executives have emphasized that while the macro environment is "highly dynamic," the company’s brand equity allows it a degree of pricing power that competitors in the commodity food space may lack.

"Our focus remains on the fundamentals," a company spokesperson noted. "By integrating our global supply chain and utilizing our scale, we are managing the volatility in raw materials and freight costs. The acquisition of our Mexico operations is a testament to our commitment to strengthening our regional footprint, which is crucial for insulating our operations from global transit disruptions."
Meanwhile, industry analysts point to the broader trend of "freight friction." Stricter federal oversight of the trucking industry has tightened capacity for over-the-road and long-haul shipping. This has forced companies like McCormick to adapt to longer lead times. Data from the broader logistics sector indicates that bulk lead times, which were historically managed within 24 to 72 hours, have now extended to 7 to 10 days in many regions, forcing food manufacturers to carry higher safety stocks—an additional cost that further pressures working capital.
Implications: The Unilever Merger and Future Outlook
Perhaps the most significant development on the horizon is the $44.8 billion merger with Unilever. As the companies move toward a targeted mid-2027 closing date, the focus has shifted to the projected synergies that will define the post-merger entity.
Procurement costs, currently a source of pain for the company, are expected to decline significantly in the three years following the completion of the merger. McCormick has projected that these procurement savings will account for roughly 40% of the $600 million in total recurring annual expense reductions expected from the deal.
The Path Forward
For the next eighteen months, investors and stakeholders should expect a "trench warfare" approach to supply chain management. McCormick is essentially playing a dual game:

- Immediate Tactical Defense: Using pricing and productivity to navigate the current inflation cycle.
- Long-term Structural Transformation: Preparing for the integration of Unilever assets, which promises to fundamentally lower the cost of goods sold (COGS) through improved bargaining power with suppliers and a more optimized global distribution network.
However, risks remain. Should the conflict in Iran escalate further, or should global energy prices move beyond current projections, the "pricing" lever may eventually hit a ceiling. Consumer sensitivity to food price increases has been on the rise, and there is a limit to how much of the inflationary burden can be offloaded to the end-user.
Conclusion
McCormick’s ability to grow operating income by over 22% in a hostile inflationary environment is a strong signal of institutional competence. While the company is not immune to the truck driver shortages, freight constraints, and commodity spikes that have plagued its peers like Lamb Weston and Conagra, its proactive hedging and lean manufacturing initiatives have kept it ahead of the curve.
As the industry pivots toward the massive consolidation of the McCormick-Unilever era, the company is effectively buying time. If they can continue to balance the current inflationary pressures while readying the machinery for a massive organizational merger, they are well-positioned to emerge as a dominant, highly efficient force in the global food industry by the end of 2027. The coming quarters will be a critical test of whether these efficiencies can hold against the tide of macroeconomic uncertainty.