In the modern financial landscape, the distance between customer expectation and institutional delivery has become a chasm. As digital-native competitors and agile fintechs redefine the boundaries of convenience, traditional financial institutions find themselves grappling with a fundamental disconnect: the "experience gap."
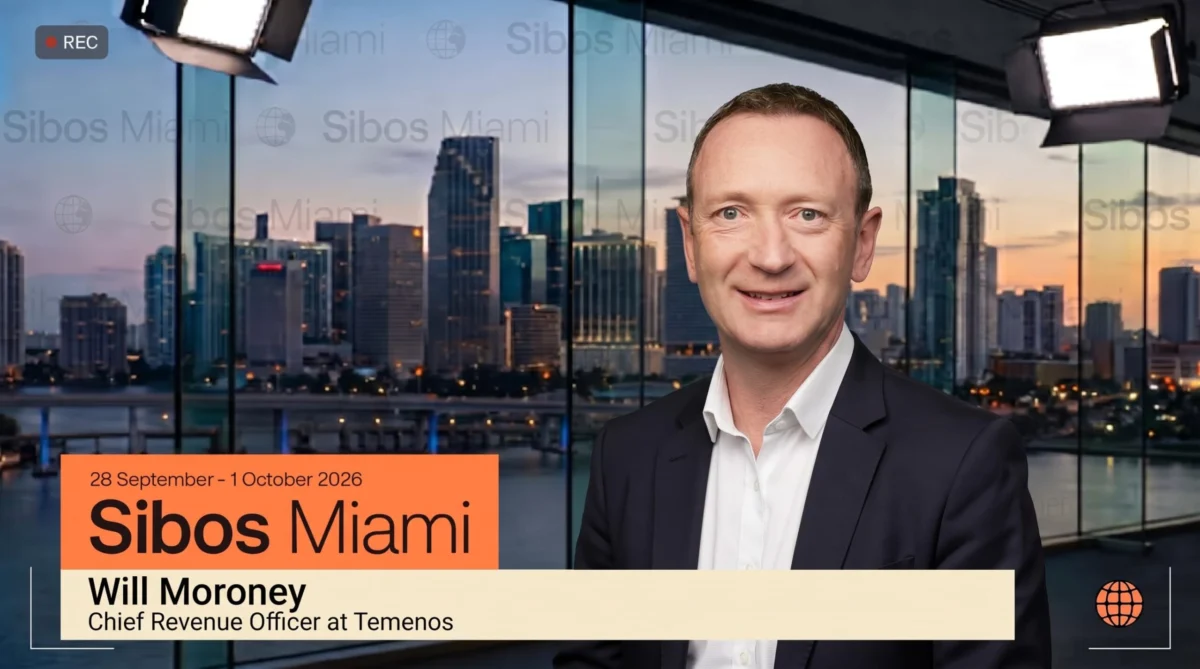
Mark Walker, Editorial Director at The Fintech Times, recently sat down with Will Moroney, Chief Revenue Officer at Temenos, to dissect the critical pressures currently reshaping the global banking sector. Their conversation, ranging from the psychological nuances of customer retention to the technical imperatives of AI-driven core modernization, paints a picture of an industry at a major crossroads.
The Main Facts: Defining the "Switchable Middle"
The central thesis of the discussion rests on a stark demographic reality: approximately three-quarters of banking customers currently inhabit what Temenos defines as the "switchable middle."
These are not the brand-loyalists of the past who stayed with their primary bank out of inertia or geographical convenience. Instead, they are customers who are increasingly indifferent to institutional loyalty, willing to move their capital at the first sign of friction or better value. According to Moroney, this group represents the greatest threat—and the greatest opportunity—for incumbent banks.
The pressure points are multifaceted, but the most acute friction occurs at the point of transaction. Payments, often viewed by banks as backend operational tasks, are the primary "moment of truth" for the consumer. When payments are slow, opaque, or prone to failure, the trust between the customer and the bank erodes instantly.
Chronology of the Modernization Shift
The urgency behind core banking transformation has evolved significantly over the past decade.
- 2010–2015: The Digital Veneer Era. Banks focused on front-end user experience (UX) to compete with early disruptors. They built sleek mobile apps that sat on top of archaic, monolithic core systems.
- 2016–2020: The Cloud Awakening. Financial institutions began realizing that a pretty app could not mask the limitations of legacy back-ends. The conversation shifted toward cloud-native architectures and API-first strategies.
- 2021–2023: The AI Catalyst. The emergence of generative AI and advanced machine learning forced a re-evaluation of data silos. Banks realized that legacy systems were inherently incompatible with the speed and data-processing requirements of modern AI tools.
- 2024–Present: The "Must-Do" Phase. As Moroney notes, the focus has shifted from "should we modernize?" to "how quickly can we modernize before we lose market share?" Even as procurement cycles lengthen due to global economic uncertainty, tier-one and tier-two banks are committing to multi-year core transformation projects with unprecedented seriousness.
Supporting Data and Industry Insights
To understand the scale of the transformation, one must look at the metrics banks use to define success. Retention numbers, while often cited in annual reports, can be dangerously misleading. Moroney warns that "retention" is not the same as "loyalty."
A customer who remains with a bank simply because the process of switching is too complex is a customer waiting to defect. True loyalty, conversely, is built through proactive engagement and seamless delivery.
Key Performance Indicators (KPIs) in Transition:
- Friction Reduction: Measuring the time-to-completion for standard payments.
- System Agility: The speed at which a bank can deploy new product features or services.
- Operational Resilience: The capacity of the core banking system to handle high-volume, real-time data processing without downtime.
- AI Integration Depth: The number of customer-facing touchpoints directly informed by AI-driven personalization.
Official Responses and Strategic Perspectives
Will Moroney emphasizes that for many large, established banks, the hurdle is not the lack of ambition, but the weight of legacy debt. Tier-one and tier-two institutions are often hampered by "spaghetti code"—decades of bespoke updates and patches that make core migration a high-stakes operation.
"The conversation has changed," Moroney explains. "Five years ago, we were talking about cost savings. Today, we are talking about survival and the ability to compete in an AI-first world."

He points out that while procurement cycles are becoming more rigorous—with banks conducting deeper due diligence on vendor stability and security—the long-term commitment to modernization is now viewed as a prerequisite for institutional health. Banks that fail to modernize their core infrastructure risk being relegated to "utility providers," while the fintechs and challenger banks capture the high-margin, customer-centric services.
Implications: The Future of Banking Architecture
The implications of this shift are profound for the entire financial ecosystem.
1. The Death of the Monolith
The future of banking lies in modular, cloud-native architecture. Banks must be able to swap out individual components—such as payment gateways, credit decisioning engines, or CRM modules—without requiring a total system overhaul. This modularity allows for the rapid deployment of AI tools that can analyze transactional data in real-time.
2. Payments as a Product
Banks that treat payments as a commodity will lose. The winners will be those who treat payments as a premium service, offering features like instant cross-border settlement, integrated liquidity management, and AI-powered spending insights directly within the payment flow.
3. The "AI-First" Imperative
Legacy systems are often incapable of feeding the high-quality, real-time data that AI requires. Modernization is therefore not just an IT project; it is an intelligence project. Without a modern core, a bank cannot leverage the predictive analytics necessary to win back the "switchable middle."
4. The Long Game of Trust
While technology is the enabler, trust remains the currency. Modernization allows for better transparency and faster dispute resolution, both of which are critical to building the kind of loyalty that prevents customers from moving to competitors.
Conclusion: Bridging the Gap
The narrative presented by Will Moroney and Temenos highlights a clear reality: the banking industry is moving away from a period of digital experimentation and into a period of structural re-engineering.
The "switchable middle" will not wait for incumbents to resolve their technical debt. They demand the responsiveness of a fintech with the security of a legacy institution. For tier-one and tier-two banks, the modernization of core systems is no longer a peripheral strategy—it is the central pillar upon which their future relevance rests. As procurement cycles tighten and the demand for AI-driven services grows, those who successfully modernize their back-ends will be the ones who transform the "switchable middle" into a base of long-term, profitable, and genuine loyalists.
The message is clear: if you are not currently building for the future, you are already being left behind by the pace of customer expectation.