In the rapidly evolving landscape of American finance, a recurring existential question haunts the C-suite of every legacy institution: Is it better to build, or to buy? When Valley National Bank announced its definitive agreement to acquire the fintech powerhouse Bluevine for $340 million, the industry received a masterclass in the complexity of this decision. The deal, slated to close in early 2027, represents more than a simple balance-sheet expansion; it is a high-stakes experiment in corporate integration. The core challenge lies in a paradox that has claimed the success of countless mergers: How can a traditional banking giant absorb a nimble, tech-first entity without suffocating the very innovation that made the acquisition attractive in the first place?
Main Facts: The Anatomy of a $340 Million Deal
The acquisition of Bluevine by Valley National Bank is a landmark transaction for both entities. By bringing Bluevine under its corporate umbrella, Valley National Bank—a institution with a robust physical footprint—is effectively supercharging its digital transformation strategy.
The deal’s value, pegged at $340 million, secures for Valley not just a product, but an ecosystem. Central to the acquisition is Bluevine’s proprietary digital banking platform, which has become a gold standard for small business (SMB) banking. Beyond the software, the transaction includes Bluevine’s formidable customer-acquisition engine and, perhaps most crucially, a specialized R&D team comprising approximately 180 professionals.
For Bluevine, the appeal is equally compelling. While the fintech has thrived as a standalone digital player, it has historically operated without the capital stability of a chartered bank. By integrating with Valley, Bluevine gains access to a substantial balance sheet and a physical branch network spanning more than 220 locations. This transition effectively moves Bluevine from a "neobank" model to a fully integrated banking division, providing its customers with the security of a traditional bank while maintaining the agility of a digital-first interface.
Chronology: The Path to Integration
The journey toward this merger did not happen in a vacuum; it is the culmination of a multi-year shift in how banks perceive the threat and opportunity posed by fintechs.
- Early 2020s: Bluevine establishes itself as a dominant force in small business lending and digital banking, carving out a niche by streamlining credit applications and offering high-yield business checking accounts.
- Mid-2026: Informal discussions between Valley and Bluevine intensify. Both parties recognize that the friction of the current macroeconomic environment requires scale to maintain profitability in the SMB sector.
- October 2026: The definitive agreement is signed and announced. The market reacts with cautious optimism, noting the premium paid for Bluevine’s intellectual property and specialized human capital.
- Late 2026 – Early 2027 (Current Phase): Regulatory review processes are underway. Both organizations are beginning the complex work of "cultural alignment," a phase that involves integrating technical stacks and aligning compliance frameworks without disrupting the daily user experience of Bluevine’s customer base.
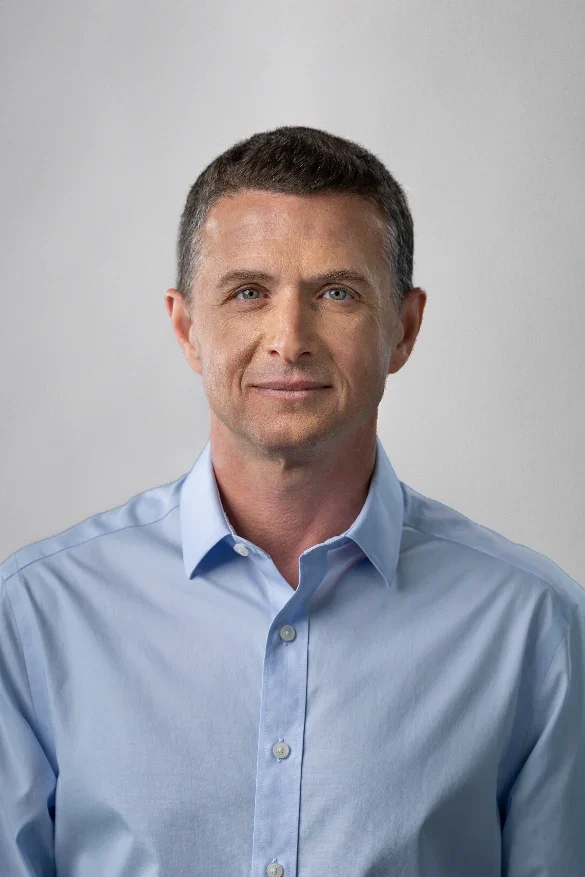
- Early 2027 (Expected): Official close of the transaction. Eyal Lifshitz, Bluevine’s CEO, is slated to step into a leadership role overseeing Small Business Banking at Valley, signaling a continuity of leadership intended to reassure both staff and stakeholders.
Supporting Data: Why "Build" Was Never an Option
To understand the price tag, one must look at the "build vs. buy" calculus. For Valley National Bank to recreate what Bluevine has spent years perfecting would have been a multi-year, capital-intensive odyssey.
Bluevine’s value proposition is built on three pillars:
- The Full-Stack Platform: Unlike many fintechs that rely on "banking-as-a-service" (BaaS) providers, Bluevine built its own core banking and lending architecture. This allows for rapid iteration and superior risk management.
- Customer Acquisition Efficiency: Bluevine has developed a data-driven, automated marketing and onboarding funnel that lowers customer acquisition costs (CAC) significantly compared to traditional bank branch-based outreach.
- Human Capital: The R&D team of 180 engineers and data scientists represents a "turnkey" innovation department. In a tight labor market for fintech talent, acquiring a pre-existing, high-functioning team is arguably more valuable than the software itself.
According to industry analysts, the "time-to-market" advantage gained by this acquisition saves Valley approximately three to five years of development. In the fast-moving SMB lending space, where competition from both Big Tech and other challenger banks is fierce, this head start is the difference between leading the market and playing catch-up.
Official Perspectives: A Conversation with Eyal Lifshitz
Tearsheet’s Managing Editor, Sara Khairi, sat down with Bluevine CEO Eyal Lifshitz to discuss the future of the entity post-acquisition. Lifshitz, who will transition into a key executive role at Valley, emphasized that the goal is not to "absorb" Bluevine into the bank’s traditional structure, but to use Bluevine as a catalyst to evolve Valley’s entire small business strategy.
"What Bluevine brings is less about any single product or capability and more about the combination it has built at scale," Lifshitz explained. "We’ve built a nationwide digital small business banking platform, a proven customer-acquisition engine, and a full-stack banking and lending platform including sophisticated core elements, risk systems, and small business expertise."
When asked about the challenge of preserving culture, Lifshitz noted that the autonomy granted to the Bluevine team is a condition of the deal’s success. He envisions a scenario where Bluevine’s technology is used to modernize the broader bank, effectively acting as an "innovation engine" for the parent institution. The objective is to keep the "fintech heartbeat" alive, ensuring that the velocity of product updates—a key differentiator for Bluevine—is not slowed by the rigorous compliance and risk-management protocols required of a traditional bank.
Implications: The Future of Banking M&A
The Valley-Bluevine deal serves as a bellwether for the future of the banking industry. We are witnessing the end of the "Bank vs. Fintech" narrative and the beginning of the "Bank + Fintech" synthesis.
The Cultural Tightrope
The most significant risk is cultural friction. Traditional banks often prioritize stability, hierarchy, and risk mitigation, whereas fintechs prioritize speed, user-centric design, and rapid testing. If Valley imposes too many layers of bureaucracy on the Bluevine team, the talent will leave. If Bluevine fails to adapt to the bank’s regulatory requirements, the merger will face legal and operational headwinds.
Technology as the New Currency
This acquisition highlights that technology is now the primary asset class for banks. In the past, a bank’s value was defined by its branch network and deposit base. Today, it is defined by the quality of its API integrations, the sophistication of its automated underwriting algorithms, and the seamlessness of its user interface. By acquiring Bluevine, Valley is effectively upgrading its "operating system" to compete with the digital-native giants.
The Rise of the "Hybrid Bank"
The success of this merger will likely encourage other regional banks to pursue similar strategies. We can expect to see a wave of acquisitions where mid-sized banks seek to buy "digital-first" capabilities to stave off encroachment from national players. However, these deals will only succeed if the acquiring banks show the restraint necessary to let the acquired fintechs operate with a degree of independence.
Conclusion: A Blueprint for the Future?
The acquisition of Bluevine by Valley National Bank is a bold bet that the strengths of a legacy institution—capital, trust, and physical presence—can be successfully married to the strengths of a modern fintech—agility, data-driven customer acquisition, and user-centric innovation.
The success of this $340 million venture will not be measured on the day the deal closes in 2027, but in the years that follow. It will depend on whether Valley can foster an environment where Bluevine’s 180-person team feels empowered to continue their work, and whether the bank can successfully scale Bluevine’s technology across its entire portfolio. If they succeed, they will provide a blueprint for how the banking industry can survive and thrive in an era of constant digital disruption. If they fail, the deal will stand as a cautionary tale about the incompatibility of banking legacy and fintech innovation.
For now, the financial world is watching closely. The "Valley-Bluevine" model is more than a merger; it is a test of whether the banking industry can truly transform, or if it will forever remain caught between the comfort of its history and the demands of its future.