In a landmark shift for the global payments landscape, American Express (Amex) has unveiled its “Intent Intelligence” framework, a technical blueprint designed to secure the burgeoning world of agentic commerce. Published on October 13, the framework represents the first comprehensive, end-to-end specification for recording, authenticating, and transmitting consumer intent before a financial transaction is ever processed.
As autonomous AI agents—software entities capable of performing tasks on behalf of users—begin to proliferate, the question of liability has become the industry’s most pressing concern. By standardizing how these agents communicate a user’s specific instructions, Amex is effectively rewriting the rules of accountability in the digital economy.
The Technical Mechanics: How Intent Intelligence Works
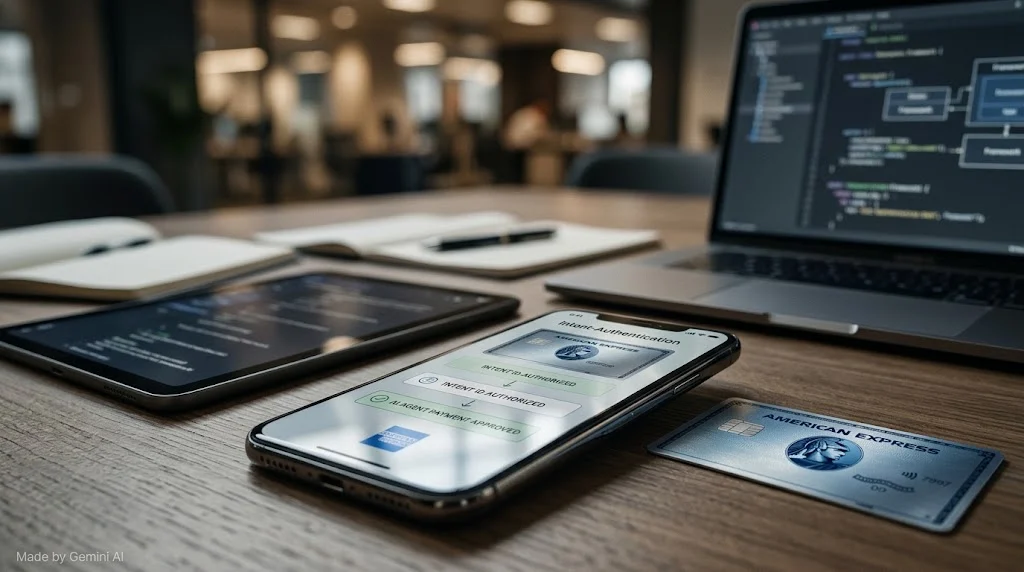
At the heart of the American Express framework is the "Create Intent API." This architecture acts as a digital ledger of desire, capturing a customer’s specific constraints—such as the target merchant, maximum budget, and product-specific preferences—before an AI agent executes a purchase.
Once the customer provides their instructions, they must authenticate and sign off on the agent’s interpretation. Upon validation, Amex issues two critical identifiers: an Intent ID and a Proof of Intent Token. The latter encodes the high-level constraints of the transaction. When the agent reaches the checkout stage, it exchanges this token for a "scoped payment credential."
Unlike a static card number, this credential is ephemeral and restricted by the parameters defined in the token. If an agent, tasked with purchasing a specific pair of white Nike trainers in size nine, attempts to pivot to a different brand or size, the system detects the deviation from the Intent ID. Amex can then block the transaction at the point of credential validation, neutralizing the risk before the merchant ever processes the charge.
A Chronology of Strategic Evolution
The launch of the Intent Intelligence framework is the culmination of a deliberate, multi-stage strategy by American Express to position itself as the infrastructure layer for AI-driven commerce.
- April 2024: Amex launches the ACE (Amex Commerce Engine) developer kit and introduces the concept of “Agent Purchase Protection.” This initial announcement set the stage, promising that eligible cardholders who utilized authenticated intent would be shielded from financial loss caused by agent errors. At the time, the service was in its nascent stages, with several key components still under development.
- September 30, 2026: The broader industry signals its intent to address the same challenge, as the public comment window for EMVCo’s draft “Intent Services” framework closes. This reflects a growing consensus that the traditional four-party payment model is ill-equipped for non-human commerce.
- October 13, 2026: Amex officially publishes its technical specifications for Intent Intelligence, moving from conceptual protection to actionable, industry-wide standards.
The Closed-Loop Advantage vs. The Four-Party Challenge
The agility with which American Express has moved stands in stark contrast to the complexities facing the rest of the industry. Because Amex operates a "closed-loop" model—functioning simultaneously as the card issuer, the payment network, and the merchant acquirer—it possesses a holistic, end-to-end view of the transaction lifecycle.

In the traditional four-party model, involving banks, networks, and third-party processors, the challenge of synchronizing intent data is significant. Every party in the chain must agree on the protocols for passing, storing, and verifying the Intent ID.
This is precisely what initiatives like EMVCo’s draft framework and the voluntary principles paper published by a consortium of six global banks, including Bank of America, seek to resolve. The industry is currently engaged in a race to standardize this "plumbing." Any institution—be it a bank or a processor—that fails to adopt a system capable of capturing, cryptographically signing, and transmitting intent data will find itself in a vulnerable position. As agentic commerce scales, the ability to produce a signed record of intent will become the primary mechanism for resolving disputes.
Official Perspectives: Shifting Risk Upstream
Hannah Bozian, Vice President of Agentic Partnerships and Strategy at American Express, has been the primary architect of this vision. Speaking to industry analysts, Bozian emphasized that the framework is essentially a move to pull the assessment of risk forward in the transaction flow.
"The goal is to shift from reactive to proactive," Bozian noted. By validating the transaction against the intent before the charge occurs, the system effectively prevents "friendly fraud" or AI-induced errors from ever entering the dispute pipeline. This transition represents a fundamental shift in the economics of payments. If a dispute arises, the burden of proof will rest on the party that holds the most accurate, authenticated, and signed record of the customer’s original instruction.
Regulatory Implications and Future Outlook
The regulatory environment remains in a state of flux. While neither the UK’s Financial Conduct Authority (FCA) nor the Payment Systems Regulator (PSR) has issued definitive guidance specifically targeting AI agents, existing frameworks offer a preview of what is to come.
Under current Authorized Push Payment (APP) fraud rules, regulators place immense weight on whether a consumer gave “genuine, informed consent.” An authenticated Intent ID provides a clear, cryptographic trail of that consent, serving as a powerful defensive artifact for both issuers and merchants.
In Europe, the implementation of PSD3 (Payment Services Directive 3) poses similar questions regarding the definition of consent. At what specific point does an AI agent’s decision-making process equate to a human’s legal mandate? The Amex framework suggests that the industry is moving toward a model where "consent" is not a single point in time, but a continuous validation of parameters.

Implications for the Ecosystem
For Merchants
For retailers, the shift toward intent-scoped credentials is a significant boon. A payment credential restricted to a specific purchase is inherently safer than a stored card number. By adopting this infrastructure, merchants can effectively outsource the risk of agent error to the network and the issuer, theoretically reducing their own dispute and chargeback rates.
For Developers and AI Partners
Developers building agentic software must now integrate these API calls into their workflows. The "friction" of authentication—often seen as a hurdle to conversion—is being rebranded as a feature of trust. Those who prioritize compliance with the Intent Intelligence framework will likely see higher adoption rates from risk-averse financial institutions.
For the Consumer
The end-user experience is poised to become safer, albeit more structured. While the convenience of AI agents is the primary selling point, the "Proof of Intent" requirement adds a layer of transparency. Users will, for the first time, have a clear, enforceable record of what their AI was supposed to do, providing a level of consumer protection that did not exist in the era of automated shopping bots.
Conclusion
The publication of the Intent Intelligence framework is a watershed moment for digital commerce. By defining the technical specifications for how AI agents communicate with financial networks, American Express has moved the conversation from abstract AI governance to practical, structural engineering.
As the industry converges on these standards, the "liability gap"—the murky space between an AI’s action and a human’s intent—is beginning to close. For the payments industry, the challenge now lies in ensuring that these standards are adopted globally, ensuring that the next generation of commerce is as secure as it is automated. The race to define the "plumbing" of the future is on, and with the publication of its framework, American Express has firmly established itself as the lead architect.