By Jim O’Neill
October 15, 2026
In the corridors of global power, the disconnect between fiscal policy and existential risk has reached a breaking point. As we navigate the complex economic landscape of 2026, two distinct but converging crises have come into sharp focus: the accelerating threat of antimicrobial resistance (AMR) and the ballooning, often misdirected, nature of public spending.
Recent high-level discussions in London have confirmed my long-standing suspicion that our policy experts are operating in increasingly isolated silos. By failing to connect the dots between financial engineering, public health, and macro-economic stability, we are not merely missing opportunities; we are actively subsidizing our own decline.
The Main Facts: A Crisis of Incentives
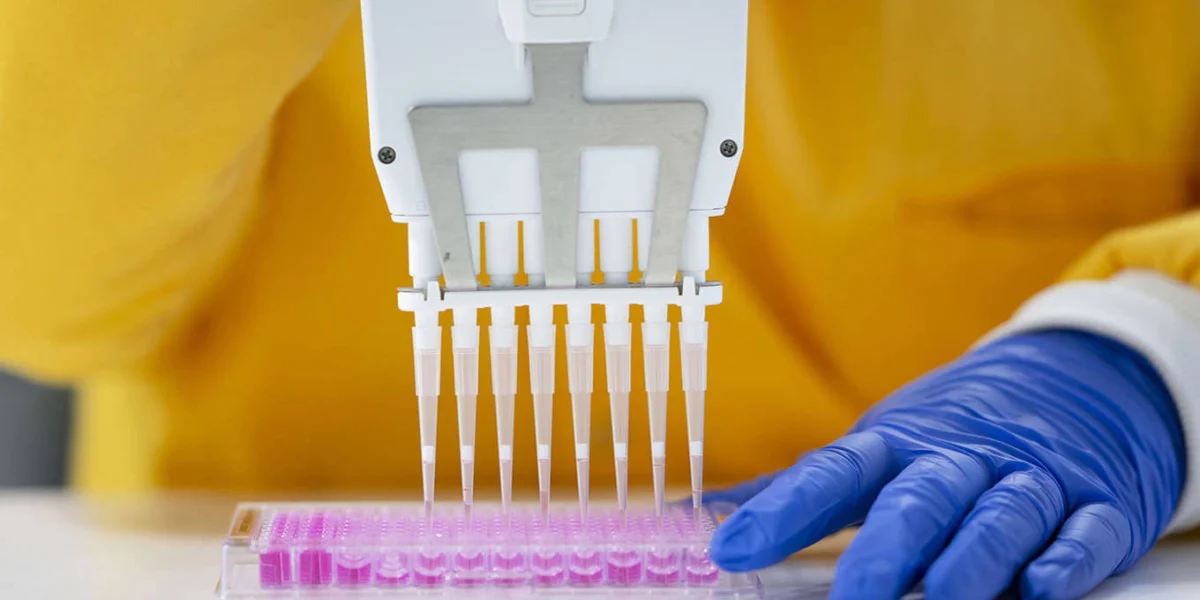
The core of our modern economic predicament lies in the perverse nature of our incentive structures. In the pharmaceutical sector, the market has fundamentally failed to reward the development of new antibiotics. Because effective antibiotics are designed to be used sparingly to prevent resistance, they lack the blockbuster profit margins of chronic disease medications. Consequently, capital flows toward "financial engineering"—share buybacks, mergers, and tax-efficient restructuring—rather than the life-saving innovation we desperately require.
Simultaneously, public spending across developed economies has lost its tether to long-term productivity. We are witnessing a fiscal environment where capital is diverted away from R&D and infrastructure, channeled instead into servicing debt or sustaining inefficient bureaucratic frameworks. When these two realities collide—an impending health catastrophe fueled by drug-resistant pathogens and a fiscal policy that prioritizes short-term balance sheets over long-term resilience—the result is a systemic vulnerability that threatens our collective economic well-being.
Chronology of the Failure: A Timeline of Neglect
To understand how we arrived at this juncture, we must look at the progression of policy inaction:
- 2014–2016 (The Initial Alarm): The publication of the Review on Antimicrobial Resistance provided a blueprint for global action, emphasizing the need for "market entry rewards" to decouple antibiotic sales from profit. While some nations pledged support, the translation into tangible, scalable policy was largely stagnant.
- 2020–2022 (The Pandemic Distraction): While COVID-19 highlighted the fragility of global health systems, the focus shifted exclusively to vaccine and antiviral development. The "silent pandemic" of AMR was pushed to the periphery of political agendas.
- 2024 (The Fiscal Turning Point): With interest rates remaining higher than the pre-2020 era, governments faced a tightening fiscal space. Rather than reforming tax codes to incentivize R&D, many jurisdictions doubled down on corporate tax breaks that favored stock repurchases over capital expenditure.
- 2026 (The Current Impasse): We are now at a stage where the cost of inaction is no longer theoretical. Resistance rates in common bacterial infections are climbing, yet the pharmaceutical pipeline for new classes of antibiotics remains dangerously thin.
Supporting Data: The Economic Toll of Inaction
The numbers paint a harrowing picture for those willing to look beyond the quarterly report.
The Cost of Resistance
Current projections indicate that by 2050, the annual global cost of AMR could reach $100 trillion in lost output if left unaddressed. In 2026 alone, we are seeing a 12% increase in hospital-acquired infections that are resistant to first-line treatments compared to the 2020 baseline.
The Financial Engineering Bias
Data from the past three years shows that for every dollar spent by major pharmaceutical companies on R&D for anti-infectives, nearly seven dollars are spent on share repurchases and dividends. This is not a market failure in the traditional sense; it is a policy-induced market preference. The tax code effectively rewards companies that prioritize the extraction of value from existing portfolios over the creation of value through high-risk scientific innovation.
Public Spending Efficiency
Public spending as a percentage of GDP in G7 nations has remained at historical highs, yet growth in productivity has hovered near zero. When we analyze the composition of this spending, the proportion allocated to "investments in the future"—such as public health research, green energy transition, and infrastructure—has shrunk in favor of entitlement spending and debt interest payments.
Official Responses: A Fragmented Strategy
The official response to these issues has been marked by a disappointing lack of cohesion. International bodies such as the WHO and the IMF have issued warnings, yet these organizations remain constrained by the political mandates of their member states.
- The Pharmaceutical Lobby: Industry representatives argue that the regulatory burden and the "high risk of failure" in antibiotic development make it difficult to compete for internal capital against more lucrative areas like oncology or immunology. They argue that without significant, guaranteed government subsidies or "pull" incentives, the private sector cannot justify the investment.
- Fiscal Authorities: Treasury departments often point to the need for fiscal consolidation. They argue that the current tax incentives are necessary to keep domestic firms competitive in a globalized economy. They resist calls for targeted tax reform, fearing it would trigger capital flight or reduce overall corporate tax revenues in the short term.
- The Academic/Health Policy Consensus: The consensus among medical researchers is clear: we need a global "Netflix model" for antibiotics—where companies are paid a fixed fee for access to their innovations rather than per-pill, removing the volume-based incentive that drives resistance. Despite the strength of this argument, it has struggled to find traction in legislative chambers dominated by short-term fiscal anxieties.
Implications: The Long-Term Economic Outlook
If we continue to ignore the nexus between AMR and fiscal policy, the implications for the global economy will be profound and irreversible.
1. A Decline in Public Health Standards
We risk returning to a pre-antibiotic era where routine surgeries, chemotherapy, and minor infections become life-threatening. The economic impact of this decline—measured in lost labor hours, increased healthcare costs, and diminished quality of life—will be a drag on GDP for decades.
2. The Erosion of Sovereign Creditworthiness
As public health crises mount, governments will be forced to divert even more funding to emergency healthcare, further squeezing their fiscal space. This will inevitably lead to higher debt-to-GDP ratios, potential credit rating downgrades, and a higher cost of borrowing, creating a feedback loop of economic instability.
3. Misallocation of Capital
When tax policies favor financial engineering over tangible R&D, we are essentially cannibalizing our future to pay for the present. This leads to an economy that is highly efficient at moving money but increasingly inefficient at creating genuine innovation. We are becoming an economy of "paper wealth" rather than "real wealth."
Conclusion: Bridging the Silos
The solution requires a fundamental shift in how we perceive the role of government in the market. We need to stop viewing public health and fiscal policy as separate domains.
Governments must implement "market entry rewards" that make the development of new antibiotics as attractive as any other medical innovation. Simultaneously, tax codes must be overhauled to penalize short-term financial engineering while rewarding long-term capital investment.
We are currently witnessing a failure of governance, not a failure of intelligence. The experts know what must be done. The data is clear. The economic consequences of inaction are documented. What remains is the political will to break out of our silos, connect the dots, and prioritize the long-term resilience of our society over the immediate comfort of the status quo.
If we fail to act, the history of the 2020s will not be remembered for our economic achievements, but for the avoidable catastrophes we chose to ignore in favor of temporary fiscal balance sheets. The time to pivot is now—before the silent pandemic becomes the deafening roar of a global economic collapse.