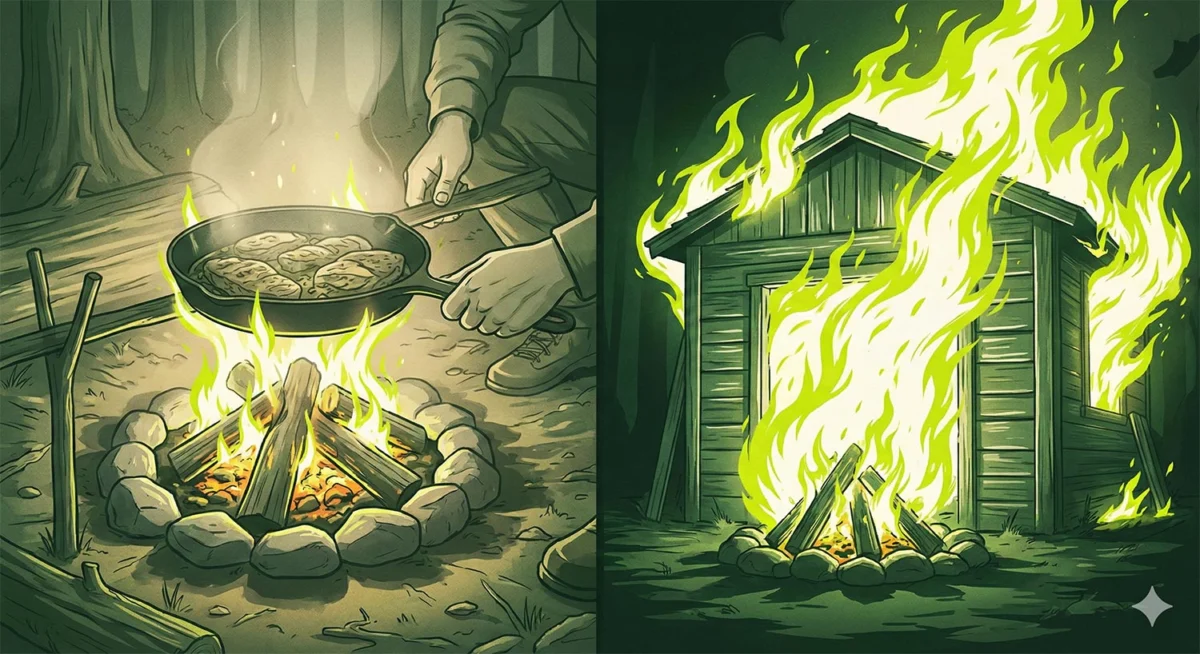
In the fast-paced world of eCommerce, capital is often viewed as the ultimate accelerant. It is the fuel for inventory orders, the budget for aggressive ad campaigns, and the bridge for seasonal cash crunches. However, for many entrepreneurs, that same fuel can become an accelerant for an uncontrollable blaze.
The reality of business debt is often hidden behind the convenience of "one-click" financing and the seductive promise of rapid scaling. Yet, as many veteran founders have discovered, the difference between a strategic leverage tool and a personal financial catastrophe is often measured by a few poorly modeled cashflow projections.
The Anatomy of a Crisis: A Case Study in Risk
The fragility of modern business operations was underscored recently by an incident involving a seasoned entrepreneur named Bill. While sitting in a parking lot, Bill received a notice from a primary supplier—a partner responsible for 80% of his company’s SKUs—stating they were terminating their relationship, effective immediately.

For any business owner, this is a nightmare scenario. But for Bill, the stakes were existential. He was personally guaranteeing seven figures of the company’s debt. If the business failed to pivot or survive the loss of its supply chain, the banks would not simply liquidate the LLC; they would come for Bill’s personal assets: his home, his brokerage accounts, and his family’s savings.
While this specific instance was later revealed to be a clerical error—a "disregard" notice—the 20 minutes of uncertainty served as a haunting reminder of how quickly debt shifts from a corporate tool to a personal threat. This chronicle of near-misses is not unique; it is a recurring theme for thousands of business owners who find themselves over-leveraged when the market shifts.
The Mechanics of Debt: Why Founders Get It Wrong
After nearly two decades in the eCommerce industry, a clear pattern has emerged: the business owners who suffer most are rarely the ones who are incompetent. They are the ones who are busy, ambitious, and reactive. They sign for loans because the liquidity is available, the interface is seamless, and the pressure to grow is constant.

The fundamental failure is almost always the same: a lack of rigorous modeling. Many founders bypass the necessary steps of understanding the true cost of capital, modeling cashflow under stress, and, most importantly, contemplating the "what-if" scenarios that could lead to default.
1. The Absence of Forward-Looking Forecasts
Before accepting any form of debt, a business must have a 13-week forward-looking cashflow forecast. This isn’t just a spreadsheet; it is a survival map.
The danger is particularly acute with Merchant Cash Advances (MCAs). These products often pull a fixed percentage of daily revenue. If a business operates on a 12% net margin and an MCA provider siphons off 10% of daily revenue, the business is effectively operating on a razor-thin 2% margin. When an entrepreneur fails to map this out, they often find themselves in a "death spiral," where the debt service consumes the very liquidity required to purchase the inventory that generates revenue.

2. The Trap of Reactive Financing
The banking industry is inherently pro-cyclical: they are eager to lend when you don’t need the money, and they vanish the moment you do.
Founders often wait until they are in a crisis—declining revenue, compressing margins, or an unexpected inventory delay—to seek credit. At this point, they are unbankable. Traditional financial institutions require 2–3 years of clean financials and consistent growth. The application process is arduous and slow. By the time a business is desperate for cash, the "proactive" window has long since closed, forcing founders toward high-interest, predatory lending options.
The Golden Rule: The best time to secure a line of credit is when the business is thriving and the balance sheet is pristine. Once established, these lines provide a safety net that can be drawn upon during periods of volatility.

3. The Hidden Cost of Personal Guarantees (PGs)
Perhaps the most dangerous element of modern business financing is the ease with which founders sign Personal Guarantees. From traditional bank term loans to the corporate credit cards used for daily advertising spend, the "corporate veil" is often much thinner than entrepreneurs believe.
If a company fails, the PG allows creditors to bypass the LLC entirely. Before signing, every founder should perform a "stress test": Would I be willing to transfer this amount of money from my personal savings account into the business today, knowing there is a possibility I will never see it again? If the answer is no, the risk profile is likely too high.
Mathematical Deception: The Truth About APR
A major pitfall in the current lending landscape is the misunderstanding of "fees" versus "interest rates." A common example is the Merchant Cash Advance that promises a "10% fee." To an untrained eye, 10% sounds manageable.

However, this fee is typically tied to the total loan amount, not an annualized rate. If a business borrows $100,000 and pays back $110,000 over the course of just 10 weeks, the true Annual Percentage Rate (APR) is significantly higher—often reaching 75% to 100%. Because the principal is repaid so quickly, the cost of capital is astronomical. Founders who treat these as standard interest-bearing loans often fail to account for the speed of repayment, leading to catastrophic cashflow erosion.
Strategic Implications: How to Protect the Business
To navigate these waters safely, business owners must adopt a mindset of financial discipline that transcends growth metrics.
The Path to Sustainable Growth
- Track ROI Religiously: Every borrowed dollar must have a specific, measurable destination. If capital is parked in a bank account without a clear plan for deployment, it will inevitably be spent on inefficiencies.
- Fix the Business Model First: If a business cannot fund its next purchase order through its own operating cash flow, there is a systemic issue—be it high Customer Acquisition Costs (CAC), thin margins, or bloated overhead. Borrowing money does not solve a broken business model; it only provides the capital to continue losing money at a faster rate.
- Avoid the "Stacking" Spiral: Using one high-interest loan to pay off another is a harbinger of insolvency. If a company reaches the point where it is "stacking" debt to stay afloat, it is time for restructuring, not more capital.
Conclusion: Debt as a Tool, Not a Crutch
Debt is a powerful lever, but like any heavy machinery, it requires an expert operator. The most successful eCommerce entrepreneurs are those who treat debt with extreme caution, prioritizing the preservation of equity and cashflow over the vanity of rapid, debt-funded expansion.

As the industry continues to evolve, the ability to read a balance sheet will become just as important as the ability to optimize a marketing campaign. For those who choose to borrow, the mandate is clear: model the cashflow, audit the personal guarantees, calculate the true APR, and never mistake a temporary cash injection for a permanent business solution.
True success in the long term is not defined by how much capital you can raise, but by how well you can build a self-sustaining engine that grows on its own merits. When the next economic storm hits, the businesses that survive will be the ones that spent their time building reserves, not the ones that spent their time managing the interest payments on their own downfall.