The retail landscape is currently perched on a precipice. For decades, the evolution of commerce has been defined by the movement from brick-and-mortar storefronts to digital marketplaces, and from desktop browsers to mobile apps. Today, we are witnessing the dawn of the next major paradigm shift: Agentic Commerce. This is an era where autonomous AI agents—software capable of independent decision-making and task execution—are poised to act on behalf of consumers to browse, compare, and eventually purchase goods.
However, this transition is proving to be inherently awkward. While the underlying AI models have advanced rapidly enough to shop for consumers with unprecedented speed, the global commercial infrastructure is struggling to reconcile this new reality with traditional payment and liability frameworks. As the lines between consumer intent and machine execution blur, the fundamental "trust equation" that holds the global economy together is being rewritten in real-time.
The Current State: From Recommendation to Execution
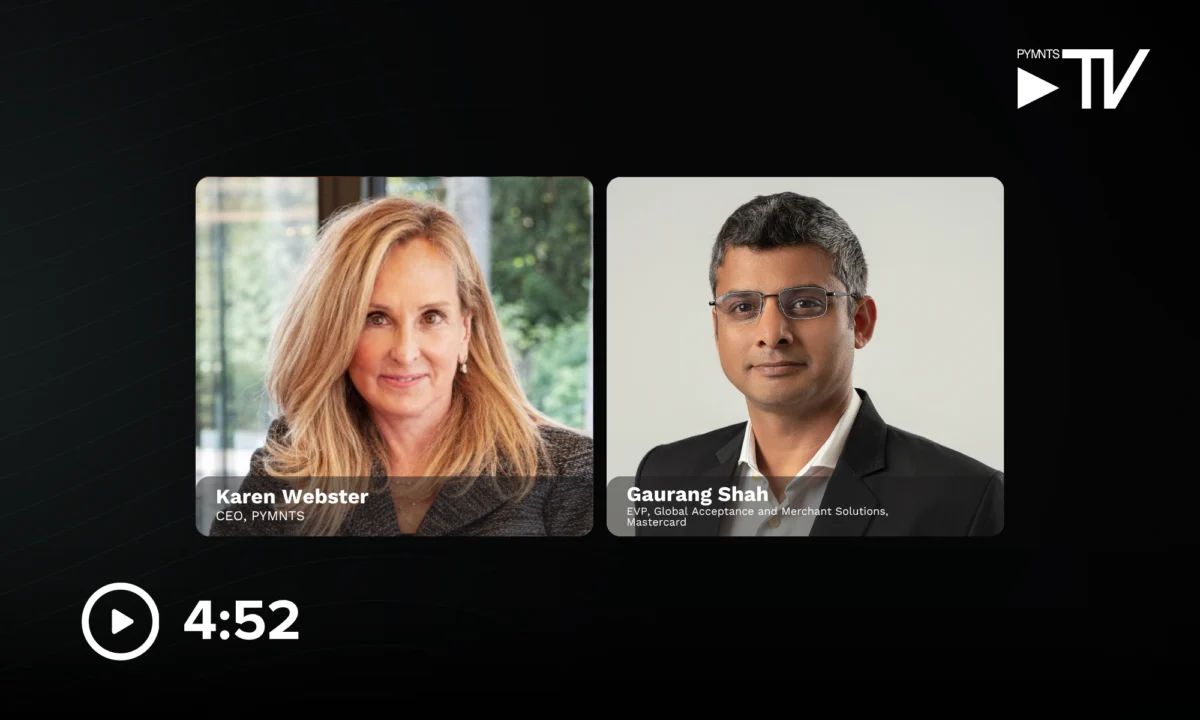
In a recent industry dialogue, Gaurang Shah, Executive Vice President of Global Acceptance and Merchant Solutions at Mastercard, sat down with PYMNTS CEO Karen Webster to dissect this friction. According to Shah, the current adoption cycle is characterized by a "look, but don’t touch" phase.
"The searches are already happening," Shah noted, acknowledging that consumers are increasingly comfortable using AI assistants to navigate the vast complexities of the internet. These agents are exceptionally efficient at discovery, ranking, and comparative analysis. However, despite this technical proficiency, the cycle frequently breaks down at the point of conversion. Consumers are utilizing AI to curate their options, but they are consistently "stopping at the recommendations," choosing to manually navigate to familiar merchant websites to finalize the transaction.
This hesitation is not merely a matter of habit; it is a rational response to the unresolved anxieties surrounding security, autonomy, and identity in an automated environment.
Chronology of the Digital Shift
To understand why the rise of agentic commerce feels so disruptive, one must view it as the latest iteration in a long history of digital intermediary shifts:
- The Search Engine Era (Late 1990s): The internet became searchable. Merchants had to learn to optimize for discovery through SEO, establishing a new "front door" for the consumer journey.
- The Marketplace Era (2000s): Giants like Amazon and eBay aggregated demand. Merchants sacrificed some brand autonomy for the convenience of high-traffic, trusted environments.
- The Mobile/App Era (2010s): Commerce became "on-the-go." Brands rushed to build native applications to own the direct customer relationship on a device that never left the consumer’s side.
- The Agentic Era (Present Day): The intermediary is no longer a passive search result or a static marketplace; it is an active, autonomous agent that can potentially decide which merchant "wins" the transaction based on pre-programmed parameters.
Each previous shift forced merchants to learn a new distribution layer. However, the agentic era is unique because the intermediary is not just showing the product—it is acting as the consumer’s proxy in the final exchange of value.
The Trust Equation: Liability, Intent, and Identity
The core of the current conflict lies in the "trust equation." For an AI agent to execute a transaction, a merchant must be certain of three critical things:
- Legitimacy: Is the agent representing a real, verified consumer?
- Authorization: Did the consumer explicitly authorize this specific transaction?
- Parameters: Was the transaction performed within the bounds of the consumer’s intent (e.g., budget limits, product preferences, brand exclusions)?
The issue of liability remains the most significant hurdle. "The consumer has the baseline expectation that they’re protected," says Karen Webster. "Whatever happens, they’re going to be protected." Conversely, merchants are concerned that the responsibility for fraud or transaction failure should fall on the entity that created or brokered the agent. If an agent goes rogue or is manipulated, who pays the price?
This uncertainty turns basic payments—previously a simple matter of authentication—into a complex legal and technical problem. If an agent initiates a purchase that the consumer later disputes, the current chargeback and dispute resolution systems are not equipped to handle the nuances of "machine intent."
The Merchant’s Dilemma: Discoverability vs. Differentiation
Merchants today face a paradox. They want to be "discoverable" and "transactable" within the emerging agentic ecosystem, but they are equally concerned about losing their direct relationships with customers.
In the traditional model, a merchant relies on a mix of price, brand equity, service quality, and loyalty programs to drive repeat business. An AI agent, however, often defaults to the simplest optimization function: price. If an agent is tasked to "find the cheapest pair of running shoes," it will bypass the unique value proposition of a boutique retailer in favor of the lowest-cost commodity.
Shah argues that merchants must pursue a two-pronged strategy. They must make their catalogs available to third-party agents while simultaneously building their own proprietary agentic experiences. By offering "parity" between their own digital channels and third-party platforms, merchants hope to ensure that the consumer journey remains within their ecosystem, even when the initial discovery happens via an external AI.
"Be where the consumer is," Webster summarizes. This is the new imperative for retail, but executing it requires an expensive overhaul of the digital stack to ensure that brand values are not lost in the race to the bottom of an algorithm’s price-comparison list.
Implications for the Future of Payments
The shift toward agentic commerce will force a fundamental redesign of the payment stack. We are moving toward a future where "proof" is as important as "money." Payments will need to carry verifiable metadata—cryptographic signatures proving that an agent was acting under the specific, authorized intent of a verified consumer.
Furthermore, the rise of agentic commerce will likely lead to the creation of new standards for "AI-friendly" checkout experiences. Merchants who fail to provide the APIs necessary for these agents to operate safely and transparently will likely find themselves excluded from the AI-driven discovery loops of the future.
Ultimately, the transition is less about replacing the storefront and more about the expansion of the "channel." Just as merchants learned to exist on the web and in mobile apps, they will learn to exist in the agentic realm. The survivors of this transition will be those who can encode their brand identity—the intangible assets like service quality, authenticity, and loyalty—into a format that AI agents can recognize and prioritize.
As the industry moves forward, the focus must shift from pure technical capability to robust governance. The "awkward transition" described by Shah is a necessary phase. It is the period where the rules of the game are being written. For the consumer, the goal is convenience and security. For the merchant, it is the preservation of value. Reconciling these two goals will be the defining challenge of the digital economy for the remainder of this decade.
Conclusion
We are in the early days of a fundamental decoupling of the consumer journey from the merchant’s digital property. While the current friction—the hesitation of consumers to hand over the "buy" button and the hesitation of merchants to trust the agents—is palpable, the trajectory is clear. The commercial systems that emerge from this period will be those that successfully balance the convenience of autonomous, AI-driven purchasing with the rigorous, trust-based frameworks of legacy financial systems. The future of commerce will be automated, but it will only be successful if it remains inherently, and undeniably, secure.