TIRANA, ALBANIA – As the new academic year commences, Albania’s National Agency for the Funding of Higher Education (AKFAL) has opened applications for its student loan program, designed to cover tuition fees and living costs. However, data reveals a concerningly low uptake of this initiative, raising questions about its effectiveness and the broader challenges facing the Albanian higher education system.
Despite being introduced in 2023, the student loan scheme has attracted a minimal number of beneficiaries. Over the past three academic years, only 23 students have successfully utilized the program, with interest in applications reportedly dwindling year after year. This stark reality contrasts sharply with the program’s intended purpose: to provide accessible financial support to students, particularly those from less privileged backgrounds, enabling them to pursue higher education without the crippling burden of immediate financial strain.
The scheme, a product of a legislative framework aiming to mirror successful models in the European Union and the United States, offers a fixed annual interest rate of 5.5%. Union Bank has been selected as the financial partner for this endeavor. Crucially, the Albanian government shoulders a significant portion of this interest, with AKFAL covering up to 5% of the rate, leaving the student with a remarkably low burden of just 0.5% interest. Applications are currently being accepted through the e-Albania portal from October 5th to November 4th.
The Genesis and Structure of the Student Loan Program
The Albanian government’s decision to implement a student loan scheme stemmed from a recognition of the financial barriers that can impede access to higher education. Modeled after international practices, the program aims to democratize university access by providing a financial lifeline to students who may otherwise be unable to afford the rising costs of tuition and daily living expenses.
Key Features of the Program:
- Purpose: To finance tuition fees and living costs for higher education students.
- Application Period: October 5th to November 4th for the current academic year.
- Platform: Applications are processed exclusively through the e-Albania portal.
- Financial Partner: Union Bank.
- Interest Rate: A fixed annual rate of 5.5%.
- Government Contribution: AKFAL covers up to 5% of the annual interest.
- Student’s Interest Burden: A nominal 0.5% annually.
- Eligibility Criteria: Applicants must provide proof of university enrollment, academic transcripts, and a confirmation from their public higher education institution stating they are not recipients of financial aid, scholarships, or tuition fee exemptions.
The program’s introduction in 2023 was met with an expectation of increased accessibility to tertiary education. However, the subsequent low participation rates have cast a shadow over its initial impact.
A Chronology of Low Engagement
The student loan scheme, while legislated in 2023, has failed to gain significant traction since its inception. The following timeline highlights the limited engagement observed:
- 2023: The student loan scheme is officially launched by the Albanian government. AKFAL begins accepting applications.
- 2023-2024 Academic Year: Data from AKFAL reveals that only a handful of students have benefited from the program. Specific figures indicate a total of 23 students across the first three academic years have successfully secured these loans.
- October 2024: AKFAL reopens applications for the new academic year, with renewed efforts to streamline the process, hoping to overcome previous low engagement.
The consistent year-on-year decline in interest for applications underscores a deeper issue that transcends mere awareness of the program.
Supporting Data: A Picture of Underutilization
The statistics provided by AKFAL paint a stark picture of the student loan scheme’s underperformance. The agency’s data indicates that over the course of three academic years, a mere 23 students have successfully applied for and received student loans. This translates to an average of just over 7 students per year.
While the exact figures for the initial academic year of the scheme’s operation are not explicitly detailed in the provided text, the overall cumulative number of 23 beneficiaries over three years is undeniably low, especially considering the large student population in Albania. This low uptake suggests that the program, as currently constituted, is not resonating with its intended audience.
The reported decline in interest from year to year further exacerbates this concern. This trend implies that the initial awareness or enthusiasm for the program may have waned, or that prospective applicants are encountering obstacles that deter them from proceeding.
Official Responses and Explanations
Officials involved with the student loan initiative have acknowledged the low number of applicants and offered explanations for this phenomenon. Laert Mezani, the Director of AKFAL, attributes the limited uptake to the novelty of student credit as a financial instrument in Albania.
"Student credit is a relatively new instrument in Albania and not a traditional mechanism for financing university studies," Mezani stated. He believes that this unfamiliarity, coupled with a degree of traditional financial conservatism among parents, contributes to the low application rates.
Mezani also expressed optimism that the simplification of application procedures for the current academic year will stimulate greater student interest. He highlighted the streamlined process through the e-Albania portal, emphasizing that applicants now only need to provide verification of their registration, academic records, and a certificate from their institution confirming they are not receiving other forms of financial assistance.
However, the narrative of "simplification" does not fully address the underlying structural and systemic issues that experts and civil society representatives believe are hindering the scheme’s success.
Implications and Expert Critiques: A Systemic Crisis?
The struggles of the Albanian student loan scheme have prompted a broader discussion among experts and civil society organizations, who point to a confluence of factors contributing to its ineffectiveness. Many view the scheme not as an isolated issue, but as a symptom of a larger crisis within Albania’s educational and economic landscape.
Bureaucratic Hurdles and Programmatic Flaws:
Artan Gjergji, an expert in financial markets and services, expressed surprise at the existence of such a government-backed financial product, even as a market follower. He identified several critical shortcomings:
- Lack of Awareness: Gjergji’s own admission suggests a significant gap in promotion and public awareness campaigns for the student loan program.
- Financial Conservatism: He cited the "conservative financial culture" of parents, who may be hesitant to incur debt for their children’s education, particularly in an uncertain economic climate.
- Bank Risk Assessment: Gjergji pointed to the stringent criteria banks employ for risk analysis, which can create additional barriers for potential borrowers.
- Government Liability: While the government subsidizes a considerable portion of the interest, he noted that the government does not assume responsibility for the repayment relationship between the bank and the student borrower.
Rigels Xhemollari, head of the organization "Citizen’s Resistance," echoed these concerns, highlighting the "bureaucracy and obstacles" within banks that impede the easy acquisition of student loans. He argues that the scheme’s design, imported from international models without adequate adaptation to the Albanian context, is a primary reason for its failure.
"The credit, first and foremost, has not worked because it only includes support for studies and not for living, which is the biggest weight of the student’s cost," Xhemollari stated. He believes that the scheme’s failure to adequately address the substantial living expenses students face is a major deterrent.
Furthermore, Xhemollari contended that the loan is not the appropriate tool for a public education system, asserting that the law was copied from England without considering the local context, rendering it non-functional.
The Importation of a Foreign Model:
The legislative framework for the student loan scheme, specifically Council of Ministers Decision No. 440/2023, reveals several bureaucratic barriers and clauses that appear ill-suited for the Albanian reality.
- Exclusion of Beneficiaries of Other Aid: Article 6 of the decision disqualifies students who receive scholarships or are exempted from annual tuition fees. This clause effectively excludes students with significant financial needs who might otherwise benefit from living cost support, even if their tuition is covered. This creates a paradox where those most in need of financial assistance for daily expenses are excluded from a program designed to alleviate financial burdens.
- Preference for Lower Loan Amounts: Article 7 dictates that when demand exceeds available funds, institutions must prioritize applications with "lower loan amounts." This penalizes students seeking full financial coverage, effectively discouraging comprehensive support.
- Post-Credit Repayment Contingency: Article 3 stipulates that the financing of subsequent credit installments is contingent upon confirmation that the student has paid their annual tuition fees. This creates a potential cash flow problem for students who rely on ongoing loan disbursements to cover both tuition and living costs.
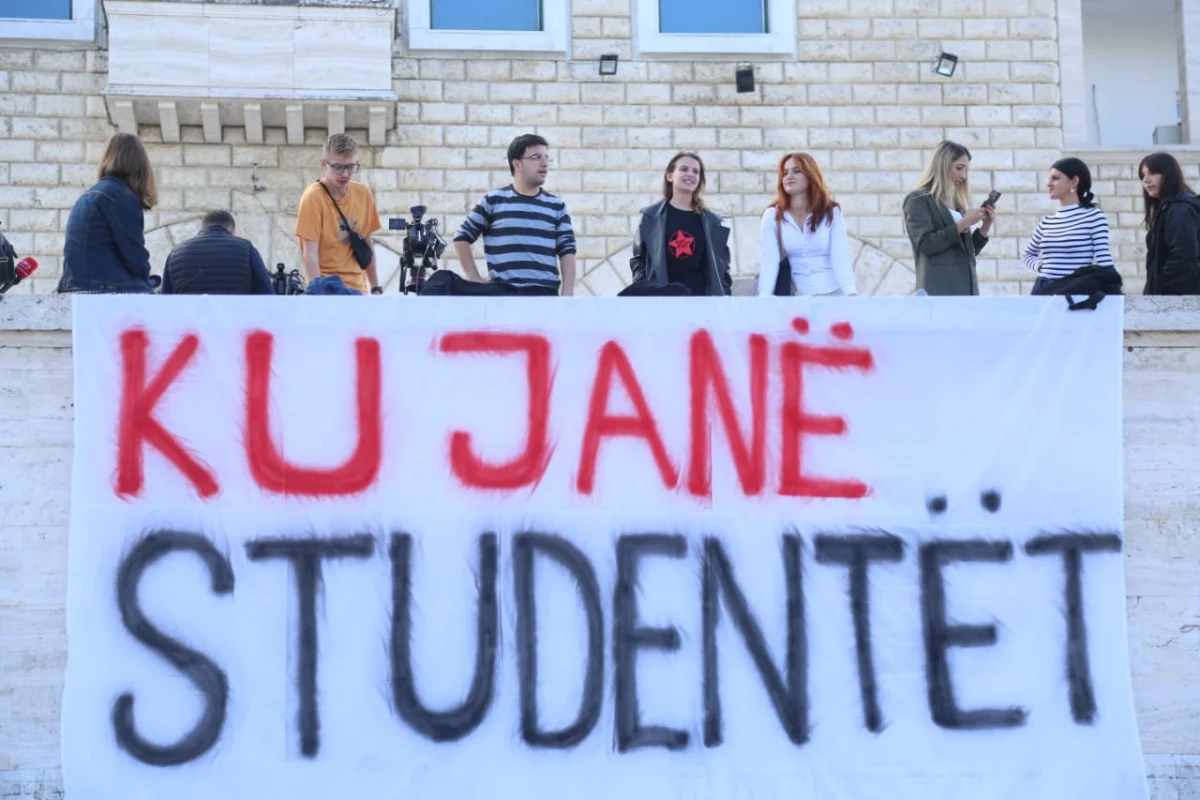
Bora Mema, an activist with the Youth Movement for Change, links the scheme’s stagnation to a broader crisis in Albania’s educational system. "The reform in higher education has been one of the biggest failures of this government," Mema stated.
She elaborated on the economic crisis, where graduates struggle to find qualified employment regardless of their field of study. This lack of job security discourages impoverished families from taking on debt for a diploma, especially since university education no longer guarantees the social mobility it once did.
In conclusion, the Albanian student loan program, while well-intentioned, faces a formidable array of challenges. The combination of low awareness, bureaucratic hurdles, programmatic flaws, and a deeply entrenched economic and educational crisis suggests that a significant re-evaluation and recalibration of the scheme, alongside broader systemic reforms, will be necessary for it to fulfill its promise of accessible and equitable higher education for Albanian youth.