The global race for artificial intelligence supremacy is no longer confined to the traditional tech hubs of Silicon Valley or the established data corridors of Singapore and Tokyo. As the computational demands of large language models (LLMs) and generative AI reach unprecedented levels, the world’s digital backbone is shifting. Vietnam, a nation defined by its rapid industrialization and youthful, tech-savvy population, has emerged as a prime candidate to anchor the next generation of global data infrastructure.
With a flurry of multi-billion-dollar investments and a strategic pivot in its regulatory landscape, Vietnam is positioning itself to evolve from a manufacturing export hub into a critical node in the regional digital economy. However, the path forward is complex, requiring the country to balance its ambitious growth targets against the harsh physical realities of energy stability and infrastructure connectivity.
The Strategic Shift: Beyond Traditional Hosting
For years, Vietnam’s data center footprint was modest, designed primarily to serve domestic enterprise needs—local banks, retail chains, and government portals. That era has ended. The current wave of infrastructure projects is characterized by a fundamental change in mission: these facilities are being built for the "AI era."
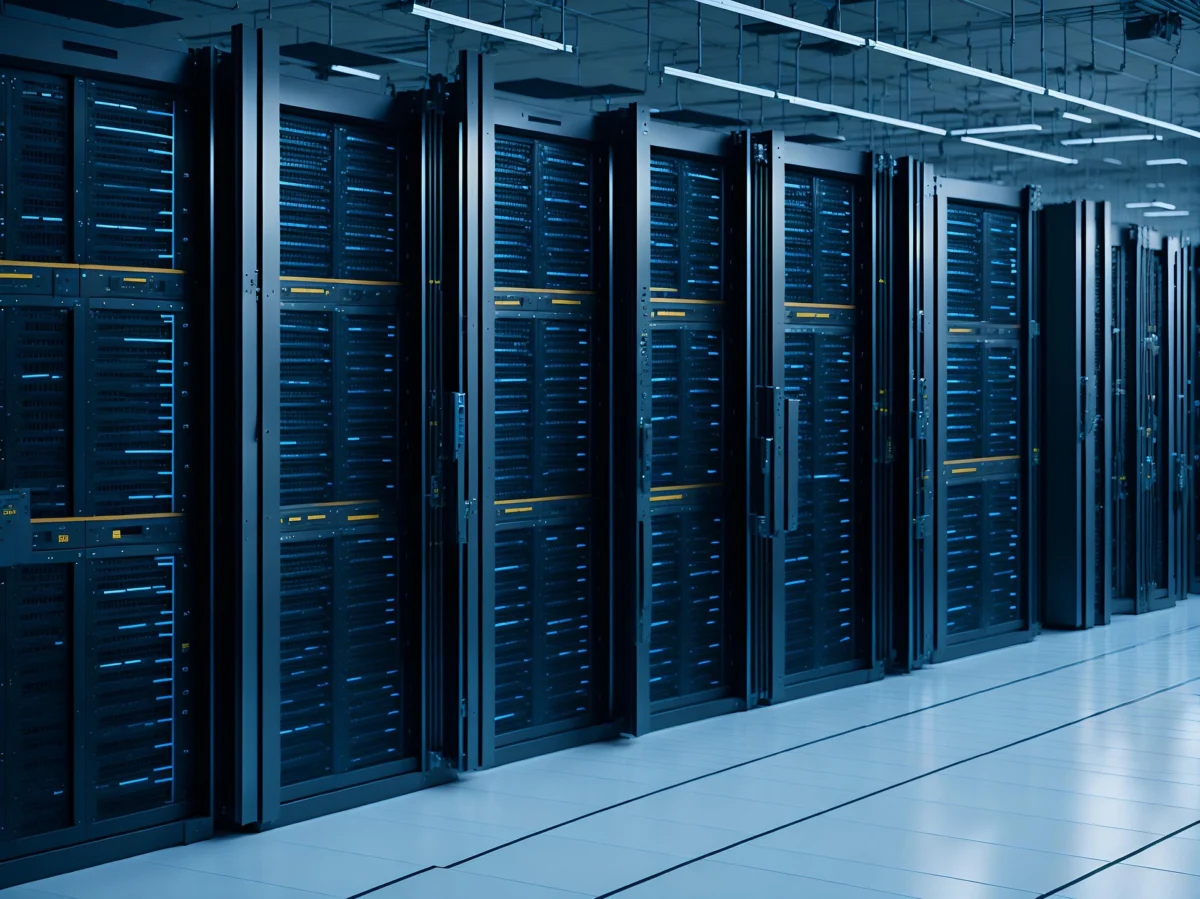
Unlike traditional server farms, modern data centers in the Ho Chi Minh City metropolitan area are designed for high-density, liquid-cooled, and GPU-intensive workloads. These sites act as the "brains" of the modern economy, facilitating the massive data throughput required for cloud computing and the iterative training of machine learning algorithms. Currently, the region hosts approximately 20 operational facilities, but the project pipeline suggests this number will swell significantly as developers race to secure prime land in key industrial parks.
Chronology of the Digital Surge
The transformation of Vietnam’s digital infrastructure is a relatively recent phenomenon, accelerated by legislative reforms and global market trends.
- 2023–2024 (The Regulatory Catalyst): Recognizing that foreign capital is essential to scale, the Vietnamese government moved to modernize its investment laws. The decision to permit 100% foreign ownership of data center services—fully effective by 2025—marked a watershed moment, dismantling the barriers that previously limited international investment.
- July 2025 (The SGI-HCM Milestone): The SGI-HCM Campus at Tan Phu Trung Industrial Park received its official investment registration certificate. This project, spearheaded by Kinh Bac City in collaboration with Accelerated Infrastructure Capital and VietinBank, signaled that massive, multi-billion-dollar projects were no longer theoretical concepts but actionable realities.
- Late 2026 (The Next Phase): The industry is bracing for the end of August 2026, which marks the scheduled shift for the SGI-HCM project to enter its intensive development phase. This will serve as a bellwether for the country’s ability to execute large-scale, high-tech infrastructure on time.
- 2031 (The Economic Horizon): Market analysts at Savills and other financial institutions have identified this year as a critical benchmark, by which point industry revenues are projected to exceed $3 billion, with a compounded annual growth rate (CAGR) consistently tracking above 20%.
Supporting Data: The Mathematical Case for Vietnam
The bullish outlook on Vietnam is backed by robust data. According to estimates from Savills Vietnam, the country’s total data center capacity is projected to nearly double within the next five years.
- Capacity Expansion: From an estimated 525 MW in 2025, the total capacity is expected to approach 950 MW by 2030. This near-doubling reflects the aggressive timelines of hyperscalers and co-location providers entering the market.
- Market Dynamics: A population of over 100 million, characterized by high mobile penetration and a digital-first younger generation, provides a fertile domestic market. When combined with the "China-plus-one" strategy of international tech firms, the demand for local compute capacity becomes exponential.
- Investment Tiers: The market is currently stratified into three tiers of investment:
- Mega-Projects ($2B+): Projects like the proposed consortium involving G42, Microsoft, FPT, and VinaCapital.
- Strategic Partnerships ($500M–$1B): Collaborations such as BW Industrial Development with Warburg Pincus and Digital Realty.
- Specialized Local Infrastructure ($100M–$500M): Regional players like NTT Global Data Centers and CMC, who are leveraging local expertise to navigate regulatory nuances.
The Regulatory Landscape: Opening the Gates
The primary driver of this recent momentum is the liberalization of the regulatory environment. By allowing full foreign ownership, Vietnam has successfully bridged the trust gap for international operators. This policy shift is not merely about attracting capital; it is about bringing international standards of management, security, and energy efficiency to the Vietnamese market.
Furthermore, evolving data localization laws—which encourage or require sensitive personal and financial data to be stored within national borders—are acting as a "forced multiplier" for demand. As the state tightens data protection frameworks, local and multinational firms operating in Vietnam are finding it increasingly necessary to move their operations from overseas cloud instances to domestic, high-security data centers.
Implications: The Energy and Infrastructure Bottlenecks
Despite the enthusiasm, the transition to a regional data hub is not without significant friction. The most pressing challenge is the "energy paradox": data centers are energy-intensive, yet they require power that is both consistent and increasingly green.
The Power Challenge
Data centers require a "five-nines" (99.999%) reliability rating for electricity. In a developing economy, balancing the grid to accommodate these massive, concentrated loads is a monumental engineering task. If Vietnam cannot guarantee a stable power supply, the risk of "brownouts" or power instability could deter the very hyperscalers (like AWS, Google, or Microsoft) that the country is trying to attract.
Moreover, as international investors face pressure to meet ESG (Environmental, Social, and Governance) targets, they are increasingly demanding that their electricity be sourced from renewable origins. Vietnam’s ability to scale its solar, wind, and potentially offshore energy capacity will directly dictate its attractiveness as a long-term data center destination.
Connectivity and the Submarine Cable Issue
While physical infrastructure is being built, the "pipes" that connect Vietnam to the global internet—specifically its submarine fiber-optic cables—are under immense pressure. Frequent outages or limited bandwidth capacity can bottleneck the utility of a world-class data center. Future-proofing the country’s digital economy will require a massive investment in redundant international submarine cables to ensure that the data stored in Ho Chi Minh City can be accessed seamlessly from New York, London, or Tokyo.
A New Real Estate Asset Class
The rise of the data center is fundamentally altering the Vietnamese real estate sector. Unlike commercial office space or traditional manufacturing warehouses, data centers represent a unique asset class. These are "mission-critical" facilities that demand:
- Geological Stability: Sites must be protected from flooding and seismic risks.
- Long-Term Horizon: These are not three-to-five-year lease properties; these are twenty-to-thirty-year infrastructure investments that require complex zoning and long-term land-use rights.
- Sophisticated Security: Beyond physical walls, these sites require cutting-edge digital firewalls and biometric access, often involving collaboration with government security agencies to ensure compliance with national data privacy standards.
Conclusion: A High-Stakes Balancing Act
Vietnam stands at a critical juncture. The country has the demographic tailwinds, the legislative support, and the international investor interest to become a dominant force in Southeast Asian digital infrastructure. The influx of billions of dollars into facilities like the SGI-HCM Campus is a testament to the global belief in Vietnam’s potential.
However, the transition from an emerging market to a regional digital leader is contingent upon the government’s ability to solve the "triple-threat" of infrastructure: energy reliability, power sustainability, and global connectivity. If these structural challenges are addressed with the same urgency as the regulatory reforms of 2025, Vietnam will not only secure its place in the AI revolution but will likely define the trajectory of the Southeast Asian digital economy for the next several decades.
As the world continues to digitize, Vietnam is no longer just a consumer of global data; it is positioning itself to become the vault where that data is kept and the engine room where the AI of tomorrow is built. The opportunity is historic, but the execution remains a test of the nation’s industrial and administrative resolve.