In a striking reversal of the restrictive energy policies that have defined the last several years of trans-Atlantic relations, a tanker laden with 40,000 metric tons of Russian diesel is currently navigating toward New York. The Agioi Fanendes, a Malta-flagged vessel, represents the first concrete manifestation of a new supply agreement between Washington and Moscow, effectively reopening a trade corridor that had been shuttered by the U.S. ban on Russian petroleum imports in 2022.
The voyage is more than a logistical maneuver; it is a signal of a profound pivot in American energy strategy. Orchestrated under the authority of a new executive order issued by President Donald Trump on October 9, 2026, this shipment marks a departure from the isolationist energy stance that previously characterized the U.S. approach to the ongoing conflict in Ukraine.
The Voyage of the Agioi Fanendes
The Agioi Fanendes took on its cargo of ultra-low-sulfur diesel at the Russian Baltic Sea oil port of Primorsk on October 22. According to LSEG ship-tracking data, the vessel is scheduled to reach its destination in the United States on November 7.
While the specific identities of the buyer and seller remain shielded from public disclosure, the shipment serves as the vanguard for what Moscow expects to be a series of recurring deliveries. Kremlin spokesman Dmitry Peskov confirmed to Reuters on Friday that the vessel had departed and noted that the Russian government anticipates regular, stable supplies to follow. Russian Deputy Prime Minister Alexander Novak further corroborated this, stating that additional shipments are currently in the pipeline as U.S. and Russian commercial entities finalize long-term delivery contracts.
This development follows a period of total abstinence from Russian diesel imports. While some analysts point to the July 2023 timeframe for the last recorded, albeit obscure, cargo arrival, the current shipment is widely regarded as the first major, policy-sanctioned import since the blanket ban of 2022.
Legal Framework: The Return of General License 135
The legality of this trade rests on the Treasury Department’s Office of Foreign Assets Control (OFAC) issuance of General License 135 on October 9, 2026. This administrative mechanism provides a surgical exception to existing punitive measures, specifically targeting the Russian Harmful Foreign Activities Sanctions Regulations (31 CFR Part 587) and the Ukraine-/Russia-Related Sanctions Regulations (31 CFR Part 589).
By providing this limited relief, the U.S. administration has effectively created a "carve-out" for diesel. The executive order, which implements the Lindsey O. Graham Sanctioning Russia and Iran Act of 2026, outlines a phased return of Russian petroleum to the U.S. market. The schedule is aggressive: an initial release of 300,000 metric tons was authorized, followed by an additional 500,000 tons in November, with a massive one-million-ton release slated for the period immediately following.
Domestic Pressure and the Election Cycle
The timing of this energy pivot is intrinsically linked to the U.S. midterm elections scheduled for November 3. With voters expressing acute frustration over the cost of living and energy prices at the pump, the White House has moved to utilize every available lever to stabilize the market.
Analysts are nearly unanimous in their assessment that the policy is a tactical response to domestic political pressures rather than a strategic shift in international alliance-building. "The diesel deal shows that Washington’s Russia policy is now driven by high prices at the pump before the November 3 midterm elections, rather than by any shared trans-Atlantic strategy," remarked Matthias Matthijs, a senior fellow for Europe at the Council on Foreign Relations.
Mohit Kumar, chief European economist at Jefferies, echoed this sentiment in an October 12 research note, suggesting that the Trump administration is "exploring all avenues to bring down diesel prices before the mid-terms." Despite the urgency, the logistical reality is that the Agioi Fanendes will not arrive until after the ballots have been cast, creating a potential political paradox if the impact on retail fuel prices remains negligible.
Economic Impact and Market Realities
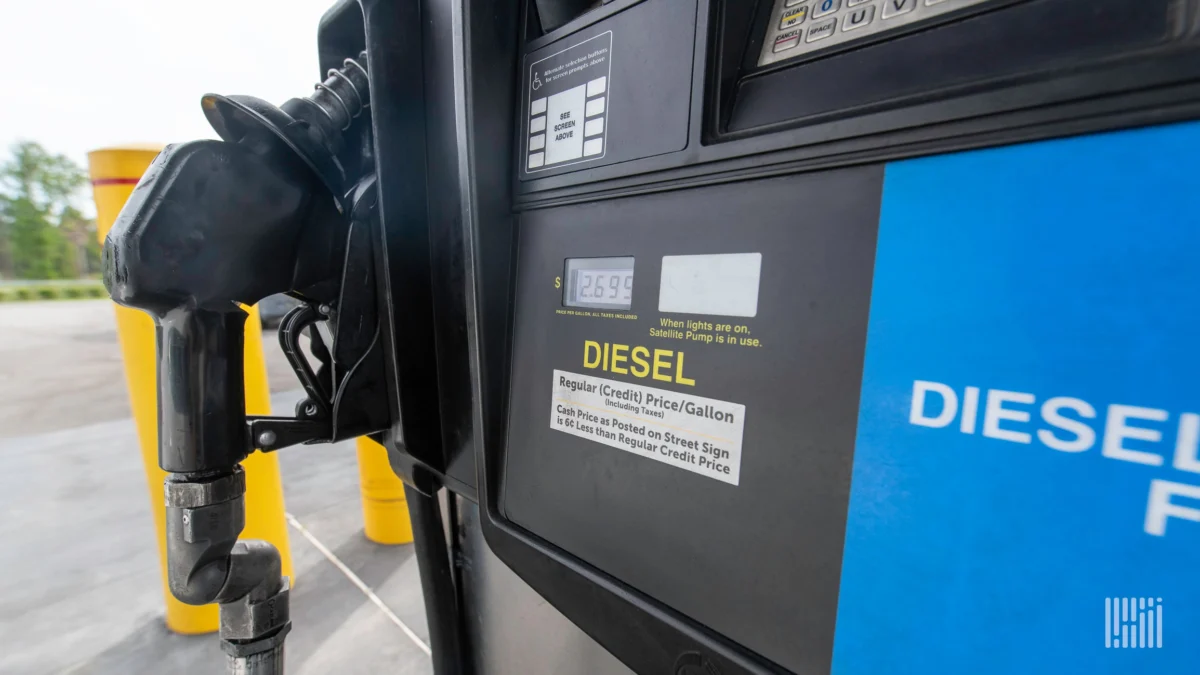
To understand the scale of this intervention, one must look at the data. The United States consumes approximately 4 million barrels of diesel per day. The current cargo of 300,000 barrels accounts for roughly 7% of that daily consumption.
Energy policy experts have been quick to temper expectations regarding the impact of these imports on the average consumer. Because the volume represents a relatively small fraction of total U.S. daily usage, many analysts argue that the influx will not be sufficient to trigger a substantial or long-term reduction in fuel prices. Instead, the move is being viewed by market participants as a signal—a psychological intervention intended to reassure markets of supply availability, rather than a fundamental correction of supply-side constraints.
Geopolitical Fallout and International Criticism
The decision has not been met with universal approval. In Kyiv, the reaction has been one of profound disappointment. Ukrainian leadership has consistently urged Western allies to maintain and tighten the economic noose around Moscow, arguing that any revenue generated by Russian energy exports directly funds the ongoing military campaign in Ukraine.
President Volodymyr Zelenskyy characterized the U.S. decision as "a weak decision by strong partners," underscoring the friction this deal has introduced into the U.S.-Ukraine relationship. The move suggests a widening chasm between the U.S. government’s domestic economic priorities and the security requirements of its allies in Eastern Europe.
Furthermore, by making Russian diesel easier to trade and transport, the U.S. has arguably enhanced Moscow’s ability to generate export earnings, potentially complicating the enforcement of other ongoing sanctions programs. The precedent set by this arrangement could lead other nations to seek similar exemptions, potentially weakening the international coalition that has sought to isolate the Russian energy sector for the past four years.
Future Implications: A New Era of Energy Pragmatism?
As the Agioi Fanendes continues its transit, the energy sector is watching closely to see if this is an isolated incident or the beginning of a broader reintegration of Russian energy into the Western sphere.
The structural changes required to facilitate this trade—re-establishing shipping routes, insurance, and banking channels—are not insignificant. Once these "pipes" are reopened, they are difficult to close again. The administration’s gamble is that the political benefit of lower fuel prices will outweigh the diplomatic fallout and the criticism regarding the efficacy of the sanctions regime.
For the trucking, shipping, and logistics industries, this development adds a new layer of complexity to an already volatile market. With the potential for regular, high-volume shipments of Russian diesel, fuel supply chains may see a stabilization in availability, though the long-term price trajectory remains tied to global crude benchmarks and the unpredictable nature of the Russia-Ukraine conflict.
Ultimately, the reopening of this trade route signifies a return to a brand of energy pragmatism that many observers thought was a relic of the past. As the United States navigates the delicate balance between domestic economic survival and the defense of its international commitments, the arrival of this single tanker stands as a powerful, if controversial, symbol of the shifting winds in global policy.
This report is part of a continuing series on the evolving landscape of global energy trade and its implications for the logistics and transportation sectors. For further analysis on international trade regulations and supply chain impacts, readers are encouraged to follow our ongoing coverage of energy policy and market trends.