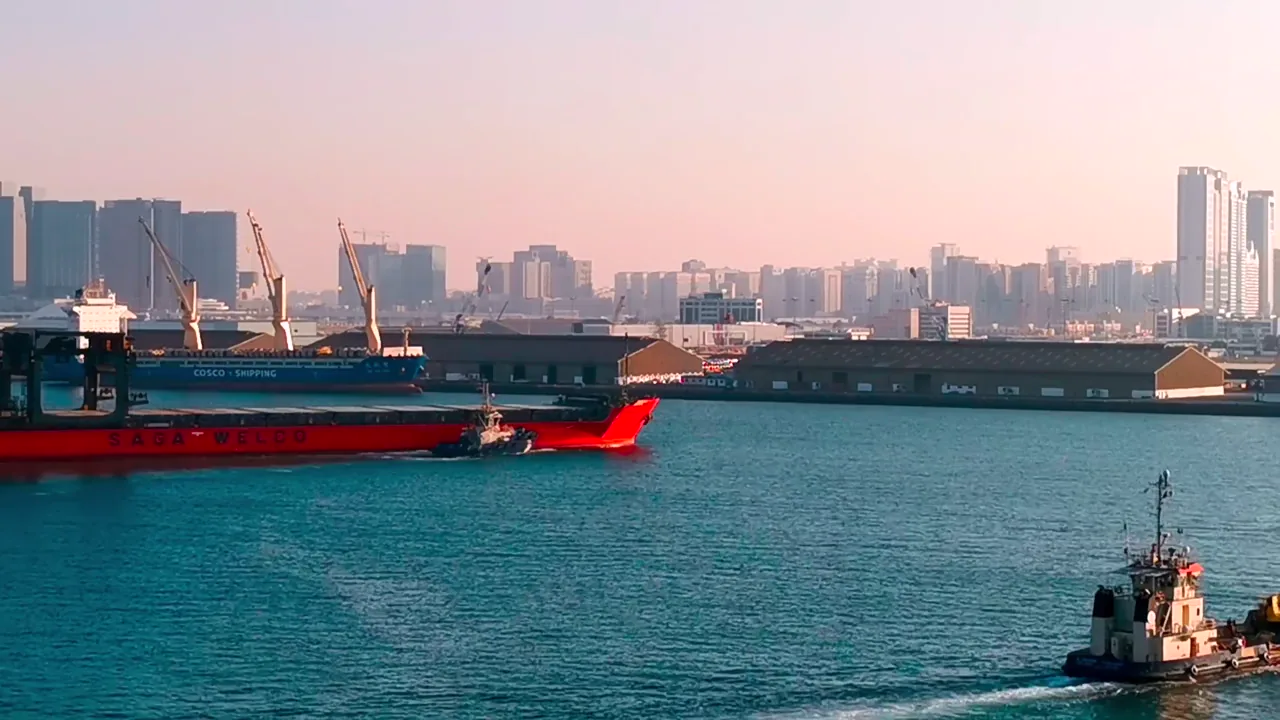
As the global maritime industry faces mounting pressure to align with International Maritime Organization (IMO) targets for net-zero emissions, China has emerged as a critical—if complex—linchpin in the transition. A comprehensive new report from the Global Maritime Forum, unveiled during the organization’s annual gathering in Shanghai, confirms that China is now the epicenter of the global push for "green shipping corridors." With 21 active projects connected to the nation, China currently accounts for nearly 20% of the world’s total green shipping initiatives, signaling a structural shift in how the world’s largest trading nation views the future of its maritime footprint.
However, beneath the headline-grabbing statistics lies a nuanced reality. While China’s industrial scale is unprecedented, the transition remains in its infancy, marked by a stark disparity between ambitious policy frameworks and the harsh economic realities of current fuel prices.
The Strategic Landscape: Mapping China’s Green Corridors
The Global Maritime Forum’s analysis identifies a significant acceleration in project announcements, with China introducing ten new ventures in 2025 alone. These corridors, designed as designated trade routes where low- and zero-emission shipping solutions are supported and incentivized, represent the industry’s best hope for scaling up green infrastructure.
The Maturity Gap
Despite the surge in activity, the data reveals a "maturity gap." As of the end of June 2025, the breakdown of these 21 projects illustrates a sector still finding its footing:
- Initiation Phase: 12 projects are in the early conceptual stage.
- Feasibility Assessment: 5 projects are currently undergoing rigorous viability studies.
- Preparation: 3 projects have reached the technical planning stage.
- Realization: Only 1 project—the Australia-East Asia Iron Ore corridor—has reached the operational stage.
The success of the Australia-East Asia corridor, which utilizes ammonia-fueled bulk carriers to bridge the Pilbara region with Chinese ports, serves as the industry’s current "gold standard." It proves that the technical hurdles of using alternative fuels can be overcome, provided there is enough political and commercial alignment between trading partners.
Future Fuel Production: A Chinese Monopoly in the Making?
Perhaps the most significant finding of the report is the concentration of green fuel production capacity within Chinese borders. To achieve a decarbonized shipping industry, the world requires massive volumes of green methanol and green ammonia. China is currently positioning itself as the primary global supplier for both.
Capacity and Projections
China currently holds approximately 80% of the world’s green methanol production capacity that has cleared final investment decisions (FID). Similarly, the nation controls over 40% of the global green ammonia capacity. If current pipeline projects proceed as planned, China aims for a staggering output of 30 million tonnes of green methanol and 15 million tonnes of green ammonia annually by the early 2030s.
While these figures are impressive, analysts remain cautious. "Not every announced project will secure the necessary capital," the report warns. The volatile nature of renewable energy markets and the high capital expenditure required for green hydrogen electrolysis mean that a significant portion of these "pipe dreams" may never reach fruition without sustained state support or long-term offtake agreements.
The Rise of Bunkering Hubs
Infrastructure is also evolving at the port level. Over ten Chinese ports are either actively operating or constructing methanol bunkering facilities. Projections suggest that volumes will reach 100,000 tonnes by mid-2026, a significant jump from the 64,000 tonnes recorded throughout 2025. Shanghai, cementing its status as the premier global maritime hub, accounts for roughly 90% of this total, effectively acting as the gateway for China’s green fuel transition.
Chronology: Key Milestones in the Green Transition
To understand how quickly this landscape is shifting, one must look at the recent timeline of events:
- 2024: Initial discussions on green shipping corridors gain momentum as international pressure on the shipping sector intensifies due to new EU and IMO environmental compliance mandates.
- September 2025: The "International Green Shipping Corridor Alliance" is launched. This initiative brings together 45 companies and organizations from 12 nations, creating a multilateral framework to harmonize fuel standards and infrastructure development.
- Early 2026: The Mineral Europa, a 210,000 dwt newcastlemax vessel owned by CMB.TECH and chartered to Australian mining giant Fortescue, completes a landmark commercial voyage.
- Mid-2026: The Mineral Europa successfully conducts the world’s first commercial ship-to-ship bunkering of green ammonia at the port of Zhoushan, marking a pivotal technical milestone for the industry.
Economic Hurdles: The "Premium" Problem
Despite the technical triumphs, the fundamental economics of green shipping remain a daunting barrier to widespread adoption. The report highlights a persistent "green premium" that threatens to stall progress.
Cost Disparity
Green methanol and ammonia remain priced at two to three times the cost of conventional heavy fuel oil (HFO), even with China’s competitive advantage in production. Furthermore, battery-electric cargo vessels currently cost roughly double that of traditional diesel-powered equivalents.
The Demand Mismatch
There is a profound disconnect between corporate sustainability commitments and the willingness to pay for them. While 65% of cargo owners surveyed expressed a willingness to pay a premium for low-carbon shipping, the median premium they are actually willing to accept is a mere 3%. This 3% ceiling is woefully insufficient to cover the current cost gaps for green fuels, creating a "deadlock" where shipping companies are hesitant to invest in fleets that cargo owners are unwilling to subsidize.
Implications: The Path Forward
The report concludes with a series of urgent recommendations, emphasizing that technical capability is no longer the primary bottleneck—economic policy is.
Policy and Harmonization
The Global Maritime Forum stresses the need for three critical interventions:
- Investment in Networks: A shift in focus from ship-only solutions to comprehensive bunkering and distribution infrastructure is required. Without a reliable supply chain at major ports, vessels cannot operate on alternative fuels.
- Certification Standardization: There is a pressing need to harmonize Chinese fuel certification rules with international standards. A fragmented regulatory landscape creates uncertainty for investors and increases transaction costs.
- Policy-Driven Price Correction: To bridge the gap between the 3% premium cargo owners are willing to pay and the actual cost of green fuels, governments must intervene. Carbon pricing mechanisms, tax incentives for green shipping, and direct subsidies for bunkering infrastructure are essential to leveling the playing field.
Official Responses and Industry Outlook
Industry leaders gathered in Shanghai noted that while China is leading by volume, the global transition is a collective effort. The formation of the International Green Shipping Corridor Alliance in September represents a strategic pivot toward collaboration rather than competition.
By uniting 45 international entities, the Alliance aims to mitigate the risks associated with the high capital costs of green infrastructure. Industry experts suggest that the "first-mover" advantage in China could set the standard for the rest of the world, provided the country can successfully transition from its current pilot-project model to a fully commercialized, profitable ecosystem.
Conclusion: A Testing Ground for the Future
The story of green shipping in China is a microcosm of the global climate challenge. It features massive industrial ambition, significant technological breakthroughs, and the stubborn persistence of economic reality. While the successful bunkering of the Mineral Europa in Zhoushan proves that the future is technically possible, the road to 2030 and beyond will be defined by whether policy can catch up to ambition. If China can reconcile its vast production capacity with the need for international regulatory harmony, it will undoubtedly lead the maritime industry into a new, cleaner era. If it cannot, the "green corridor" movement risks remaining a collection of well-intentioned, but ultimately isolated, pilot projects.