In a significant reprieve for Australia’s small business sector, the federal government has intervened to halt a contentious plan by the Australian Taxation Office (ATO) to cease accepting credit card payments. The decision, announced by Treasurer Jim Chalmers, provides a crucial extension until July 2027, effectively shielding small enterprises from a policy change that industry leaders warned could have severely crippled cash flow management.
While the intervention has been widely welcomed by business lobby groups, the consensus remains that this delay should serve only as a starting point. Critics argue that the underlying structural issues—namely the ATO’s refusal to absorb processing costs and the unique financial pressures faced by SMEs—require a more permanent, strategic resolution rather than a temporary financial band-aid.
The Chronology of a Policy Crisis
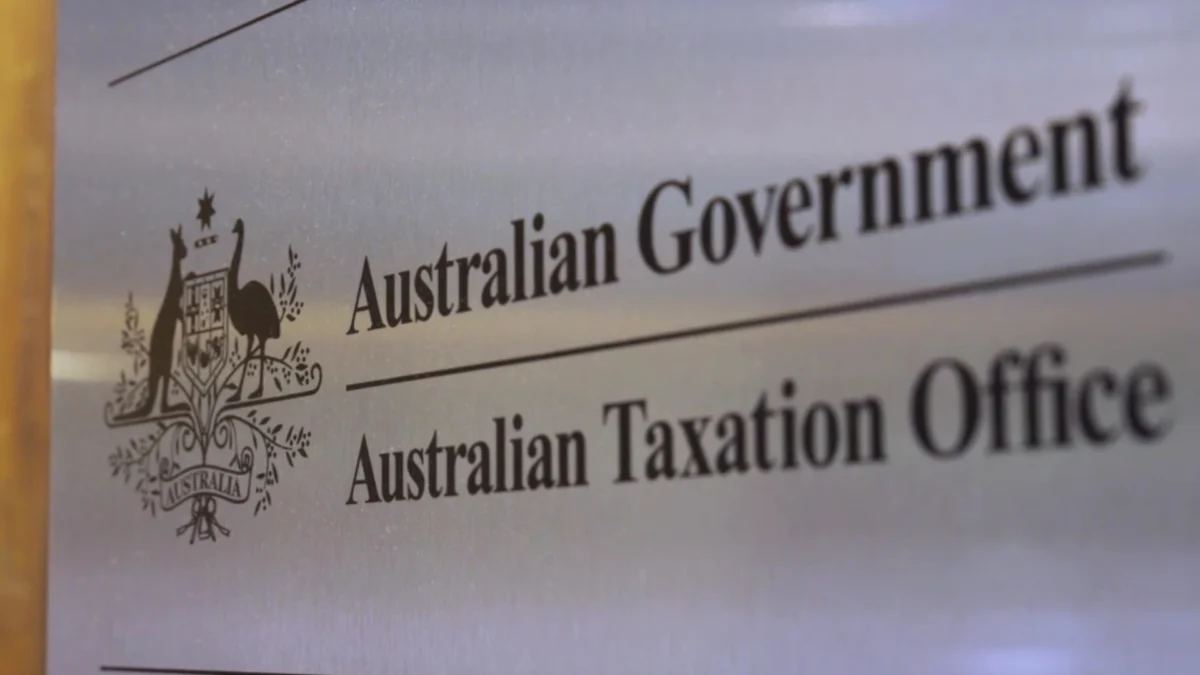
The friction began when the ATO announced its intention to stop accepting credit card payments for tax obligations, a move driven by concerns over mounting transaction fees. The tax office projected that its card acceptance costs would balloon to approximately $200 million annually, a figure it deemed unsustainable in the current fiscal climate.
This announcement followed the October 1 introduction of a broader credit card surcharge ban, which inadvertently created a climate of uncertainty for taxpayers. Many small business owners, who utilize credit cards as a strategic tool to bridge the gap between tax deadlines and the receipt of their own client payments, were blindsided.
By mid-September 2026, the prospect of a November 30 cut-off date created a wave of anxiety across the SME landscape. Entrepreneurs, already navigating a high-interest-rate environment and sluggish consumer spending, viewed the potential removal of the credit card payment option as an existential threat to their liquidity.
The pressure mounted rapidly throughout September, culminating in the Treasurer’s Friday announcement. The government has committed to bankrolling the ATO’s card acceptance costs for the remainder of the 2026-27 financial year, with the hard deadline pushed out to July 2027. This window is intended to facilitate a period of "meaningful consultation" between the ATO and the small business sector, shifting the focus from immediate termination to long-term sustainability.
The Economic Implications: Why Credit Cards Matter to SMEs
To understand the outcry, one must look at the mechanics of small business operations in Australia. For many, a credit card is not merely a payment method; it is a vital line of credit. When an entrepreneur faces a BAS (Business Activity Statement) deadline but has not yet collected on their own invoices, the credit card acts as a bridge.
By utilizing credit cards to pay the ATO, businesses can ensure they meet their statutory obligations on time—avoiding late fees, interest charges, and the potential for audit scrutiny—while maintaining the operational cash flow necessary to pay staff, suppliers, and rent.
Denita Wawn, CEO of Master Builders Australia, highlighted the gravity of the situation, particularly for the construction industry. "The cumulative effect of recent policy decisions is making it harder, riskier and less attractive to run a small building business at the very time we need more of them delivering the homes, infrastructure and community facilities Australia relies upon," Wawn stated.
The concern is that removing this facility effectively forces small businesses to turn to more expensive or less accessible forms of finance, such as overdrafts or short-term business loans, which often come with higher interest rates and more stringent collateral requirements than credit cards.
Official Responses and Stakeholder Advocacy
The reaction from industry leaders has been one of cautious relief. Lynda McAlary-Smith, the Australian Small Business and Family Enterprise Ombudsman, was among the first to applaud the government’s intervention.
"This extension provides valuable breathing room for small businesses who use credit cards as a legitimate cash flow management tool to meet obligations on time and allows consultation about longer-term arrangements to take place," McAlary-Smith said. She noted that her office had been inundated with feedback from business owners who felt the ATO’s original timeline was detached from the realities of the current economic climate.
Andrew McKellar, chief executive of the Australian Chamber of Commerce and Industry (ACCI), described the original ATO plan as an "unacceptable situation." When questioned about the potential for legislative reform to force the ATO to maintain credit card facilities, McKellar suggested that the focus should remain on negotiation.
"I think you heard the Treasurer’s statement. What that provides is the time, the flexibility," McKellar told reporters in Canberra. He further hinted that the ATO might be able to leverage its scale to negotiate better merchant service fees with credit card providers, potentially reducing the $200 million annual cost burden that triggered the crisis in the first place.
The Cost of Compliance: Analyzing the $200 Million Figure
The ATO’s primary justification for the ban has been the high cost of transaction processing. However, industry analysts and business groups have questioned why the tax office is not treated similarly to other large-scale institutions.
Some industry experts suggest that the "sweetheart rates" often enjoyed by major corporations and government departments should be accessible to the ATO. If the ATO were to engage in a robust tender process or leverage its position as a government agency to negotiate volume-based discounts with the major card schemes, the $200 million figure could potentially be reduced significantly.
This technical aspect is expected to be a primary focus of the upcoming consultations. If the cost of acceptance can be lowered, the justification for removing the service vanishes, potentially paving the way for a permanent solution that satisfies both the tax office’s budget and the taxpayer’s need for flexibility.
Looking Ahead: The Path to 2027
The period between now and July 2027 represents a critical juncture for small business policy in Australia. The government has clearly signaled that while it is willing to provide a temporary safety net, the status quo is under review.
For the ATO, the challenge will be to demonstrate that it has engaged in good faith. This involves more than just periodic meetings; it requires a transparent assessment of how payment methods affect small business compliance. If the ATO proceeds with the ban in 2027 without offering a viable alternative—such as low-interest, government-backed payment plans or delayed tax deadlines—it risks alienating the very businesses that form the backbone of the national economy.
Industry bodies are already preparing their submissions for the consultation phase. Their primary objectives are twofold:
- To secure a permanent, low-cost payment mechanism that does not disadvantage small businesses compared to their larger counterparts.
- To ensure that any future transition away from credit cards is phased in a manner that does not trigger a liquidity crisis for vulnerable sectors, such as construction, hospitality, and retail.
Conclusion: A Pyrrhic Victory or a New Beginning?
The government’s decision to bankroll the ATO’s credit card fees is a significant win for small business advocacy, proving that collective pressure can indeed shift the dial on bureaucratic policy. However, the victory is essentially a stay of execution.
As Denita Wawn poignantly remarked, "While the government will step in to fill the ATO’s funding gap, unfortunately, small businesses do not have a white knight." The underlying economic pressures—inflation, labor shortages, and rising material costs—remain largely unaddressed.
The next 18 months will be a test of the government’s commitment to supporting the SME sector. Whether this period leads to a modernized, more flexible tax payment system or a return to the original, contentious plan remains to be seen. For now, small business owners have the temporary relief they desperately needed, but the conversation about the relationship between the tax office and the nation’s entrepreneurs is far from over. The coming months will require a delicate balance of fiscal responsibility from the ATO and pragmatic support for the businesses that keep Australia moving.