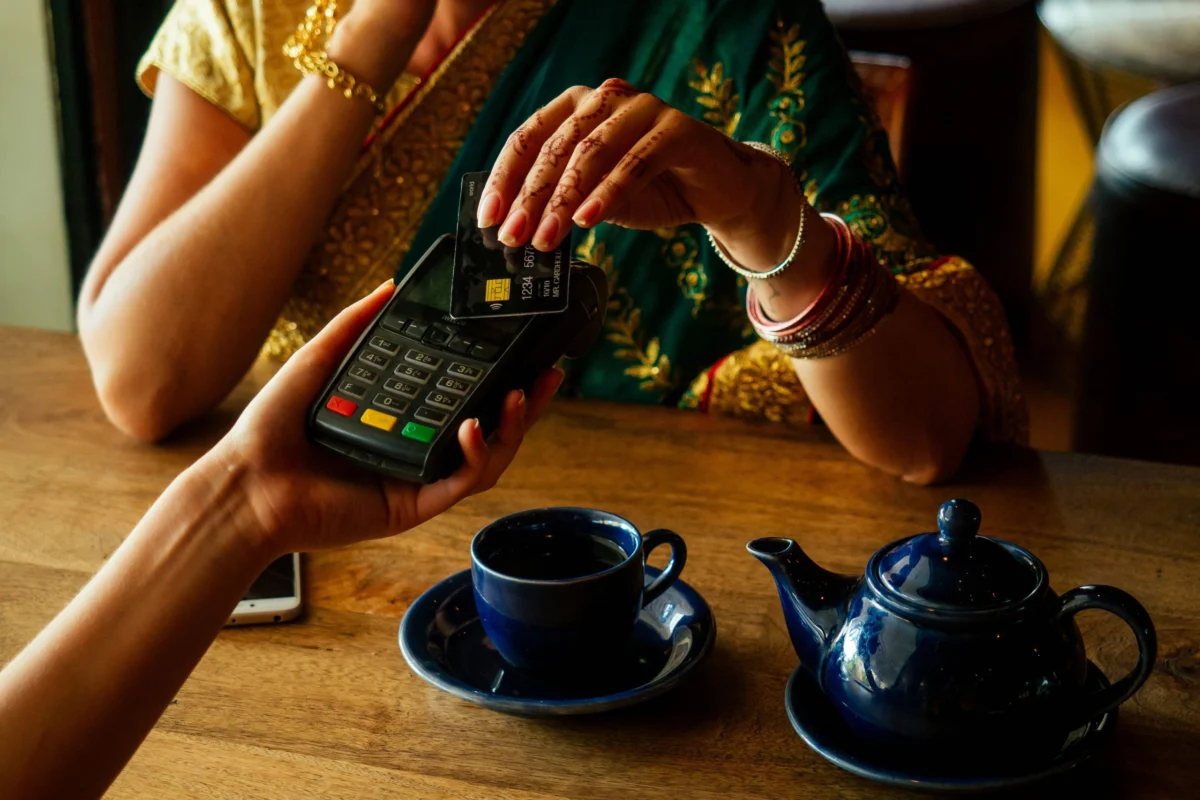
The landscape of Indian commerce underwent a seismic shift over the last decade, defined largely by the meteoric rise of the Unified Payments Interface (UPI). However, the system is now facing its most significant administrative challenge to date. The National Payments Corporation of India (NPCI) has opted to postpone the introduction of a controversial 0.4% merchant fee on transactions exceeding 2,000 rupees (approximately $21), a move that highlights the immense complexity of altering the economic foundations of a digital infrastructure that has become synonymous with daily life in the world’s most populous nation.
Originally slated for implementation within days, the rollout has been pushed back by several months—likely until January—to accommodate merchant readiness and avoid disrupting the critical festive shopping season. This delay is more than a mere scheduling adjustment; it serves as a masterclass in the delicate balancing act required when governing a payment network that is deeply embedded in the national economy.
The Core Conflict: Free Access vs. Economic Sustainability
Since its inception, UPI has been lauded for its "zero-MDR" (Merchant Discount Rate) policy. By ensuring that transactions were free for both users and merchants, the NPCI successfully incentivized mass adoption, turning street-side tea vendors and high-end retailers alike into participants in the digital economy.
However, the NPCI’s recent decision to impose a 0.4% fee on transactions over 2,000 rupees represents a fundamental pivot. The rationale is clear: maintaining a network that processes tens of billions of transactions requires significant capital for infrastructure, security, and innovation. The burden of this cost can no longer be sustained solely by subsidies. Yet, the reaction from the merchant community was swift and vocal. Many retailers, operating on thin margins, view any additional fee as a direct hit to their profitability, and their lack of preparation—partly born of skepticism that the NPCI would actually move forward—created a bottleneck that the regulator could not ignore.
Chronology of the Impasse
The path to this delay was paved with miscalculations and logistical hurdles.
- The Announcement: Late last month, the NPCI signaled its intent to implement the 0.4% levy on larger transactions. The move was intended to align UPI’s economic model with global standards while ensuring the long-term viability of the platform.
- The Merchant Pushback: Almost immediately, industry groups representing small and medium-sized enterprises (SMEs) expressed concern. The primary grievance was not just the cost, but the technical and operational readiness required to track, account for, and reconcile these new fees.
- The "Bluff" Sentiment: As Don Apgar, Director of Merchant Payments at Javelin Strategy & Research, points out, many merchants operated under the assumption that the NPCI was merely testing the waters. "A certain percentage of the merchants are skeptics and don’t do anything based on their belief that NPCI won’t follow through," Apgar noted.
- The Impending Festive Season: October through December marks the "festive season" in India, a period where consumer spending reaches its annual zenith. Introducing a new cost structure during this high-stakes period threatened to create chaos at the point of sale.
- The Delay: Recognizing the potential for systemic friction, the NPCI quietly agreed to defer the implementation. Reports now suggest the fee will be revisited in January, providing a cooling-off period for both regulators and the retail sector.
Supporting Data: The Scale of the Ecosystem
To understand why the NPCI is treading so cautiously, one must look at the staggering scale of the UPI ecosystem. In August alone, UPI processed nearly 25 billion transactions, with the total value exceeding $312 billion.
This volume is not just a statistical milestone; it is the lifeblood of the Indian economy. From rural agricultural hubs to the bustling tech corridors of Bengaluru, UPI has replaced cash for millions. Because the system is so "sticky," any technical glitch or administrative friction can have cascading effects on consumer confidence.
The 0.4% fee is targeted specifically at transactions over 2,000 rupees to minimize the impact on the "micro-transaction" economy—the millions of small, daily purchases that define UPI usage. Yet, even this targeted approach creates friction. For a merchant processing hundreds of such transactions a day, the cumulative cost of the 0.4% fee is non-trivial, prompting a necessary, albeit painful, recalibration of their digital sales strategy.
Official Responses and Strategic Caution
The NPCI finds itself in the crosshairs of a classic regulatory dilemma: how to professionalize an economy-wide utility without alienating the very participants who make the network valuable.
Don Apgar emphasizes that the NPCI’s caution is well-founded. "UPI has been so successful and commands such dominant market share in India that it wouldn’t make sense to blow up the network by forcing through a change that merchants aren’t ready to support," Apgar explained.
By forcing the change too quickly, the NPCI risked a revolt—not necessarily by abandoning the platform, which is difficult given its ubiquity, but by creating a culture of resentment that could hinder future upgrades or policy changes. The decision to delay is an acknowledgment that market dominance does not grant the right to ignore operational realities. If the regulator alienates the merchants, it inadvertently makes the customers’ lives harder—a cycle of friction that no digital payment system can afford.
Implications: A Lesson for Global Regulators
The situation in India is being watched closely by regulators in the United States and beyond, where similar debates regarding interchange fees and payment processing costs are currently unfolding.
The U.S. Perspective
In the United States, states like Illinois have explored legislation that would limit interchange fees on taxes and tips. Much like the Indian experience, these legislative attempts have faced repeated delays and intense lobbying. The common thread is the "wait-and-see" approach adopted by stakeholders.
Apgar notes that the skepticism observed in India is a universal reaction to regulatory uncertainty. "Right now, nobody thinks it will actually go into effect, so nobody is doing anything to support it," he said. The implication is that regulators often fail to realize that the announcement of a fee is insufficient to ensure readiness. If a policy is perceived as a "bluff," the private sector will remain idle until the last possible moment, leading to the exact kind of "scrambling" currently seen among Indian retailers.
The Future of Payment Economics
The broader lesson is that payment networks, once they reach a state of hyper-utility, cease to be just financial tools; they become public infrastructure. Changes to this infrastructure require more than just a decree from a central authority; they require:
- Technical Synchronization: Ensuring that every point-of-sale terminal and banking app is configured to handle the new fee structure seamlessly.
- Merchant Education: Bridging the gap between the regulator’s vision and the merchant’s bottom line.
- Gradual Phasing: Avoiding the "big bang" implementation in favor of phased rollouts that accommodate seasonal business cycles.
Conclusion: The Path Ahead
The delay of the UPI fee is not a defeat for the NPCI, but rather a tactical retreat that recognizes the realities of the market. By pushing the implementation to January, the NPCI gains the opportunity to consult more effectively with merchant associations, refine the technical deployment, and ensure that the fee does not dampen the holiday spirit of the Indian economy.
For the rest of the world, the Indian experience provides a clear warning: you cannot simply switch the business model of a vital, deeply-embedded national payment system overnight. The friction of transition is high, and the risks of alienating the merchant class are significant. As the NPCI prepares for the January rollout, the global financial community will be watching to see if a more collaborative, measured approach can successfully bridge the gap between economic sustainability and the seamless, low-friction user experience that has defined the UPI era.
Ultimately, the strength of a payment network lies not just in its transaction speed or its reach, but in the trust of those who use it daily. Balancing that trust with the need for systemic fiscal health remains the ultimate challenge for the architects of modern digital finance.