The rapid proliferation of generative AI has fundamentally altered the landscape of financial services marketing. As institutions race to deploy automated content generation to reach consumers, the friction between speed-to-market and regulatory adherence has reached a critical inflection point. In a strategic move to address this imbalance, Sedric, an agentic AI compliance platform founded in 2020, has announced it is joining the American Fintech Council (AFC).
This partnership places Sedric at the heart of the largest US trade body representing both established banks and agile fintech firms. By securing a seat at the table, the company intends to pivot from being a mere service provider to an architect of the practical standards governing responsible AI deployment in financial communications.
Main Facts: The Evolution of Compliance
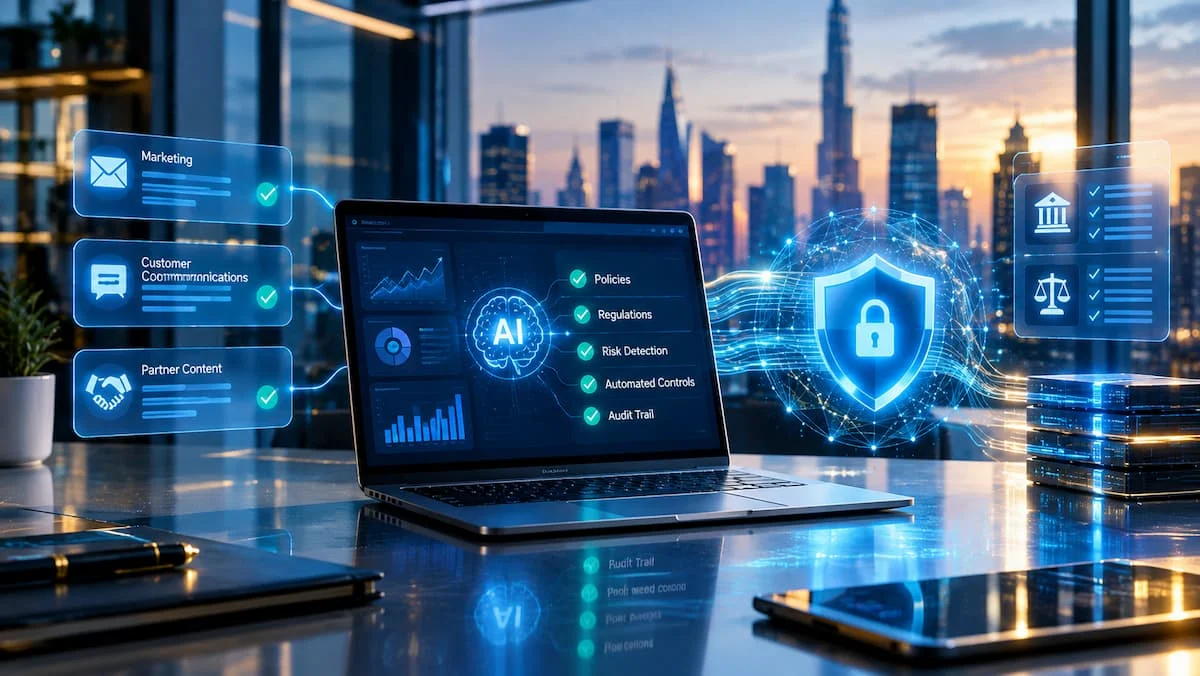
Sedric’s core offering is a sophisticated, agentic AI platform designed to codify complex regulatory requirements into automated, real-time controls. Unlike legacy systems that rely on periodic manual audits, Sedric’s architecture sits directly within an organization’s existing CRM and communication technology stacks.
The platform operates as a proactive gatekeeper, pre-screening outbound marketing assets, customer service scripts, and partner-generated content before they reach the public. By logging every compliance decision, the system creates an immutable, auditable trail that regulators can review with ease. This transition—from retrospective, sample-based review to continuous, real-time supervision at scale—represents a seismic shift in how financial institutions manage risk.
Chronology: A Path to Agentic Governance
Founded in 2020, Sedric emerged during a period of unprecedented digital acceleration, as the COVID-19 pandemic forced traditional banks to embrace digital-first engagement models.
- 2020: Sedric is founded with a vision to automate the compliance burden through AI.
- 2021-2023: The company refines its "agentic" approach, moving beyond simple keyword flagging to intent-based analysis of financial marketing materials.
- 2024: As the CFPB and other regulators heighten scrutiny on AI-driven financial advice, Sedric secures significant traction among mid-market and enterprise-level financial firms.
- 2026 (Current): Sedric formally joins the American Fintech Council (AFC), signaling an intent to transition from a private software provider to a thought leader in industry-wide AI standards.
The Partnership Gap: A Strategic Vulnerability
The most pressing issue addressed by the Sedric-AFC partnership is the "distributed financial product" dilemma. In the modern financial ecosystem, institutions rarely interact with consumers directly; instead, they rely on a complex web of affiliates, embedded finance partners, and third-party marketing channels.
Despite this outsourcing, regulatory accountability remains firmly with the licensed financial institution. The Consumer Financial Protection Bureau (CFPB) has repeatedly demonstrated its willingness to hold banks accountable for the conduct of their marketing partners, creating a significant enforcement risk.

Nir Laznik, CEO and co-founder of Sedric, has been vocal about the dangers of this disconnect. "Financial products are increasingly distributed through partners, affiliates, and embedded channels, but accountability still sits with the licensed institution," Laznik explains. "That gap is where consumer harm and enforcement risk actually live, and it’s widening as AI collapses the cost of producing content and conversations at scale. Reviewing a small sample after the fact was never designed for this."
This observation is not merely a marketing pitch; it is a diagnosis of a systemic weakness. Generative AI allows for the creation of thousands of variations of marketing copy in seconds. When compliance teams are forced to rely on manual spot-checks, they are effectively auditing a fraction of a percent of the total content output, leaving the organization exposed to "hidden" compliance violations buried within the automated stream.
Supporting Data and Market Context
The compliance technology (regtech) sector is currently experiencing a gold rush, driven by the dual pressures of technological innovation and regulatory tightening. Sedric faces competition from both established legacy players and agile AI-native entrants.
However, Sedric differentiates itself through its "agentic architecture." While traditional tools flag problematic content for human review—creating bottlenecks and operational drag—Sedric’s agents are designed to execute policy rules autonomously. This approach aims to "close the loop" faster, ensuring that only compliant, pre-vetted content makes it to the end consumer.
The Regulatory Backdrop
The urgency of this technology is underlined by an increasingly aggressive regulatory climate:
- United States: The CFPB continues to prioritize the enforcement of rules against unfair, deceptive, or abusive acts and practices (UDAAP) in digital marketing. Simultaneously, the Federal Trade Commission (FTC) has issued stringent guidance regarding the disclosure of AI-generated content and endorsements.
- United Kingdom: The Financial Conduct Authority (FCA) has enforced its "Consumer Duty" for over a year, placing an explicit, ongoing obligation on firms to ensure that all customer communications—regardless of the channel or the creator—are clear, fair, and not misleading.
For global firms, these regulatory regimes represent a massive, recurring cost. Sedric’s platform is designed to absorb this cost, turning compliance from a reactive, high-friction overhead into a streamlined, automated product feature.
Implications for the Future of Finance
The membership of the American Fintech Council (AFC) offers Sedric a vital platform to influence the future of "Responsible AI." As the industry moves toward drafting voluntary standards, Sedric’s presence suggests a move toward codifying AI safety.

1. Toward Standardized Auditing
The next logical step for Sedric and its peers will be to align their internal controls with globally recognized frameworks, such as the NIST AI Risk Management Framework (RMF) or ISO 42001. By subjecting their automated controls to independent, third-party audits, Sedric could provide the "gold standard" of proof that banks require before trusting an autonomous agent with their compliance sign-offs.
2. The Shift in Compliance Roles
As these tools become more prevalent, the role of the human compliance officer will fundamentally change. Instead of "policing" every piece of content, these professionals will transition into "policy engineers," responsible for setting the parameters, guardrails, and ethical constraints within which the agentic AI operates.
3. Increased Transparency
One of the most significant implications is the potential for increased enterprise transparency. If Sedric can prove that its platform consistently catches non-compliant content across distributed networks, it may lead to a market where "Certified Compliant by Sedric" becomes a seal of trust for consumers and regulators alike.
Conclusion: A New Era of Supervised Automation
The marriage of Sedric’s agentic technology with the policy-shaping power of the American Fintech Council marks a transition in the industry. Financial firms are no longer satisfied with simply "trying their best" to keep up with AI; they are looking for structural, automated solutions that can match the speed of their marketing engines.
As Nir Laznik noted, the gap between distributed delivery and centralized accountability is where risk lives. By moving to close that gap through the adoption of agentic supervision, the industry is not just adopting new tools—it is fundamentally rewriting the playbook for consumer protection in the age of generative AI. Whether this partnership leads to a new industry standard or simply a more efficient way to manage risk remains to be seen, but the intent is clear: in the future of finance, compliance will be automated, continuous, and absolute.