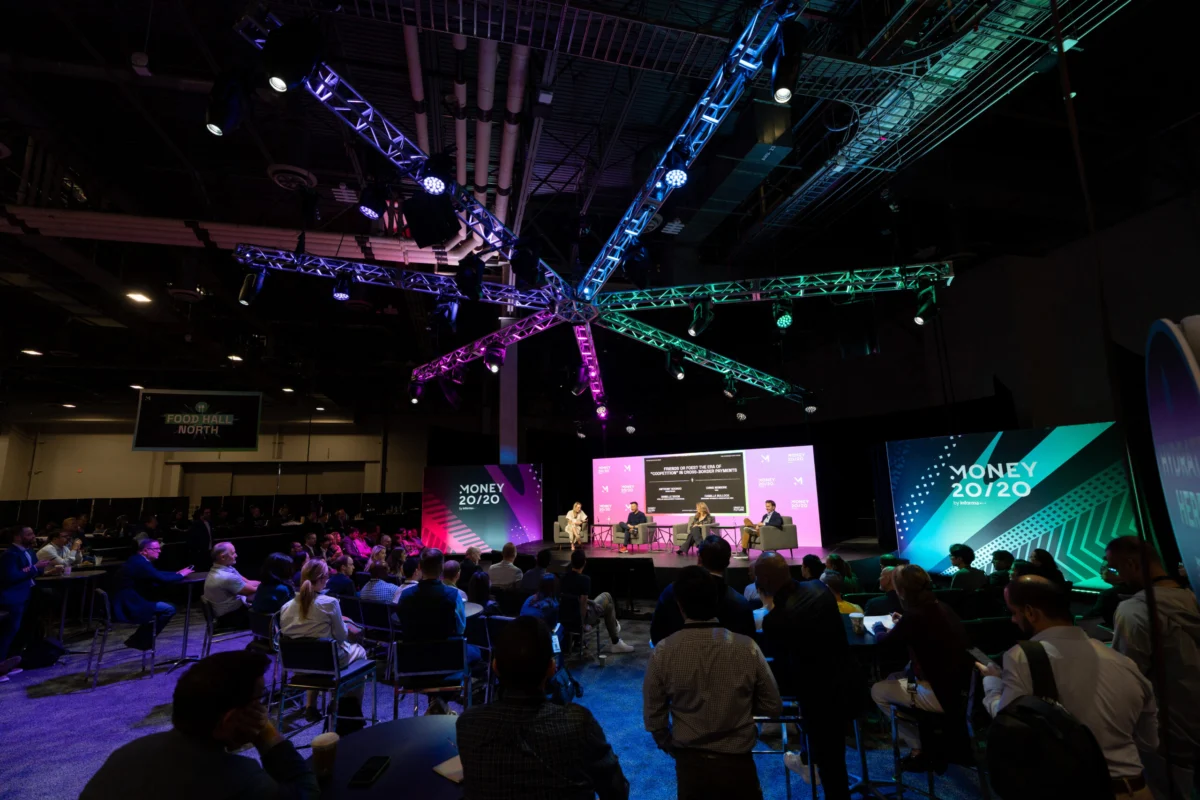
For three days in Las Vegas, the global financial community grappled with a singular, existential question: when money begins to move itself, who ultimately carries the risk? This inquiry defined the atmosphere of the recent industry gathering, as stablecoins, AI agents, and tokenized deposits moved from theoretical pilot programs to the center stage of the global economy.
By the final morning of the conference, the fog of uncertainty began to lift. In a landmark development, the Office of the Comptroller of the Currency (OCC) finalized the first federal rulebook under the GENIUS Act. This move represents more than just a regulatory update; it signals a fundamental shift in how the United States government intends to govern the intersection of autonomous software and institutional banking.
The Chronology of a Regulatory Milestone
The timeline of the conference mirrored the industry’s evolution. Day one was defined by the conceptual challenges posed by AI agents—autonomous entities capable of executing financial transactions without human intervention. Day two saw a flurry of industry-led initiatives, with participants presenting their own standards, certificates, and code-based safeguards in an attempt to self-regulate before the government could intervene.
On the closing Wednesday morning, just hours before the "Money Hall" doors were set to lock for the final time, the OCC delivered its verdict. As the first agency to finalize its rule under the GENIUS Act, the OCC established a definitive framework for how banks and non-bank entities may function as permitted payment stablecoin issuers. This was the moment the industry had been waiting for: a federal standard to replace the fragmented, state-by-state approach that has historically hindered mass adoption.
Main Facts: The OCC’s New Rulebook
The OCC’s finalized rule, which takes effect in January, serves as the inaugural federal blueprint for stablecoin oversight. Key components of the regulation include:
- Reserve Requirements: Issuers must maintain reserves that fully back the stablecoins currently in circulation.
- Redemption Windows: The rule mandates that issuers must generally meet redemption requests within two business days, ensuring liquidity for holders.
- Operational Standards: The regulation imposes rigorous requirements regarding custody, capital adequacy, and auditing procedures. It also establishes a framework for foreign issuers operating within the U.S. jurisdiction.
- AML and Sanctions: While the rule sets the foundational structure, anti-money laundering (AML) and sanctions compliance are being deferred to subsequent, collaborative rulemaking with the Treasury Department.
Comptroller Jonathan Gould characterized the framework as a "clear, practical" approach to balancing innovation with systemic stability. However, the rule has already drawn fire from the American Bankers Association, which expressed concern that the framework leaves a "door open" for non-bank platforms to offer rewards that could siphon deposits away from traditional community lenders.
The Yield Debate and the Preservation of Trust
The most contentious point in the new regulatory landscape remains the issue of yield. While the OCC has maintained the prohibition against issuers paying interest simply for holding a stablecoin, it has softened its stance on the presumption that certain affiliate arrangements are merely attempts to circumvent this ban.

Instead of a blanket presumption of guilt, the OCC will evaluate reward programs on a case-by-case basis, retaining the authority to intervene if it suspects evasion. This shift toward nuance is seen by some as a victory for flexibility, though it adds a layer of regulatory subjectivity that banks are wary of.
The broader discussion throughout the week emphasized that trust is not merely a "soft metric"—it is a critical growth strategy. During a panel featuring CMOs from Early Warning, JPMorganChase, and PNC, the consensus was clear: the financial industry is moving away from the "move fast and break things" ethos of early fintech, toward an era where the invisibility of the rails is the ultimate measure of success. As Neetika Bansal of Stripe noted, customers no longer ask for "stablecoins"; they ask for cross-border payments that arrive reliably and instantly.
Controls Written Into the Payment: The New Liability Standard
As regulators debated the legal parameters of stablecoins, the private sector moved to solve the liability question through technological enforcement. The narrative of the week was defined by a transition toward "agentic" security.
Visa’s announcement on Wednesday showcased this shift, introducing advanced controls for commercial card payments. These tools include automated verification to ensure funds reach the intended supplier, 3-D Secure authentication for virtual card users, and granular limits on spend, location, and timing. Furthermore, Visa’s pilot with BILL and Billtrust demonstrated how AI agents can pay approved invoices using tokenized credentials, effectively removing the need for risky, shared logins.
Similarly, Ninth Wave unveiled its "Agentic Control Layer." By requiring every agent to be tied to a registered, accountable operator, and by masking account numbers before they reach AI models, the company is establishing a "trust layer" that sits between legacy banking infrastructure and modern, autonomous agents.
These developments align with the industry’s emerging consensus: nobody hands a digital agent "the bag" without a named human or corporate operator, a limited mandate, and an immutable record of every transaction request.
Official Responses and Strategic Implications
The implications of these developments extend far beyond the immediate regulatory changes. FDIC Chairman Travis Hill has already signaled that the work is far from finished. Following the implementation of the GENIUS Act rules, the FDIC intends to focus on the complexities of tokenized deposits, particularly the thorny issue of how to resolve a bank failure when deposits are moving across decentralized, weekend-active rails.

The industry is also grappling with the question of accreditation. Who validates an agent? Whether the market converges on a unified "Trusted Agent" registry—or whether disparate networks create fragmented silos—will determine the friction levels of the next decade of finance.
The Road Ahead: From Pilot to P&L
As the conference concluded, the focus shifted from technical capability to operational sustainability. The "innovation" phase is largely complete; the "operating" phase has begun.
Three primary challenges define the road ahead:
- The Reward/Deposit Divide: As the market structure bill remains stalled in the Senate, the boundary between a stablecoin reward and a deposit rate will continue to be litigated case by case, creating a "regulation by enforcement" environment that banks find deeply challenging.
- Network Interoperability: With major players like Visa, Ninth Wave, and the FDIC all proposing different versions of "trusted operator" schemes, the industry faces a critical juncture. Convergence on standards will be essential for the seamless movement of capital.
- Profitability at Scale: Many of the technologies discussed—from supplier validation tools to read-only agent layers—are still in pilot or early release. The true test of these innovations will be their ability to move from the "sandbox" into the quarterly earnings reports of major financial institutions.
Conclusion: The Disappearance of the Technology
Perhaps the most telling remark of the week came from Coinbase’s Shan Aggarwal. When asked where he sees tokenization in 2030, he expressed a hope that the category itself disappears. "I think we just talk about assets," he said.
This sentiment perfectly encapsulates the shift that occurred in Las Vegas. The industry has moved past the need to evangelize the underlying technology. The debate is no longer about whether stablecoins or AI agents are viable, but about who vouches for the participants, who sets the standards, and whether the end-user ever needs to know the difference.
As the financial sector prepares for the next chapter in 2027, the goal is clear: the infrastructure of the future must be invisible, the risks must be explicitly managed, and the trust must be absolute. The regulators have provided the starting line; the race to integrate these autonomous systems into the core of global commerce has officially begun.