Australia’s fintech sector is no longer the scrappy, experimental industry it was a decade ago. It has matured into a sophisticated engine of economic growth, characterized by sustainable revenue streams and a focus on enterprise-level solutions. However, as the latest industry data reveals, this maturation has hit a regulatory and structural glass ceiling. While Canberra continues to offer incremental tax tweaks, industry leaders warn that these measures are insufficient to address the systemic gridlock hindering funding, procurement, and competitive parity.
The 2026 Fintech Annual Census, a comprehensive study conducted by RSM in partnership with FinTech Australia, paints a picture of an industry that has grown up—but is now being held back by its own success.
The State of Play: Main Facts and Industry Performance
The 2026 Census, which surveyed 135 fintech businesses, provides the most granular look at the health of the sector to date. The headline figures suggest a resilient and increasingly profitable industry.
Nearly half (47%) of surveyed companies are currently profitable, a significant milestone for a sector previously defined by high-burn, growth-at-all-costs mentalities. Furthermore, 66% of respondents reported annual revenues exceeding $1 million. This transition from "pre-revenue" to "sustainable business" indicates that Australian fintechs are moving away from speculative consumer apps toward robust B2B models, with 67% of firms primarily targeting other businesses.
Perhaps most encouraging is the industry’s commitment to growth. Despite global economic headwinds and a tightening venture capital market, 59% of respondents are actively planning to expand their headcount. This is a critical indicator of economic contribution; fintechs are no longer just software developers—they are significant employers of highly skilled talent, contributing to the broader digital transformation of the Australian economy.
However, beneath these positive statistics lies a growing tension. While the industry is scaling, the support mechanisms provided by the federal government have remained static or, at best, reactive.
A Chronology of Stagnation: From Innovation to Integration
To understand the current impasse, one must look at the timeline of the Australian fintech journey over the last decade.
- 2014–2016: The Era of "Fintech-Friendly" Policy: This period saw the initial formation of FinTech Australia and the introduction of the first wave of tax incentives, including the Early Stage Innovation Company (ESIC) scheme. The focus was on incentivizing risk-taking.
- 2017–2020: The Regulatory Build: Australia made international headlines with the introduction of the Consumer Data Right (CDR) and the rollout of the New Payments Platform (NPP). This was the "infrastructure" phase, where the government acted as a catalyst for sector-wide connectivity.
- 2021–2023: The Pandemic Boom and Correction: The surge in digital adoption during COVID-19 led to a record-breaking investment cycle. This was followed by a sharp market correction in 2022–2023, exposing the vulnerabilities of startups that relied too heavily on cheap capital.
- 2024–2026: The Maturity Challenge: We are currently in a period where "scale-ups" are struggling to transition into "incumbents." The industry has moved beyond the need for early-stage grants and is now demanding structural reform in government procurement, competition policy, and regulatory sandbox efficacy.
Supporting Data: Where the Bottlenecks Lie
The Census data makes it clear: the primary obstacles are no longer about "innovation" in the traditional sense, but about "integration."
The Funding Gap
While tax concessions like the ESIC scheme are helpful for pre-revenue startups, they do little to assist mid-market firms looking to scale internationally. The "Series B and beyond" gap remains a perennial issue in the Australian venture capital landscape. Without a deeper pool of domestic institutional capital, many of Australia’s most promising fintechs are either acquired by foreign entities prematurely or are forced to relocate their headquarters to the US or UK to access growth capital.
The Procurement Gridlock
A recurring theme in the Census feedback is the difficulty of selling to the public sector. Despite the government’s stated goal of digital transformation, the procurement process remains siloed, risk-averse, and prohibitively expensive for smaller fintechs. Many firms report that the administrative burden of becoming a government vendor outweighs the potential revenue, effectively handing the market to global tech giants who have the legal and compliance teams to navigate the red tape.
The AI Imperative
The industry is currently obsessed with Artificial Intelligence, viewing it as the "magic bullet" for efficiency. However, the data suggests that while AI adoption is high, it is not a panacea for poor market access. Fintechs are integrating AI into fraud detection, customer service, and credit scoring, but these technological gains are being neutralized by the time wasted in regulatory limbo.
Official Responses and the View from Canberra
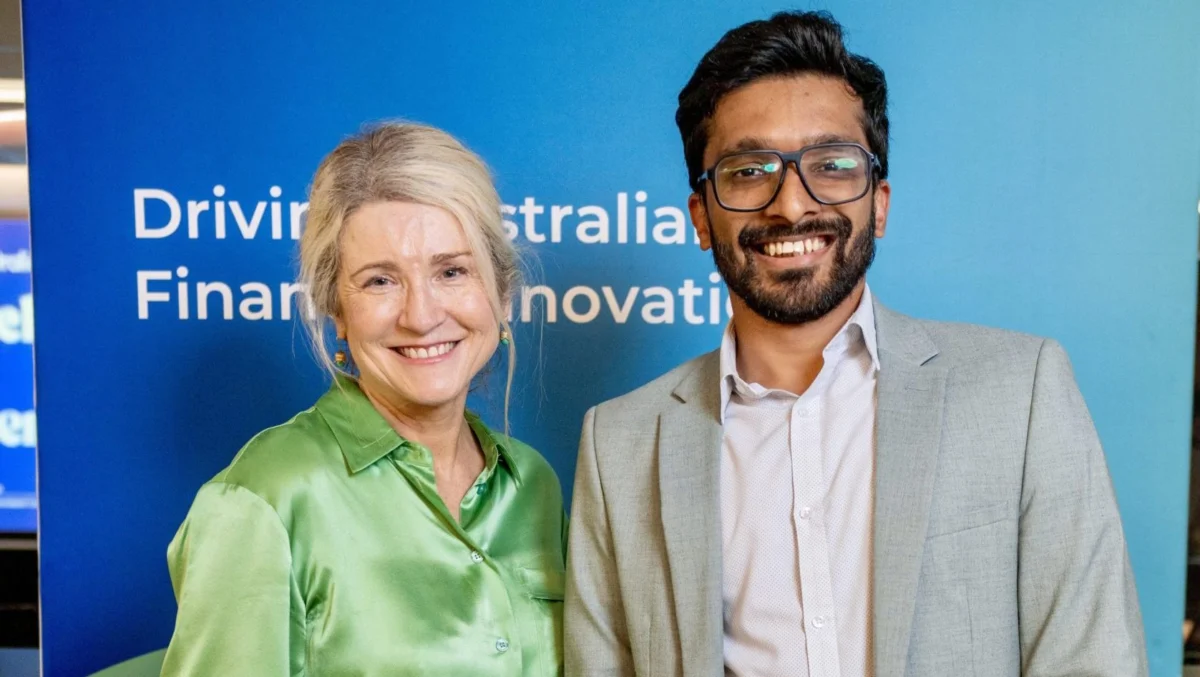
The tension between the fintech sector and the government is becoming increasingly public. FinTech Australia, led by Chair Sarah Gorman and CEO Rehan D’Almeida, has been vocal about the need for a shift in policy focus.
"Tax tinkering is not a strategy for growth," a representative noted in recent industry briefings. The sentiment from the advocacy body is that the government is confusing "support for startups" with "support for an industry."
Canberra’s traditional response—offering R&D tax credits—is viewed by the industry as a backward-looking tool. While it helps recoup some costs for past work, it does nothing to solve the forward-looking problems of market entry and regulatory hurdles. Government officials argue that they are balancing the need for innovation with the necessity of maintaining financial stability. However, critics argue that this conservative approach is creating a "lost decade" for Australian financial innovation, as regional neighbors like Singapore and Hong Kong streamline their regulatory environments to attract the very companies Australia is letting slip through the cracks.
Implications: What Happens If We Do Nothing?
The implications of continued gridlock are severe. If Australia fails to modernize its procurement and regulatory frameworks, it risks becoming a "service branch" economy rather than an innovation hub.
- Brain Drain: If local founders cannot find the growth capital or the B2B customers they need within Australia, they will continue to depart. This results in a loss of intellectual property, tax revenue, and high-paying jobs.
- Stagnation of Digital Infrastructure: The Australian financial sector remains highly concentrated among the "Big Four" banks. Fintechs were meant to be the agents of disruption that lowered costs and improved customer choice. If these companies cannot scale, the current oligopolistic structure of the Australian banking sector will remain unchallenged, to the detriment of the consumer.
- The "Innovation Trap": We risk becoming a country that is excellent at inventing new financial technologies but terrible at commercializing them. Australia has historically struggled to turn R&D into global market leaders; the fintech sector is currently the best chance to break that cycle.
A Path Forward
To unlock the next phase of growth, the government must move beyond tax incentives and address the structural pillars of the fintech ecosystem. This includes:
- Mandatory Procurement Quotas: Implementing specific targets for government departments to source a percentage of their digital and financial services from local startups and SMEs.
- Regulatory Harmonization: Simplifying the licensing process for fintechs to operate across borders, reducing the cost of compliance for firms looking to export their services.
- Institutional Capital Incentives: Encouraging superannuation funds to allocate a larger, dedicated portion of their portfolios to Australian venture capital and late-stage growth funds, ensuring that domestic capital backs domestic winners.
The 2026 Fintech Annual Census is a mirror held up to Canberra. It shows an industry that has done the hard work of building sustainable, profitable businesses. Now, the ball is firmly in the government’s court. The question is no longer whether Australian fintechs have the potential to compete on the global stage, but whether the Australian government has the ambition to let them.
The era of relying on tax tweaks is over. The era of structural reform must begin if Australia is to secure its place in the future of global finance.