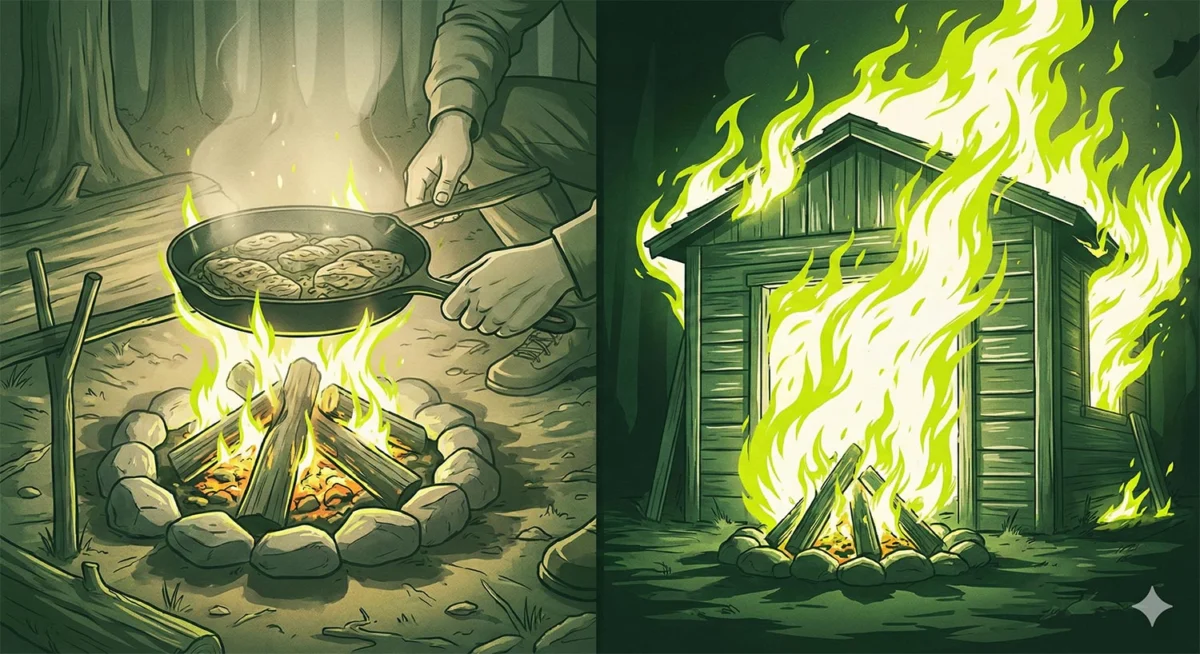
In the fast-paced world of e-commerce, access to capital is often framed as the ultimate accelerant. It is the fuel that buys inventory, launches marketing campaigns, and scales operations from five figures to seven. Yet, for many entrepreneurs, this accelerant can quickly become an incendiary device.
The reality of business debt is often masked by slick user interfaces and "one-click" loan approvals. However, the consequences of mismanaged capital are rarely digital—they are profoundly physical. They manifest in shaking hands, sleepless nights, and the looming threat of losing one’s personal assets.
The Anatomy of a Crisis: A Case Study in Risk
The vulnerability of the modern e-commerce founder was laid bare in a recent, harrowing account involving a business owner named Bill. Sitting in a parked car, staring at a termination notice from a primary supplier—a company responsible for 80% of his store’s stock—Bill faced an immediate, existential threat.
The business had been built on debt. More importantly, it was built on a seven-figure personal guarantee (PG). If the business collapsed, the bank would not simply liquidate the LLC; they would pursue Bill’s home, his brokerage accounts, and his personal savings. While this specific instance turned out to be a clerical error—a false alarm that was retracted—the twenty minutes of uncertainty burned a permanent lesson into the minds of those involved: debt is a tool that can turn into a threat in the blink of an eye.

The Chronology of Financial Erosion
The journey toward a "debt death spiral" rarely happens overnight. It follows a predictable, dangerous trajectory that often catches even the most seasoned entrepreneurs off guard.
1. The Proactive "Need": The Initial Infusion
Most founders do not seek debt out of recklessness; they seek it out of ambition. They are busy, growing, and hit a point where cash flow fails to keep pace with demand. They see an opportunity to increase inventory or ad spend, and they click "apply" on a loan platform.
2. The Misunderstanding of Terms
The primary failure at this stage is a lack of rigorous financial modeling. Many founders bypass the creation of a 13-week forward-looking cash flow forecast. Without this map, they enter into agreements—particularly Merchant Cash Advances (MCAs)—without realizing that the daily repayment percentage might effectively starve the business of the operating margin it needs to survive.
3. The "Masking" Phase
When cash flow tightens, the debt is used to cover the gap. This is the critical turning point. Instead of addressing the underlying business issue—be it thin margins, high customer acquisition costs (CAC), or bloated inventory—the founder uses the new capital to "mask" the symptoms. The business looks healthy on the surface because the accounts are funded, but the underlying model is still broken.

4. The Stacking Spiral
As the original loan eats into margins, the business becomes less profitable. To stay afloat, the founder seeks additional capital. This is where "stacking" begins: taking out a second or third loan to pay the installments of the first. Each new loan carries a higher effective interest rate and provides a shorter runway, accelerating the descent toward insolvency.
Supporting Data: The Illusion of "Cheap" Capital
One of the most persistent myths in e-commerce financing is the perceived cost of capital. Founders frequently confuse "fees" with "interest rates."
Consider a standard Merchant Cash Advance: A company borrows $100,000 and agrees to pay back $110,000. On the surface, the "10% fee" sounds reasonable. However, if the lender demands that $110,000 back in just 10 weeks, the reality changes drastically.
The Real Math
- Stated Fee: 10%
- Repayment Window: 10 weeks
- Effective Annual Percentage Rate (APR): In many cases, this structure results in an APR between 75% and 100%.
Because the lender is pulling a percentage of daily revenue, the founder is effectively paying a premium on capital that they only hold for a matter of days. When the math is stripped of its marketing terminology, it becomes clear that many founders are paying exorbitant rates that would make a traditional lender shudder.

Implications: The Weight of the Personal Guarantee
The most significant, yet often overlooked, component of business borrowing is the personal guarantee (PG). A PG acts as a bridge between the business entity and the individual. By signing one, the founder effectively waives the protection of the corporate veil.
Many founders sign PGs on almost every credit instrument they hold:
- Business Credit Cards: Most high-limit cards (Amex, Chase, Capital One) require a PG.
- Term Loans and Lines of Credit: Often secured against the founder’s personal net worth.
- Equipment Financing: Often carries personal liability.
The implication is clear: if the business fails, the liability transfers to the founder’s personal life. Before signing, every entrepreneur should ask themselves: "Would I write a personal check for this amount to this business today, knowing it might disappear?" If the answer is no, the risk is likely too high.
Strategic Shifts: A Path to Sustainability
To avoid the pitfalls described, founders must pivot from reactive, crisis-based financing to a proactive, disciplined model.

Build Relationships Early
The best time to secure a line of credit is when the business does not need it. Banks prefer to lend to healthy companies with 2–3 years of clean financials. Once a crisis hits, the bank will see the stress in the numbers and decline the application. By securing a line of credit while the business is thriving, founders create an "optionality" buffer that can save them when the market turns.
Obsessive ROI Tracking
Every dollar of debt must have an explicit, projected return. If a loan is taken to fund inventory, that inventory must be tracked to ensure it is generating a return that exceeds the cost of the capital. If the funds are not immediately deployed, they should be moved to a high-yield account rather than left sitting in a checking account where they can be spent on non-essential overhead.
Addressing the Broken Model
If a business cannot generate enough cash to fund its next purchase order, it is not a "timing" problem—it is a business model failure. Whether it is poor pricing, excess stock, or inefficient marketing, borrowing will only serve to compound the error. The focus must be on fixing the margins and optimizing inventory turns before considering additional leverage.
Conclusion: The Path Forward
Debt is not inherently evil. When used to scale a proven, profitable business, it is a powerful instrument. However, when used as a bandage for a broken business, it is a fast track to ruin.

The e-commerce landscape is littered with the remnants of businesses that grew too fast, borrowed too much, and ignored the fundamentals of cash flow. By prioritizing transparency, modeling the true cost of capital, and treating personal guarantees with the gravity they deserve, founders can build businesses that stand on their own—independent of the cycle of debt that claims so many others.
True financial mastery, as many experienced owners in the community will attest, is not about how much you can borrow; it is about how much you can grow while remaining in control of your own future.