BRUSSELS — The economic landscape of the 20-country euro area faced renewed scrutiny in late October 2026 as fresh data from Eurostat revealed a notable uptick in industrial import prices. According to the latest update to the TEIIS011 dataset, the cost of goods entering the common currency bloc accelerated in August, reflecting complex global supply chain dynamics and shifting commodity valuations.
The European Union’s statistical office reported that the index of import prices for total industry reached 119.2 in August 2026, measured against a 2021 base of 100. This non-seasonally adjusted figure serves as a vital barometer for the health of the euro area’s manufacturing sector and provides early indicators of potential "imported inflation" that could impact consumer price indices in the months ahead.
Main Facts: A Snapshot of August 2026
The data released on October 24, 2026, paints a picture of a euro area grappling with rising external costs. The 1.0 percent month-on-month increase, while seemingly modest in isolation, underscores a broader trend of price sensitivity within the bloc’s industrial framework.
When viewed through a year-on-year lens, the picture becomes more pronounced. The 8.2 percent increase compared to August 2025 highlights a persistent inflationary environment that has challenged policymakers at the European Central Bank (ECB) throughout the year. The index, which tracks the price of goods—ranging from raw materials and energy inputs to finished intermediate products—entering the 20-country euro area, suggests that domestic industries are continuing to absorb significant cost pressures from international trading partners.
Chronology of Market Developments
To understand the trajectory of these figures, one must look at the broader economic calendar of 2026.
- Early 2026: The euro area began the year with cautious optimism, as supply chain disruptions from the previous year appeared to be stabilizing. However, fluctuating energy costs and geopolitical tensions in major shipping corridors kept import prices volatile.
- Q2 2026: Throughout the second quarter, industrial sectors across Germany, France, and Italy reported increased difficulty in sourcing affordable inputs. The Eurostat data began to show a slow, creeping rise in the import price index as currency fluctuations and logistical surcharges took their toll.
- July 2026: The precursor to the August data showed the market teetering, with businesses expressing concern over narrowing profit margins as they struggled to pass higher import costs down the value chain.
- August 2026: The reporting period saw a definitive spike. The index’s climb to 119.2 confirmed that the summer months had not provided the expected seasonal cooling in pricing, but rather a intensification of external inflationary forces.
- October 24, 2026: The formal publication of the TEIIS011 dataset provided the empirical confirmation needed by analysts to adjust their forecasts for the remainder of the year.
Supporting Data and Technical Context
The Eurostat dataset, "Import prices – total industry," is a non-seasonally adjusted index that provides a comprehensive view of the euro area’s external trade costs. By utilizing a 2021 baseline of 100, the index allows economists to isolate the cumulative impact of post-pandemic economic shifts.
Key Metrics:
- Index Value (August 2026): 119.2
- Monthly Growth Rate: +1.0%
- Annual Growth Rate: +8.2%
- Scope: 20-country Euro area (2023–2025 reference composition)
The non-seasonally adjusted nature of these figures is critical. While it can introduce fluctuations caused by predictable events—such as energy demand cycles or annual manufacturing shutdowns—it provides the most "raw" look at what importers are paying at the border. The 8.2 percent year-on-year increase is particularly significant when compared to the targeted inflation rates set by central banks, suggesting that the "imported" component of inflation remains well above target levels.
Official Responses and Market Analysis
While Eurostat serves as the neutral arbiter of these statistics, the implications have been echoed across the continent’s economic institutions. Analysts at the IndexBox Market Intelligence Platform have pointed out that the correlation between shipping volumes and import prices is becoming increasingly disjointed.
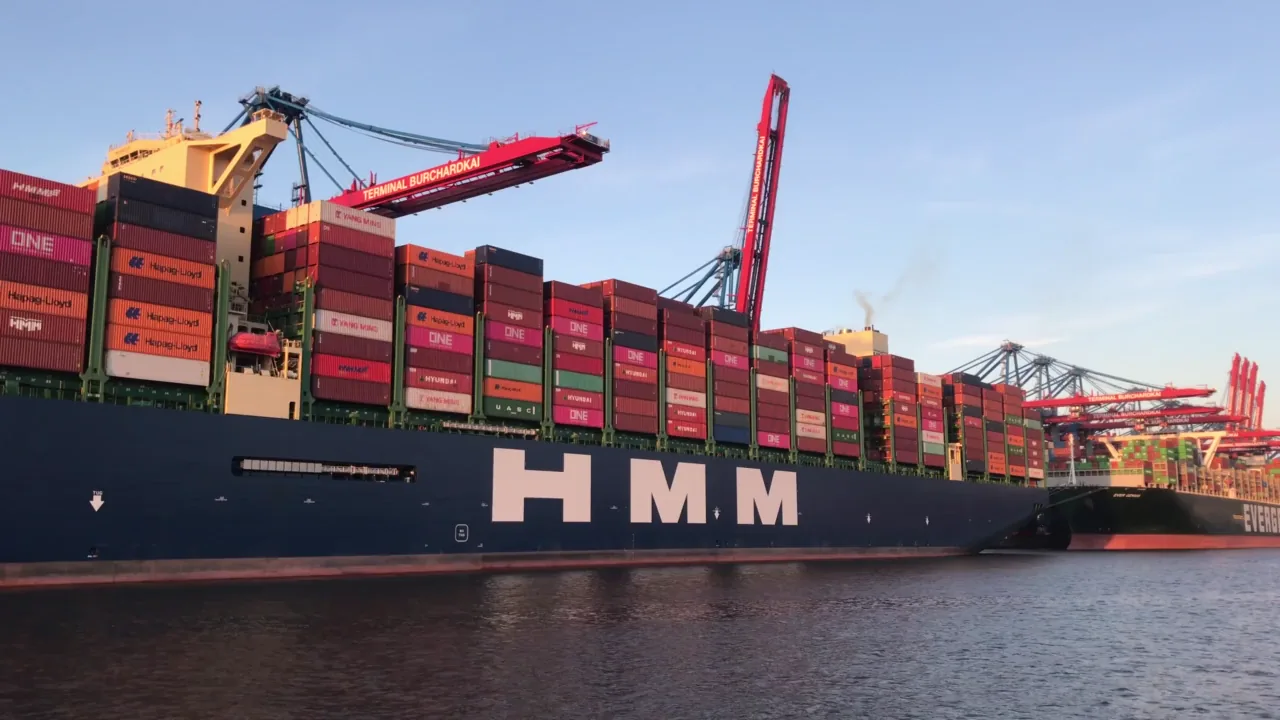
For instance, while U.S. container imports reached record levels in September 2026, the euro area’s experience in August showed that even without record-breaking volume, prices can climb due to supply-side constraints.
"The August data is a warning shot," noted a lead economist at a major European trade consultancy. "When you see an 8.2 percent annual jump in import prices, it suggests that the euro area is either paying a premium for scarcity or that the depreciation of the euro against the dollar is exacerbating the cost of commodity-denominated imports."
Industry associations have responded with calls for more robust trade policies. Small and medium-sized enterprises (SMEs) have been particularly vocal, noting that they lack the hedging capabilities of larger corporations to mitigate these price swings. Many firms are now forced to make a binary choice: absorb the cost and see margins evaporate, or pass the price increase to the consumer and risk losing market share.
Implications: The Road Ahead
The rising import price index has profound implications for the euro area’s macroeconomic stability.
1. The Inflationary Ripple Effect
Imported inflation is often a precursor to broader consumer price index (CPI) growth. As industrial inputs—such as metals, chemicals, and semi-conductors—become more expensive, the cost of manufacturing finished consumer goods rises. This suggests that the ECB may face a difficult environment in late 2026 and early 2027, where they must balance the need to curb inflation against the risk of stifling economic growth in an already fragile industrial sector.
2. Monetary Policy Dilemmas
If import prices continue to trend upward, the ECB may be forced to maintain higher interest rates for longer than previously anticipated. While high rates generally strengthen the currency, they also increase the cost of capital for the very industries that are already struggling with high input costs. It is a classic "catch-22" for central bank governors.
3. Supply Chain Resilience
The August data has reignited debates regarding the "near-shoring" of production. If the cost of importing goods remains persistently high, more European manufacturers may look to bring production closer to home to insulate themselves from global volatility. This could lead to a structural shift in the European industrial base over the next decade, focusing on regionalized supply chains rather than global ones.
4. Trade Balance Considerations
A higher import bill, if not matched by a commensurate rise in export prices, will inevitably weigh on the euro area’s trade balance. While the region remains a global powerhouse in high-end manufacturing, the increased cost of the components required to build these exports could dampen international competitiveness.
Conclusion
The release of the August 2026 import price data serves as a sobering reminder of the interconnectedness of the global economy. For the euro area, the 8.2 percent annual rise in industrial import costs is not merely a number on a spreadsheet; it is a signal of the ongoing struggle to maintain price stability in an era of geopolitical fragmentation and supply chain uncertainty.
As policymakers and industry leaders digest these figures, the focus will undoubtedly shift toward the Q4 performance. Will the 1.0 percent monthly increase be a localized peak, or is it the beginning of a sustained trend? With the European Central Bank monitoring these inputs closely, the coming months will be decisive in determining whether the euro area can successfully navigate these inflationary headwinds without sacrificing its industrial momentum.
For businesses operating within the bloc, the directive is clear: agility, efficient supply chain management, and a keen eye on the macroeconomic horizon are no longer optional—they are essential for survival in the current climate.
Source: Data derived from Eurostat dataset TEIIS011 and analysis provided by IndexBox Market Intelligence Platform. Official statistics are subject to future revisions as more comprehensive trade data becomes available.