In the high-stakes arena of e-commerce, the difference between a thriving enterprise and a cautionary tale often comes down to a single, overlooked skill set: financial mastery. While many founders obsess over customer acquisition costs (CAC), conversion rates, and SEO rankings, a persistent, silent killer lurks in the background: poor financial literacy. After two decades of observing the ebb and flow of the digital economy, the consensus is clear—being a master of your metrics is as critical to success as understanding your market. Perhaps, in the long run, it is even more so.
The landscape of modern entrepreneurship is littered with the wreckage of companies that scaled too fast, burned too bright, or simply misunderstood the fundamental mechanics of their own balance sheets. From cash flow crunches that paralyze growing operations to the dangerous allure of debt that takes years to unwind, the pitfalls are common. Yet, they are not inevitable. To bridge this gap, a comprehensive framework for financial mastery has emerged, designed specifically for store owners who want to move beyond "gut feeling" management.
1. The Core Philosophy: Radical Ownership
The first pillar of financial mastery is perhaps the most uncomfortable: Radical Ownership.
It is a natural human inclination to outsource the "boring" parts of a business. Entrepreneurs frequently hire accountants, fractional CFOs, and financial advisors, believing that by delegating the numbers, they are freed to focus on "the vision." While expert advice is essential, the delegation of responsibility is a fatal error.
Experts are advisors, not captains. They operate within the parameters of the data they are provided, but they do not share the sleepless nights of a founder. When a strategy backfires or a cash-flow crisis hits, the accountant may lose a client, but the founder loses a livelihood. True financial literacy requires that you own the decisions and their outcomes entirely. You must be able to interrogate your experts, challenge their assumptions, and understand the "why" behind every financial recommendation.
2. Deciphering the Financial Narrative
Financial reports—the income statement, the balance sheet, and the cash flow statement—are often viewed as bureaucratic hurdles or tax-season obligations. In reality, they are the heartbeat of the business.
The Interconnected Trio
- The Income Statement (P&L): Tells you if you are profitable over a specific period. It is the story of your operational efficiency.
- The Balance Sheet: Acts as a snapshot of your company’s health at a specific moment in time. It reveals your assets, liabilities, and, crucially, your equity.
- The Cash Flow Statement: The ultimate reality check. It tracks the movement of actual cash, which is often disconnected from the "profit" shown on a P&L.
When these three documents are analyzed in isolation, they provide a fragmented view. When understood as an interconnected narrative, they reveal exactly where you are leaking money, where your inventory is stagnating, and whether your marketing spend is actually driving long-term value. Mastery here is not about accounting expertise; it is about literacy—the ability to read the story the business is telling you before the numbers turn red.

3. Strategic Profit Levers: The "Big Three"
Not all financial activities move the needle with the same force. A common mistake among growth-stage founders is spreading their attention too thin. To achieve financial stability, focus must be applied to the "Big Three" profit levers:
- Pricing Strategy: A modest increase in price often drops directly to the bottom line with no increase in variable costs. It is the most powerful lever available to any business.
- Fixed Overhead Management: Keeping fixed costs lean during the growth phase provides the agility needed to pivot when market conditions shift.
- Post-Tax Profitability: Many entrepreneurs celebrate revenue, but the only number that truly builds personal wealth is what remains after the government takes its share. Optimizing for tax efficiency is not an afterthought; it is a core business strategy.
4. The Double-Edged Sword of Leverage
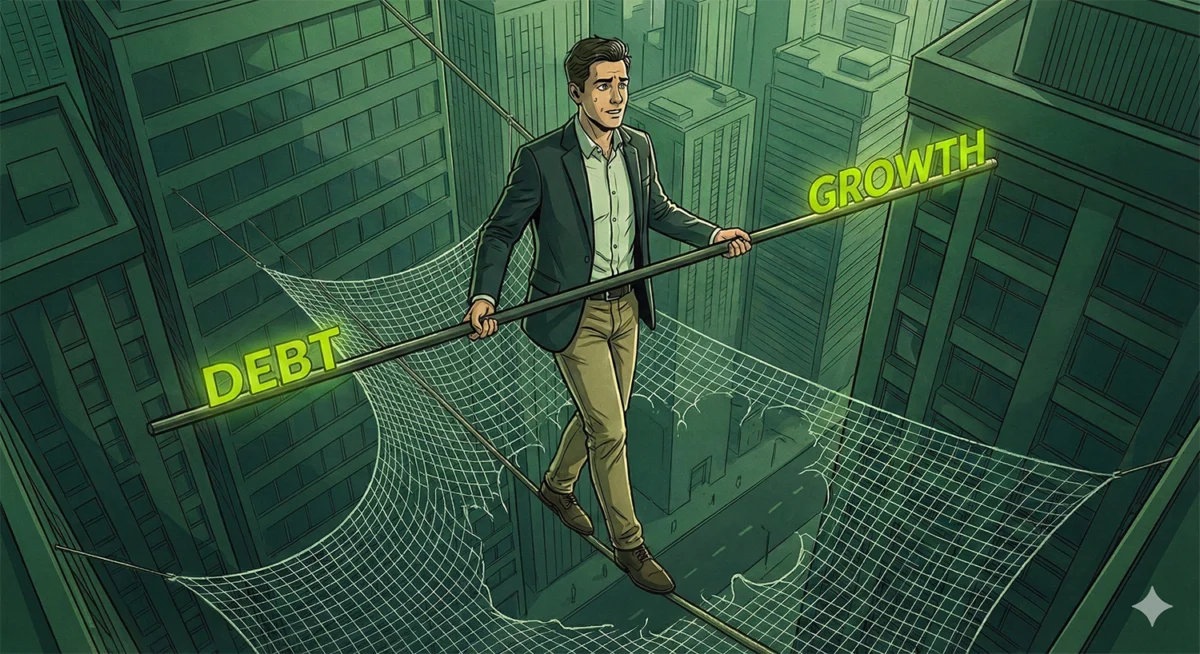
Debt is the great accelerator of business, but it is also the most common cause of collapse. In the current economic climate, leverage is often marketed as "easy money."
The danger lies in the time-horizon mismatch. Founders frequently take on debt based on a best-case scenario for growth. When market headwinds arrive—and they always do—the debt service remains constant while revenue fluctuates. The result is a liquidity crisis that can turn a healthy, growing business into a sinking ship overnight. The lesson for the modern founder is clear: leverage should be used to pour gasoline on a fire that is already burning, never to start one that isn’t. If you cannot explain exactly how the debt will generate a return that covers its own cost plus a significant premium, walk away.
5. Building Personal Wealth Beyond the Exit
A pervasive myth in the startup community is the "Exit-or-Bust" mentality. Founders often pour every dollar of profit back into the business, living lean in anticipation of a massive, multi-million dollar exit.
This is a high-risk gamble. Statistics show that the vast majority of businesses do not reach an exit, and even fewer reach the valuation the founder dreams of. Financial mastery requires building your personal balance sheet alongside your business. This means establishing a policy for taking dividends and investing in uncorrelated assets—real estate, index funds, or other ventures—well before you consider selling your company. If your entire net worth is tied up in your store, you are not an entrepreneur; you are a gambler.
6. Defining the Inflection Point: Financial Freedom
Financial freedom is often misunderstood as the ability to retire to a beach. For the high-achieving entrepreneur, however, retirement is rarely the goal. Instead, financial freedom is the ability to choose your work.
It is the point where the business no longer dictates your life out of necessity. When you reach this inflection point, the decision-making process shifts. You stop optimizing for "maximum possible profit" and start optimizing for "maximum possible meaning." This shift allows for more courageous leadership, as you are no longer making decisions out of fear of insolvency. Knowing your "enough" number is the key to transitioning from a grind-heavy operator to a strategic, purpose-driven owner.

7. The Psychology of Money: Evolving Your Habits
How you handle money is rarely a logical calculation; it is an emotional inheritance. We all carry deep-seated biases and patterns regarding money, often inherited from our upbringing.
Some founders have a "scarcity mindset," leading them to hoard cash even when reinvestment is necessary. Others possess a "growth-at-all-costs" bias, leading to reckless spending. Financial mastery requires a degree of self-reflection. You must identify your triggers—what makes you panic during a downturn? What makes you overspend during a boom? Correcting for these biases is just as important as balancing your books.
8. The Legacy Pillar: Passing It On
The final stage of financial mastery is the transition from accumulation to impact. If you have successfully navigated the previous seven pillars, you have built a powerful engine for change.
This involves two distinct responsibilities:
- Mentorship: The ecosystem of entrepreneurship thrives when those who have "made it" reach back to mentor those in the trenches.
- Intergenerational Wealth Education: If you have children, the greatest asset you can pass on is not money, but financial literacy. Teaching the next generation the principles of stewardship, investment, and responsibility is the ultimate test of your own mastery.
Conclusion: The Path Forward
The journey toward financial mastery is not a weekend workshop; it is a lifelong commitment to the health of your enterprise and your personal future. By mastering your reports, managing your leverage, and aligning your business with your personal financial goals, you transition from being a prisoner of your company’s cash flow to being the architect of your own destiny.
As we move forward, the complexities of the global economy will only increase. Those who treat financial literacy as a core competency—not just an administrative task—will not only survive the market’s inevitable cycles but will emerge as the leaders of the next generation of commerce. The framework is set; the responsibility is now yours.