The global energy landscape is currently defined by a precarious state of exhaustion. As inventories hit historic lows and geopolitical tensions threaten to sever critical supply lines, the U.S. diesel market has entered a period of extreme volatility. In a stark demonstration of this instability, ultra-low sulfur diesel futures on the CME surged by 20 cents in a mere two-hour window this week, leaving industry analysts and logistics operators reeling.
For those at the helm of the nation’s supply chain, the message is clear: the safety nets that once protected the market from price shocks are no longer functional. As one expert starkly put it, the industry is “running out of bullets.”
The Anatomy of the Surge: A Chronology of Volatility
The recent price spike serves as a case study in market nervousness. On Monday, the market experienced a brief dip into negative territory, a move that offered a fleeting sense of relief to a sector battered by months of inflation. However, the optimism proved short-lived.
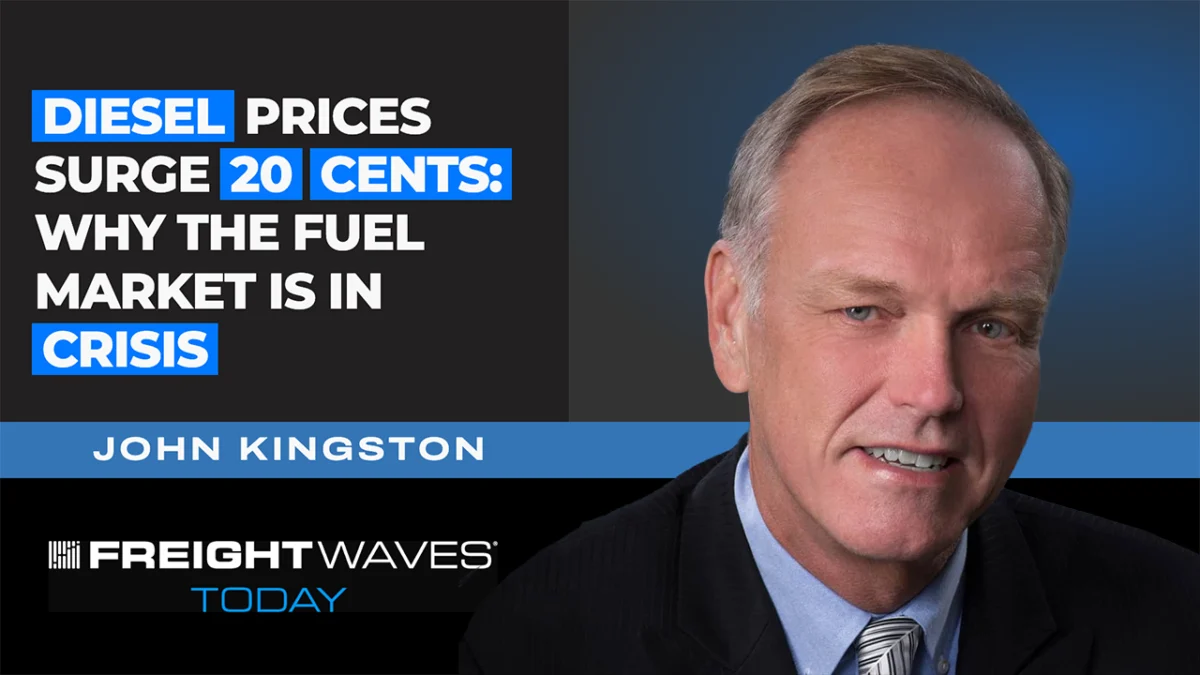
By Tuesday morning, the tide had turned with violent speed. Within a two-hour window, futures rebounded from a marginal loss to a 20-cent gain. This "whipsaw" effect is not merely a statistical anomaly; it is a manifestation of a market devoid of excess supply. John Kingston, a veteran energy market analyst for FreightWaves, observed the volatility firsthand, noting that the market’s inability to find a floor suggests that any minor disruption—whether a refinery maintenance issue or a geopolitical flare-up—now triggers outsized price reactions.
"In the last two hours, I’d be real worried if I was a diesel consumer," Kingston remarked during an interview. "I think what’s happening today is really, really concerning. There are no more bullets in the chamber. The inventories have been drawn down, and we are operating in a vacuum."
The Illusion of Policy Solutions: The "Red-Dyed" Problem
In a bid to mitigate the pain at the pump, the federal government has looked toward unconventional policy levers, including the authorization of "red-dyed" diesel for on-road use. Typically, red-dyed diesel is reserved for tax-exempt, non-road applications, such as agricultural machinery and construction equipment. By allowing this fuel to enter the general commercial trucking supply chain, the administration hoped to alleviate the immediate pressure on fuel availability.
However, industry experts argue that this policy is fundamentally disconnected from the logistical reality of the American fuel distribution system.
The Infrastructure Bottleneck
The supply chain for diesel is highly segregated. Red-dyed diesel is distributed through an agricultural and off-road supply network that rarely overlaps with the high-volume retail network serving interstate trucking. Major travel center chains—such as Love’s, TA, and Pilot—rely on a highly efficient, high-speed replenishment system that is not currently equipped to handle the legal and logistical complexities of red-dyed fuel.
"The supply chain is not set up to get red-dyed diesel out of the agricultural supply chain and down to the supply chain that includes Love’s, Pilot, and TA," Kingston explained.
Furthermore, the federal excise tax exemption tied to red-dyed diesel is a statutory creation of Congress. Because the executive branch cannot unilaterally waive these tax provisions, the administrative burden of implementing such a program for the remainder of the year creates more friction than benefit. For fleet operators, the cost of draining and reconfiguring storage tanks to accommodate a temporary, limited-use product is simply not economically viable.
Geopolitical Instability and Global Strategic Reserves
The volatility in the U.S. market is inextricably linked to the global energy theater. The fragility of international supply chains has become a recurring theme, particularly regarding the Strait of Hormuz.
A week prior to the recent price surge, there was a glimmer of hope as shipping flows through the Strait began to normalize toward pre-conflict levels. This uptick in supply provided enough stability to soften diesel prices momentarily. However, the latest data suggests those gains have been erased. Renewed reports of attacks on oil infrastructure in the region have reintroduced a "geopolitical premium" to the price of every barrel.
The Role of the IEA
Recognizing the severity of the crisis, the International Energy Agency (IEA) has stepped into an active coordination role. Under the guidance of Fatih Birol, the IEA has urged member nations to expedite the release of strategic petroleum reserves. Notably, the directive has shifted in focus: nations are now being explicitly asked to prioritize the release of diesel stocks over gasoline.
While the release of 100 million barrels of crude and products by G7 nations and Western allies has provided a temporary buffer, analysts warn that these reserves are not an infinite resource. Once these stockpiles are depleted, the market will lose its final line of defense against supply shocks.
The Long-Term Pivot: Is Electrification Inevitable?
As diesel prices threaten to break the $6-per-gallon barrier—with some projections suggesting even higher peaks—the economic calculus for the trucking industry is shifting. For years, the adoption of electric vehicles (EVs) in the heavy-duty sector was viewed as a long-term goal for the mid-2030s. Today, it is being viewed as a potential survival strategy.
Historically, major oil supply-demand reports from the OPEC, the IEA, and the U.S. Department of Energy have cited EV penetration as a primary driver of downward pressure on oil demand. With EV adoption rates for passenger vehicles reaching roughly 40% in markets like Norway and China, the writing is on the wall for the fossil-fuel-reliant freight sector.
"Higher diesel and fuel prices are likely to push fence-sitters toward electrification," Kingston noted. "It’s already been a factor in investment decisions, and it is almost certainly going to be a larger factor moving forward."
Implications for the Logistics Sector
For logistics providers and shippers, the current environment necessitates a shift in operational strategy. When fuel costs become the most volatile variable in a P&L statement, the ability to forecast and hedge becomes a critical competency rather than a luxury.
- Contractual Protections: Shippers and carriers must review fuel surcharge (FSC) agreements. Standard formulas may be insufficient in an environment where fuel prices can swing 20 cents in a matter of hours.
- Inventory Management: With the "buffer" of strategic reserves thinning, firms may need to reconsider just-in-time fuel purchasing strategies, favoring instead a more robust on-site storage approach where possible.
- Diversification: The volatility in diesel is serving as a catalyst for firms to accelerate the integration of alternative fuel vehicles into their fleets. While the transition is capital-intensive, the risk of remaining tethered to a volatile global oil market is becoming an existential threat to thin-margin logistics operations.
Conclusion: The New Normal
The recent market activity is more than a simple supply-and-demand mismatch; it is a reflection of a structural weakness in the energy sector that has been building for years. As geopolitical risks continue to disrupt the flow of oil, and as domestic policy options fail to bridge the gap between refinery output and terminal demand, the industry must brace for a period of sustained high prices.
The "running out of bullets" analogy from John Kingston serves as a sobering reminder. The global energy system is currently operating without a safety net, and in such an environment, the only certainty is that the next shock will be felt deeply across every sector of the economy. For the logistics and freight industries, the path forward requires not just careful navigation of the current storm, but a fundamental reassessment of how energy is sourced, stored, and utilized in a world where cheap, abundant fuel can no longer be taken for granted.